
Aftermath Silver Ltd
AAGAftermath Silver Ltd., an exploration stage company, acquires, explores, and develops mineral properties. The company explores for silver, gold, and copper deposits. It holds interests in the Cachinal and Challacollo property located in Chile; and Berenguela property located in Puno, Peru. The company was formerly known as Full Metal Zinc Ltd. and changed its name to Aftermath Silver Ltd. in April 2014. Aftermath Silver Ltd. was incorporated in 2011 and is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Aftermath Silver Ltd
Sector
Precious Metal
Founded
July 7, 2011
Reporting Currency
CAD
Contact Phone
604-484-7855
Website
aftermathsilver.comHeadquarters Address
409 Granville Street , Vancouver , BC V6C 1T2 , CA
Identifiers
ISIN
CA00831V2057Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos
Aftermath Silver($AAG | $AAGFF):推进 Berenguela 项目迈向预可行性研究阶段
Key Highlights
detailed- Williams says the Berenguela pre-feasibility study is on schedule and under budget and due in Q1 2027, framing it as the first time the project's economics (IRR and NPV) can be shown to the market and as the catalyst for a potential re-rating.
- The updated resource, per Williams, is about 51.5 million tonnes measured and indicated at 122.5 g/t silver, 0.63% copper and 5.69% manganese, plus roughly 14 million tonnes inferred, a 21% increase in the measured and indicated categories.
- Williams says test work has reached 99.9% high-purity manganese, the minimum battery grade, and that processing in the United States could realize about $2,000-2,500 per tonne versus $800-1,000 in China, with China kept as a fallback.
- Recent drilling includes 156 metres from surface grading 1.12% copper, 290 g/t silver and 7.3% manganese, plus 48.5 metres at 438 g/t silver and 2.2% copper, and Williams says the copper targets and a skarn area 4 km from the deposit will be drilled over the next year.
- Williams cites a C$20 million financing closed in December with no warrants and led by roughly 25% holder Eric Sprott, about $15 million in cash and 341 million shares outstanding, with a possible NYSE or NASDAQ uplisting after the pre-feasibility study.
Chairman Michael Williams argues investors buy Aftermath Silver for the silver and get its copper and battery-metal manganese for nothing. The updated resource estimate is 21% larger, with 51.5 million tonnes (measured-and-indicated, the two most reliable resource categories) at 122.5 grams of silver per tonne. Its pre-feasibility study (a detailed economic and engineering assessment) is due in Q1 2027, tracking on schedule and under budget. Newer processing now recovers about 95% of the silver and copper and 85% of the manganese, versus roughly 66% historically. Catalysts: copper drill results, Challacollo (Chile) assays, US processing plans worth $2,000-2,500 a ton versus China's $800-1,000, and a possible NYSE or NASDAQ move.

Beaver Creek 2026 - Best Stocks
Key Highlights
brief- Durrett says Aftermath is early stage with a PFS due next year, expects a low-cost large silver mine, and calls it under the radar at about $152 million.
- He places Aftermath in the group of names he rates as potential 30-baggers.
Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.
Derek Iwanaka of Prince Silver Corp. talks to Chen Lin | Metals Investor Forum Sept. 2026
Key Highlights
brief- The host cites Aftermath Silver as a comparable that solved manganese recovery after about two years and whose stock 'just took off' once that was announced, implied as a potential roadmap for Prince Silver.
Prince Silver targets a maiden 100M-ounce silver-equivalent resource in the coming months, with manganese excluded until metallurgical recovery is proven. Manganese grades run 8-10%, but the team waits on metallurgical testing before including it in the upcoming resource. Step-out drilling continues with an 87% hit rate, supported by more than 129 historical holes of data. Nevada's previously disturbed ground with old shafts eases permitting - an edge given manganese's US critical-metal status.
Rua Gold ($RUA | $NZAUF): Unlocking Reefton’s Historic Goldfield
Key Highlights
brief- The host argues Aftermath Silver could rank top-3 or top-5 in North America manganese despite the company name, citing a direct conversation with chairman Mike Williams and framing manganese as a huge revenue generator.
- The host suggests Aftermath should approach Toyota about offtake, framing the company's battery-grade manganese as a beneficiary of Toyota's upcoming lithium-ion battery production.
Reefton's Old Creek targets first antimony-gold concentrate by mid-2028 from a 25,000 oz/year starter mine with $130M CapEx. Nine undrilled historic mines at Reefton support a hub-and-spoke expansion that could roughly double throughput. Antimony co-product (25% antimony, 80 g/t gold) drew metal trader Mercuria into a $5M strategic investment. New Zealand's fast-track permitting compresses mine approvals to about six months; application is due October. Three oversubscribed, warrant-free raises let Rua Gold fund the permitting path with minimal dilution overhang.
Gold & Silver in Focus: Jurisdiction, Capital & Investor Priorities for 2026 | August 6, 2026
Key Highlights
detailed- Michael Williams outlines a pre-feasibility study due in Q1, with active drilling following up 150 meters of 1.12% copper, 290 g/t silver and 7% manganese at Aftermath.
- Williams cites the Berenguela resource at 122Moz silver measured and indicated plus 20Moz inferred, with roughly a billion pounds of copper and significant manganese credits.
- Aftermath plans a US processing facility (likely South Carolina) and has met with the Pentagon and the US Navy Undersecretary on Western-hemisphere critical-metals supply.
- Eric Sprott owns about 24% of Aftermath and ranks in Sprott's top 5 to 10 of around 140 holdings, providing retail signaling and a defensive block against hostile bids according to Williams.
Gold and silver sit at generational highs with structural fundamentals intact; both remain in the early innings of a multi-decade bull market. Junior mining equities have lagged physical metals despite record prices, creating a generational buying window for investors who pick the right teams. Grade and jurisdiction together drive valuation; Nevada, Ontario, Quebec, and Newfoundland command premiums that attract major capital today. Strategic backing by senior producers and funds like Fresnillo, Agnico, Alamos, and Eric Sprott acts as due diligence and signals quality. Capital discipline separates winners: leading juniors put 80 cents of every dollar into the ground and share evidence through steady news flow.
How Aftermath Silver $AAG | $AAGFF Plans to Recover Silver & Other Metals at Its Flagship Peru Proj
Key Highlights
detailed- The speaker says the company now uses a hydrometallurgical process that recovers 96% of the silver, 90% of the copper, and 87% of the manganese from the deposit, which he says makes extraction economic.
- He explains that past local mining recovered only about 67% of the silver because manganese and copper in the rock made commercial extraction very difficult.
- He notes the deposit outcrops right at surface and has been known for about a hundred years, with only roughly 2% of the ore body removed by local miners working high-grade silver at surface.
Hydrometallurgy (extracting metals with chemical solutions) now recovers 96% of silver, 90% of copper, and 87% of manganese, the speaker says. Earlier recoveries ran only 67% because manganese and copper in the rock made the silver commercially unrecoverable. The deposit reaches surface and has been known for a century, with only about 2% of the ore body removed. The speaker argues the improved recoveries are what make the company's flagship Peru project economically extractable.
Mineros ($MSA | $MNSAF) CEO on Growth Story, Investments & 2030 Gold Production Goals
Key Highlights
brief- The host notes Eric Sprott owns about 25% of the shares directly, not through Sprott Inc., and keeps participating in every financing.
- Don Durrett calls it a really good spec bet — silver-heavy with manganese and copper in Peru and Chile — with the market still waiting on a PEA or a possible skip straight to PFS.
Mineros S.A. trades at 0.47 times net asset value (what its mines and cash are worth) despite a tenfold share-price re-rating under Sun Valley control. Sun Valley Investments deployed about $200 million to take control, then doubled silver recovery and lifted gold output 22% through operational fixes. Guidance rose to 240,000 ounces with costs tracking below plan, and the CEO targets 500,000 ounces by 2030 via the Porvenir project and acquisitions. An upsized $175 million buyback and $30 million dividend program return cash, while a strategic gold reserve keeps bullion in company vaults. Analyst Don Durrett argues quality mid-tier gold producers are the sweet spot, and Mineros still offers tenfold upside on his $7,000 gold assumption.
Aftermath Silver ($AAG | $AAGFF): Peru Silver Project with Significant Manganese Potential
Key Highlights
detailed- The guest frames flagship Berenguela in southern Peru as roughly the 11th-largest undeveloped silver asset globally, with 144 million ounces of silver (120 Moz measured and indicated, 20 Moz inferred), about a billion pounds of copper and roughly 3 million tonnes of manganese.
- He says the pre-feasibility study lands in Q1, likely January, with a production decision in 18-24 months; he models about 3 Moz of silver in year 1 rising to roughly 5 Moz a year from years 2-6, with production possible around 2030-31.
- Manganese is the differentiating metal in his thesis: he says US buyers pay roughly $2,500/t against about $1,000/t in China, and that the US government has signalled interest in helping fund a processing plant in South Carolina or Georgia, after the company was invited to the Pentagon two months earlier on Navy drone demand for manganese.
- Drilling to date is close to 190 holes at a 95-97% hit rate, with highlights including 156 m at 1.12% copper with 290 g/t silver and 7.3% manganese, and roughly 48-50 m at 438-450 g/t silver with 2.2% copper; the eastern high-grade copper zone and a skarn target 4 km away are next drill targets, with skarn results hoped for by August 2026.
- Aftermath owns 100% of Berenguela, of Chaya Coyle in Chile and of a third Chilean project, with no earn-in payments outstanding; it paid $21m in cash and stock for Berenguela when its market cap was about $25m, against roughly $200-250m at the time of this interview.
Michael Williams argues Berenguela's silver, copper and battery-grade manganese give Aftermath an unusual choice: develop the deposit or sell it. Eric Sprott holds roughly 25% after backing a $20 million December financing at 90 cents, with shares now trading below that level. Ore reaching the surface supports an open pit with a roughly one-to-one strip ratio, meaning less waste rock and lower upfront capital. Hydrometallurgy lifts recovery to about 96% silver, 90% copper and 87% manganese, against the 67% achieved by historic surface workings. The guest points to three near-term catalysts: a January pre-feasibility study, a skarn drill test, and follow-up on high-grade copper intercepts.

Honey Badger Silver ($TUF.V | $HBEIF) Acquires Prairie Creek | Don Durrett & John Feneck Interview
Key Highlights
detailed- Durrett put Aftermath on his buy-the-dip list of roughly 25 names, screened for 15x or better against his $200 silver case.
- He says Aftermath is waiting on a preliminary economic assessment, and Williams compares it as trading at about a one third valuation on enterprise value per ounce against his own company.
- He argues paying so little for the silver in the ground at Aftermath is hard to justify, particularly if silver moves toward $200.
- Feneck presented Aftermath on his silver panel, trading as AAG in Canada and AAGFF in the US, as a name they had discussed before.
Chad Williams says Prairie Creek anchors a 650 million ounce silver-equivalent portfolio bought at a deep discount to peers. Prairie Creek is a 1982 mine restart, roughly 95% built, with three miles of underground development and an existing mill. Byproduct credits from zinc, lead, germanium and tungsten could hold Prairie Creek's cash costs far below the silver price. Don Durrett frames the sector as washed out: the HUI gold-miner index sits 26% below its high, yet quality developers trade at fractions of peers. Durrett stays cautious until the company publishes an updated resource estimate, a PEA and a capital cost plan.

Gold/Silver Miner Buy The Dip List (June 2026)
Key Highlights
brief- He frames Aftermath Silver as a long-term story with no PEA yet, which he says is what is needed to put a value on it.
- He says the project has a lot of silver and that manganese credits would make it a low-cost silver operation, but there is no timeline yet to production.
Gold and silver broke below their 200-day moving averages, and the host calls the 25% to 47% drop a buyable correction in a bull market. His trigger is the gold-to-S&P 500 ratio — gold's price divided by the index — near 0.6 today; 0.8–0.9 signals gold outperforming stocks. The watchlist spans producers, developers and explorers, with price assumptions of $7,000 gold and roughly $175 to $190 silver. Producers adding ounces rank above one-off development stories, since incremental production flows straight to free cash flow and lifts valuations quickly. He expects another, deeper dip before year-end tied to an S&P selloff, so he is assembling names to buy at lower prices.
Silver at $75, and This Project Has 224 Million Ounces | Michael Williams - Aftermath Silver
Aftermath Silver's Berenguela project holds 224 million ounces of measured and indicated silver, with copper and manganese co-products enhancing potential economics. Prefeasibility study expected in Q1 next year, with higher silver prices potentially accelerating the company's development strategy. U.S. government interest in Western Hemisphere manganese supply adds strategic value to the project alongside ongoing silver industrial demand deficits.

The Arsenal of Electrification – Securing the North American Defense | April 30, 2026
Key Highlights
detailed- Michael Williams says Aftermath's Berenguela project in Peru could be the biggest high-purity manganese deposit globally, with the company looking at processing the material in the United States.
- The introduction frames Berenguela as transitioning from a silver-only story into a critical minerals source with roughly 900 million pounds of copper plus high-purity manganese potential.
- Williams argues a silver crunch is already here after a six-year supply deficit, with silver at about $75 as of the April 30, 2026 panel versus roughly $16 when Aftermath acquired Berenguela five years earlier.
- The company raised $20 million in equity for an unusually thorough pre-feasibility study that is halfway done and due in about 8 to 10 months from the panel, with Williams expecting substantial US government engagement once it finishes.
- Williams notes high-purity manganese takes 18 months to two years of qualification testing, and that US processing prices of $2,000 to $2,500 per ton (projected to reach $4,000 to $5,000 in 5 to 6 years) compare with about $1,000 in China.
Defense demand and bipartisan US policy are turning niobium, lithium, boron, and silver into national-security commodities carrying a permanent premium. Panelists argue China's decades of price suppression closed Western mines, leaving processing capacity, not geology, as the West's real bottleneck. Capital-intensive, hard-to-refine minerals struggle to attract private capital, so government backstops like Ioneer's $996 million US Department of Energy loan and price floors matter. Only about a dozen niobium or tungsten junior miners exist, so the panel urges screening management quality and permitted, financed status before investing. Silver's six-year supply deficit and 50-65% industrial use show how strategic demand can reprice a commodity the market long ignored.
Don Durrett & John Feneck Explore First Tellurium’s ($FTEL | $FSTTF) PyroDelta Energy Stake
Key Highlights
detailed- Don says he bought more Aftermath Silver shares on the day of recording because he felt underweight relative to what the company owns, adding that he likes the stock a lot.
- The host cites roughly 800 million silver-equivalent ounces and a share price of about 53 cents US at recording, down from a peak near $1.10, calling the story 'clicking on all cylinders.'
- The host notes a longtime contact named Michael holds a huge position in the stock.
PyroDelta's thermoelectric generators (solid-state devices that turn waste heat into electricity) need only a 20°C differential and run 24/7. First Tellurium (CSE: FTEL), which management calls the world's only tellurium-focused company, owns 83% of PyroDelta plus a high-grade British Columbia project. Acceptance into DARPA's Lift Challenge (Dayton, Ohio, August 2) brings prize potential and introductions to defense primes and drone-delivery buyers. Durrett argues small silver producers gain huge margin above $200 silver, though he cautions developers take years and often disappoint before paying off. Co-hosts note 131 million shares out with roughly 35% in friendly hands, giving the 11-cent junior room to move on DARPA news.
Optionality Update - April 2026
Key Highlights
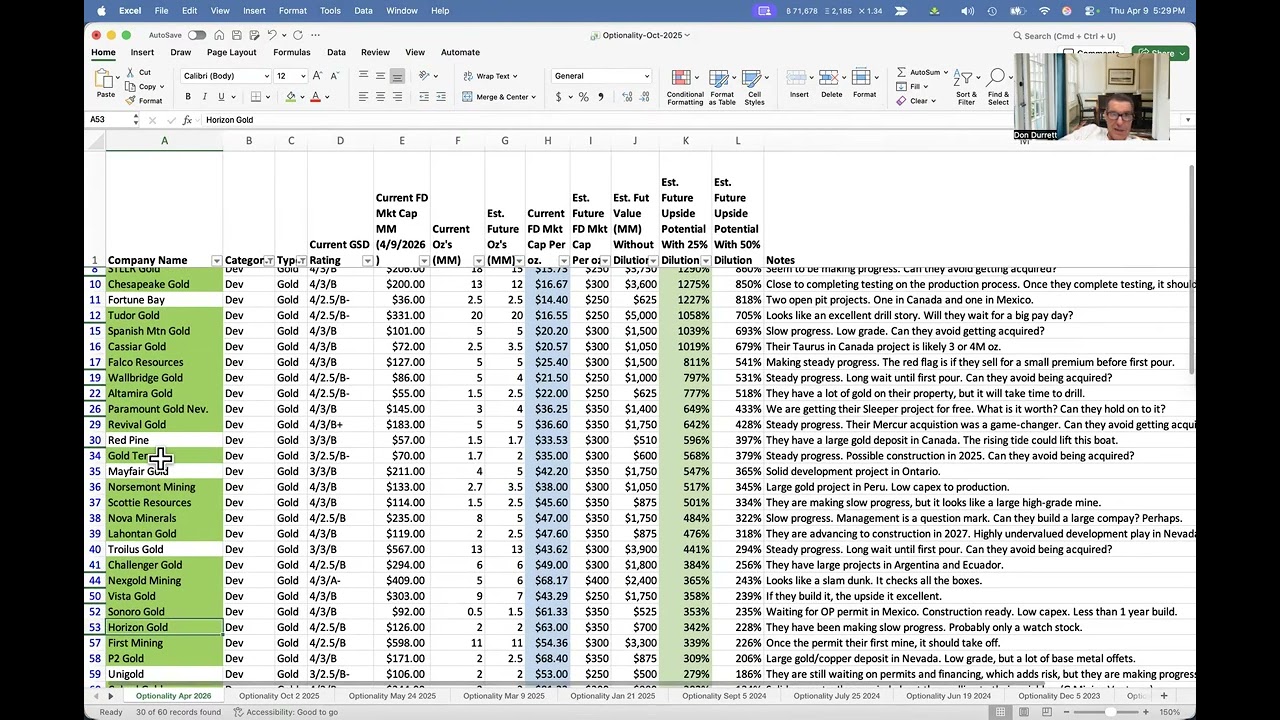
brief- Durrett owns Aftermath Silver and projects it reaches $5 per ounce as a silver developer.
- He notes the market is waiting for a PEA on the Berenguela project, which he expects to be a catalyst.
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Live Q&A with Rick Rule and Albert Lu
Key Highlights
brief- Rule declines to comment on Aftermath Silver's largest project because he has not yet finished his own review of it.
Rule argues Gulf-driven commodity spikes are anticipatory, not rationing, and warns credit stress could escalate into a 2008-style liquidity squeeze. He is building personal cash because bond ETFs promise retail liquidity while holding illiquid bonds, a mismatch that could gate redemptions. Net present value (discounted future mine cash flows) ignores cash beyond its 8-9 year horizon, so it understates long-lived copper deposits. Thirty years of copper underinvestment, grades down to 0.4%, and a $250 billion capex gap make copper supply extraordinarily bullish, Rule argues. G Mining's takeover of G2 Goldfields joins contiguous Guyana ground, removes financing risk, and lifts combined output above 500,000 ounces of gold.

Newsletter Favorites Upside (using New GSD Defaults)
Key Highlights
brief- The host calls Aftermath Silver a long-term development play working on a PFS, saying it needs to advance but has huge leverage.
Raising default price assumptions to $7,000 gold and $200 silver reflects conviction that current metal prices undershoot the macro setup. Screening 90 favorite miners at those prices prints 20-plus-bagger upside for many, but most need three-to-four-year mine builds first. Near-term producers like Guanajuato Silver need no new growth, so they offer immediate leverage if silver reaches $200. A gold-silver ratio squeeze toward 2.5-3% underpins the $175-200 silver target alongside $7,000 gold within 24-36 months. Timeline to getting paid is the key filter: the longer a mine build, the longer investors must wait for the printed upside.

Newsletter Favorites Overview (Feb 2026)
Key Highlights
brief- Don says Aftermath Silver is coming out with a PFS that everyone has been waiting for, which will show how fast it can get its project into production.
Durrett argues there is limited time left to buy gold and silver producers while they are still cheap, expecting one more significant dip. His Newsletter Favorites list leans on quality Canadian and Australian mid-tier producers, which he expects to re-rate as the bull market warms up. Companies whose second and third projects get no market value offer free upside — you pay for the first asset and get the rest for nothing. Cheap forward free-cash-flow multiples persist in West Africa and among silver producers, where weak sentiment discounts heavy leverage to metal prices. Australian producers like Ramelius reaching major-sized valuations is, in his view, the first sign the junior gold bull market is broadening.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.