First Majestic Silver Corp logo

First Majestic Silver Corp

AG

First Majestic Silver Corp. engages in the acquisition, exploration, development, and production of mineral properties with a focus on silver and gold production in North America. It holds 100% interests in the San Dimas Silver/Gold Mine covering an area of 71,868 hectares located in Durango and Sinaloa states; the Santa Elena Silver/Gold Mine covering an area of 102,244 hectares located in Sonora; Jerritt Canyon gold mine that covers an area of approximately of 30,821 hectares located in Elko County, Nevada; and the La Encantada Silver Mine covering an area of 4,076 hectares situated in Coahuila, as well as surface land ownership of 1,343 hectares. The company also holds 100% interests in the La Parrilla Silver Mine that covers an area of 69,478 hectares located in Durango; the Del Toro Silver Mine consisting of 3,815 hectares of mining concessions and 219 hectares of surface rights located in Zacatecas; the San Martin Silver Mine includes 33 mining concessions covering an area of 12,795 hectares located in Jalisco; and the La Guitarra Silver Mine that covers an area of 39,714 hectares located in Mexico. In addition, it holds interest in the Springpole project, a gold and silver project covering an area of approximately 41,913 hectares in Ontario, Canada. The company was formerly known as First Majestic Resource Corp. and changed its name to First Majestic Silver Corp. in November 2006. First Majestic Silver Corp. was incorporated in 1979 and is headquartered in Vancouver, Canada.
Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

First Majestic Silver Corp

Sector

Precious Metal

Founded

November 28, 2006

Employees

4,000

Reporting Currency

USD

Contact Phone

16046883033

Headquarters Address

925 West Georgia Street , Vancouver , BC V6C 3L2 , CA

Identifiers

CUSIP

32076V103

Commodity Portfolio

AG Silver Primary
AU Gold Secondary

Stock Exchanges

AG NYSE • USD
AG:NYSE
FR TSX • CAD
FR:TSE

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

I'm Buying These Gold & Silver Stocks 'Hand Over Fist': John Feneck

I'm Buying These Gold & Silver Stocks 'Hand Over Fist': John Feneck

Commodity Culture
4 days ago 30:57

John Feneck says the backdrop for gold and silver has never looked better, and he is buying gold equities hand over fist for leverage. He runs a hub and spoke portfolio, holding ETFs like GDX as the core and selling satellite juniors after 200 to 300 percent gains. He expects a 25 basis point Fed hike on December 9, sees gold support at 3,900 to 4,000 dollars and prefers equities over bullion. His picks span BlackRock Silver, the Silver 47 Bunker Hill merger, Triumph Gold, Western Star tungsten and First Phosphate. Gold miners are 0.1 percent of the investable universe, and he sees potential sector rotation when the tech led bull market changes.

Kingsmen Resources – New Structure Encountered Which Intersected 218g/t Silver Eq over 6.5 Meters

Kingsmen Resources – New Structure Encountered Which Intersected 218g/t Silver Eq over 6.5 Meters

The KE Report
5 days ago 12:36

Key Highlights

brief
  • Scott Emerson cites First Majestic's Los Gatos project in Chihuahua as an example of regional mines running deep, around 500 metres, when explaining why Kingsmen plans to follow the mineralization before committing to deep holes of its own.

Kingsmen Resources reported 218 g/t silver-equivalent (gold credits converted into silver terms) over 6.45 metres on a newly identified third structure at Las Coloradas. Drillers targeted blind mineralization — ore not visible at surface — where mapping showed cross-cutting structures, a setting that often traps high-grade ore. Roughly 50-metre step-outs are underway on the new structure, and 11 holes are already at assay labs with results batching out for months. About 5,000 of the planned 10,000 metres are drilled; $13.5 million in cash funds multi-rig drilling through mid-December, restarting around January 20. Nearby Chihuahua mines run 500 metres deep, so the CEO plans to follow mineralization down gradually rather than commit early to deep holes.

Sierra Madre Gold and Silver – Ramp Up To 720tpd At The La Guitarra Complex & Exploration Strategy

Sierra Madre Gold and Silver – Ramp Up To 720tpd At The La Guitarra Complex & Exploration Strategy

The KE Report
7 days ago 16:58

Key Highlights

brief
  • The guest confirms Sierra Madre acquired the Del Toro silver complex - a past-producing, fully permitted site with three mines and a 3,000 tpd plant - from First Majestic, with the deal closing at the end of June.
  • The CEO notes First Majestic was among previous operators that did some mapping and a little drilling in one area of the East District, but there has been essentially no modern exploration there since the late 1930s.

Phase 1 expansion lifted La Guitarra throughput over 40% to 720 tonnes per day (tpd — ore milled daily), with 1,500 tpd targeted by next year. Management expects costs to drop about $5 per quarter for the next four to five quarters as development charges roll off and grades rise. A 30,000-metre drill program across the La Guitarra East District targets up to 40 veins in mines untested by modern drilling since the late 1930s. The Del Toro acquisition adds a past-producing, fully permitted complex with a 3,000 tpd plant, plus a parallel 30,000-metre drill program from next year. About $25 million in working capital and positive cash flow fund the expansion and 60,000 metres of planned drilling across the two projects.

Adrian Day: Broken Bond Market

Adrian Day: Broken Bond Market

Mining Network
14 days ago 37:44

Key Highlights

brief
  • Orogen's royalty cash flow comes from the Ometeño mine, described by the guest as First Majestic's flagship mine in Mexico.

Adrian Day argues the 30-year Treasury near 5.5% shows the bond market is close to broken, with too few buyers willing to lend long term. Gold is holding up against a strong dollar, rising oil and higher yields — which he reads as confirmation that the bond market is strained. He expects the Fed to become buyer of last resort for Treasuries, a step he says would be inflationary and justify gold ownership. Beaver Creek mining companies are well cashed up and senior producers are again eyeing early-stage projects, without the reckless 2011-era deal-making. He discloses a long position in Origin Royalties, a junior with cash and a royalty (a revenue share) that avoids dilution.

AI Is Making Silver’s Six-Year Deficit Worse | Mani Alkhafaji -  First Majestic Silver

AI Is Making Silver’s Six-Year Deficit Worse | Mani Alkhafaji - First Majestic Silver

The Deep Dive
18 days ago 6:43

Key Highlights

detailed
  • Jerritt Canyon restart is the headline update: $75M committed earlier in 2026, the guest says execution is ahead of schedule with purchase orders issued for a brand new fleet and managerial/supervisory recruitment tracking ahead of plan; a formal study is targeted by end of 2026 with publication in Q1 2027, and the stated goal is an H2 2027 production restart.
  • Santa Elena expansion is described as the next leg of growth at that operation, with two portals currently underway.
  • A substantial exploration program is ongoing at San Dimas and Los Gatos, with the guest flagging more updates to be released over the coming months.
  • Portfolio strategy is to focus on district-scale silver assets and divest smaller past-producing mines to juniors — the La Preciosa assets were sold to Silver Storm — while retaining an equity position to keep upside exposure.
  • The interview frames First Majestic against Mani's structural-deficit silver thesis: consumption has exceeded mine supply for six straight years, and AI/data-center demand (he cites ~6.5 tons of silver per 50 MW data center) plus resurgent solid-state-battery and solar-panel consumption are adding further pressure on top of the current deficit.

Silver has run a structural supply deficit for six years, and AI/data-center buildouts are now widening it beyond current forecasts. A 50 MW data center alone consumes about 6.5 tons of silver — a single demand source not yet matched by new mine supply. First Majestic's $75M Jerritt Canyon restart is running ahead of schedule, with a formal study expected by Q1 2027 ahead of H2 2027 production. First Majestic is divesting sub-2 Moz (million ounce) producers so management can refocus on district-scale assets like Santa Elena, San Dimas, and Los Gatos. Retail silver demand softens when prices pull back — historically June through August are the seasonal lows before Q4 and Q1 recover.

Barrick–Newmont Nevada JV, Permitting Risk, Royalties, and Mine Financing | Analyst Joe Mazumdar

Barrick–Newmont Nevada JV, Permitting Risk, Royalties, and Mine Financing | Analyst Joe Mazumdar

MiningStockEducation.com
28 days ago 51:52

Key Highlights

brief
  • Per the guest, Orogen Royalties' 2% NSR on Ermitano — a First Majestic asset in Mexico — became a producing, cash-flowing royalty, which helped keep the royalty generator out of the equity market.

Barrick is selling Fourmile at a steep discount, but access to permitted autoclave (pressure oxidation) capacity via Goldrush justifies it. Seabridge's KSM court setback shows Indigenous consultation now extends beyond a project's footprint, raising permitting risk across British Columbia. Major gold producers returned roughly 30% of first-half 2026 revenue to shareholders, with buybacks outpacing dividends and the top five dominating. Judge management on per-share value: grow assets without growing the share count, and favor teams that raise capital at rising prices. Coffee's upfront capital quadrupled in a decade, reinforcing the case for hunting fatal flaws early — cutoff grades, jurisdictions, and site visits.

Sierra Madre Gold & Silver – Q2 Operations, Financial, Exploration Update At La Guitarra & Del Toro

Sierra Madre Gold & Silver – Q2 Operations, Financial, Exploration Update At La Guitarra & Del Toro

The KE Report
about 1 month ago 21:13

Key Highlights

brief
  • The CEO notes Sierra Madre paid off its $4.5 million First Majestic loan more than a year ahead of a three-year term, at 50% interest, from operating cash flow.
  • First Majestic is also referenced as a past operator that developed some of the underground levels Sierra Madre is now reopening at La Guitarra.

Daily throughput at La Guitarra climbed 34% to 672 tpd, with a new ball mill set to push capacity to roughly 1,400-1,500 tpd. Q2 AISC (All-In Sustaining Cost — what it really costs to produce an ounce) jumped to $5,473 from $3,254 on FX, development, and lower-grade ore. Sierra Madre plans a year of mapping at Del Toro's three past-producing mines and 3,000 tpd mill before any restart decision. Phase 1 drilling at La Guitarra begins early Q4 with 13 long holes; Del Toro drilling is slated for mid-2027 — roughly 60,000m combined. Repayment of the First Majestic Silver term loan leaves Sierra Madre with $22.2M cash and $25M working capital and no funded debt.

Silver Miners Will Crush Gold Miners | Adrian Day

Silver Miners Will Crush Gold Miners | Adrian Day

The Deep Dive
about 1 month ago 32:36

Key Highlights

brief
  • Adrian Day discloses he personally owns First Majestic Silver but notes its Ermitaño deposit, which feeds the Central Elena mine, is currently producing 'much more gold than silver.'
  • He uses First Majestic as an example that even 'purer' silver names still generate substantial gold by-production, blurring the line between silver and gold producers.

Day reads gold holding up against rising yields as a sign of underlying strength, and expects a stressed US bond market to eventually drag the Fed back in. Day calls Barrick's Fourmile-for-Nevada-Gold-Mines swap with Newmont an "awful deal," estimating Barrick effectively paid roughly $6-7B to clear its IPO path. Day expects Franco-Nevada to keep its $2B cash powder dry until a high-quality royalty deal surfaces, with Metalla Royalty floated as a possible fit. Over the next 1-2 years, Day prefers purer silver producers over gold producers, citing deeper pullbacks and stronger implied upside. Day flags many "silver" producers for actually mining more gold than silver, including Pan American Silver and First Majestic's Ermitaño deposit.

John Feneck: Silver's Bull Market Isn't Over

John Feneck: Silver's Bull Market Isn't Over

VRIC Media
about 1 month ago 29:15

Key Highlights

brief
  • John calls First Majestic one of the few pure silver producers investors can buy, contrasting it with the gold-forward silver-byproduct producers that dominate the space.
  • Feneck Consulting holds First Majestic indirectly through silver and gold ETFs (GDX, GDXJ, SIL, SILJ, SLVP) rather than as a direct position, as John describes on the show.

Physical silver is Feneck's largest position (~11.5%) on a sub-$17 cost basis; he adds on dips in the $50-$55 range. Silver developers look compelling: production AISC (All-In Sustaining Cost — what it really costs per ounce) of $25-$30 vs silver near $70. Mining equities are starting to move three-to-one with metals, a leverage regime that returned in late July after years of one-to-one. Tungsten, not rare earths, is the more actionable critical-mineral play — China controls ~81% of supply and there's no futures market. He reads the Fed as more market-friendly than the headlines, noting only ~50bps of cuts are priced in by late next July.

SILVER Manipulators Failing - Move Back to $120 Will Be 'Very Quick': Mario Innecco

SILVER Manipulators Failing - Move Back to $120 Will Be 'Very Quick': Mario Innecco

Commodity Culture
about 1 month ago 38:45

Key Highlights

brief
  • The guest describes First Majestic as one of the 'good' major silver producers, paying dividends and generating 'huge' cash flow.
  • He treats First Majestic as undervalued versus the silver price and expects a metal-price re-rating to be the main catalyst for the major silver miners.

Mario Innecco reads silver's defense of the $70 level by paper markets as a delaying action, expecting the next leg back to $120 to be fast. He flags the persistent Basel III tier-one narrative and a roughly 12% Shanghai silver premium as evidence that physical demand is outrunning paper selling. The guest argues a US Treasury gold revaluation, last done in 1973, would add balance-sheet liquidity but would debase the dollar against real goods. He calls mining equities undervalued versus gold and broad stocks, yet recommends keeping most savings in physical metal and using miners as a smaller speculative sleeve. He warns that tungsten supply is roughly 85% controlled by China and North Korea, a Western vulnerability now drawing UK government investment in domestic projects.

What's Behind Huge SILVER Premium in Shanghai? 'This Isn't Supposed to Happen': Chris Marcus

What's Behind Huge SILVER Premium in Shanghai? 'This Isn't Supposed to Happen': Chris Marcus

Commodity Culture
about 1 month ago 35:15

Key Highlights

brief
  • Marcus recalls a 2024 conversation with someone at First Majestic about the then-unusual ~$3 COMEX-Shanghai spread; the First Majestic contact said China smelters were already reaching out directly to Latin American silver producers.

Persistent Shanghai silver premium above $8 for eight-plus months signals a physical supply squeeze the paper arbitrage cannot close. India's import-license delays cascaded into a London shortage, pulling metal from China and COMEX and reinforcing the squeeze. Most silver is mined as a by-product (a secondary credit from mining another metal), so $65 silver still drives strong free cash flow at producers. Mining-stock valuations look disconnected from spot prices because Wall Street models assume $3,000 gold and $40 silver, not current levels. A bond-market crisis or US gold revaluation remains a multi-year tail risk that the guest says could push silver dramatically higher.

Mario Innecco: Imminent Financial Repression, Decade-Long Bear-Market for Bonds & Gold

Mario Innecco: Imminent Financial Repression, Decade-Long Bear-Market for Bonds & Gold

Palisades Gold Radio
about 1 month ago 53:07

Key Highlights

brief
  • Mario cites First Majestic CEO Keith Neumeyer as arguing the gold-silver ratio should be closer to 7-8:1 based on mining production ratios, where 7-8 ounces of silver are produced for every ounce of gold found
  • First Majestic is described as one of the few pure silver plays in the mining sector amid a 5-6 year silver supply deficit

Bond bull ended in 2021, debt-driven financial repression is forcing capital toward hard assets — secular commodities bull market underway. Gold and silver are scarce stores of value that cannot be printed, hedging the devaluation of fiat currencies under rising debt. Japan is the most leveraged creditor nation; its repatriation of overseas capital could destabilize global bond markets. Precious metals remain under-owned at under 1% of investable assets in the West, leaving room for institutional re-rating. Silver could outperform gold on industrial demand, persistent supply deficits, and possible Basel III tier-one status.

Live Q&A with Rick Rule and Albert Lu

Live Q&A with Rick Rule and Albert Lu

Rule Investment Media
about 2 months ago

Key Highlights

detailed
  • Rick says Keith Neumeyer is spending 30 million on a drilling campaign aimed at answering whether Jerritt Canyon has enough non-refractory and refractory ore left to justify a H2 2027 restart
  • Rick notes the last four operators tried to milk Jerritt Canyon for cash, leaving the asset very unloved and starved for capital
  • Rick advice is to wait for the drill results and the implied resource and NPV rather than anticipate a restart
  • Rick framing: the best place to look for gold is in the shadow of a head frame

Oil setup toward 2029 reflects deferred sustaining capex of $1B per day, with Venezuela reopening adding limited supply. Value prospect generators by multiplying third-party drill spend by the carried interest, then subtracting G&A — the synthetic profit measure. Anchor mining NPV discount rates to the host sovereign rate plus a 3-4% risk premium; US, Canada, and Australia use the project WACC instead. Press winners by trimming as price approaches value — Rick cut Paladin at $1.25, $3, and $6, pausing whenever a smart new buyer emerged. Northern exploration stocks typically get crushed each winter without news; March or April entries exploit the seasonal weak-handed selling.

Silver Prices Exploded. New Supply Never Came. |  First Majestic

Silver Prices Exploded. New Supply Never Came. | First Majestic

The Deep Dive
about 2 months ago

Key Highlights

detailed
  • Management says production from the same four mines barely changed, yet a record $40 million free-cash-flow quarter at $32 silver in spring 2025 turned into roughly $220-250 million a year later.
  • Two discoveries near Santa Elena added over 90 million ounces of silver-equivalent as incremental resource in a March update; permits came an estimated 12-18 months early, with production from the two finds framed 2-3 years out (as of August 2026).
  • The company holds about $1.2 billion in cash, says it does not need to raise money, and has committed to more than 300,000 meters of drilling in 2026; Santa Elena discovery costs are cited at about $0.32 per ounce.
  • Jarrett Canyon in Nevada, shut since early 2023, is being restarted with a $75 million commitment targeting the second half of 2027 at 125,000-150,000 ounces of gold a year; management says it currently carries zero value on the books.
  • Growth toward a 50-million-ounce silver-equivalent goal within 10 years rests on drilling, this year's mill expansions (Santa Elena from 3,200 to 3,500 tons per day; Los Gatos from 3,500 to 4,000), and M&A - and management rules out buying gold or copper assets to grow.

Silver's price surge has not created new mines: new projects need roughly 18 years from discovery to production, so supply cannot respond quickly. First Majestic's unchanged production generated $40 million in quarterly free cash flow at $32 silver and roughly $220-250 million a year later. Two Santa Elena discoveries hold over 90 million silver-equivalent ounces (all metals converted to silver ounces), with permits arriving 12-18 months early. Exploration beats acquisition: Santa Elena discovery ounces cost about $0.32 each, far below what developers charge for ounces in the ground. A $1.2 billion cash position funds 300,000-plus metres of drilling, mill expansions and the Jerritt Canyon restart — growth without acquisitions.

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile

Investor TV
about 2 months ago

Aya's Zgounder mine is running as a cash machine: Q2 revenue up 151% YoY, operating cash flow up 522%, with payback on $140M capex inside five months. Boumadiene is targeting 37M ounces of silver a year at an AISC (all-in sustaining cost) under $15, lifting Aya to roughly 43M ounces by mid-2029. Q3 and Q4 historically deliver about 60% of annual silver production at the Moroccan operations because winter weather slows Q1 and Q2. A 400,000-ton ore stockpile gives the mill roughly two quarters of feed if mining halts, materially de-risking any short-term pit disruption. At a roughly $4B market cap, even conservative silver prices imply material upside as Boumadiene approaches commissioning.

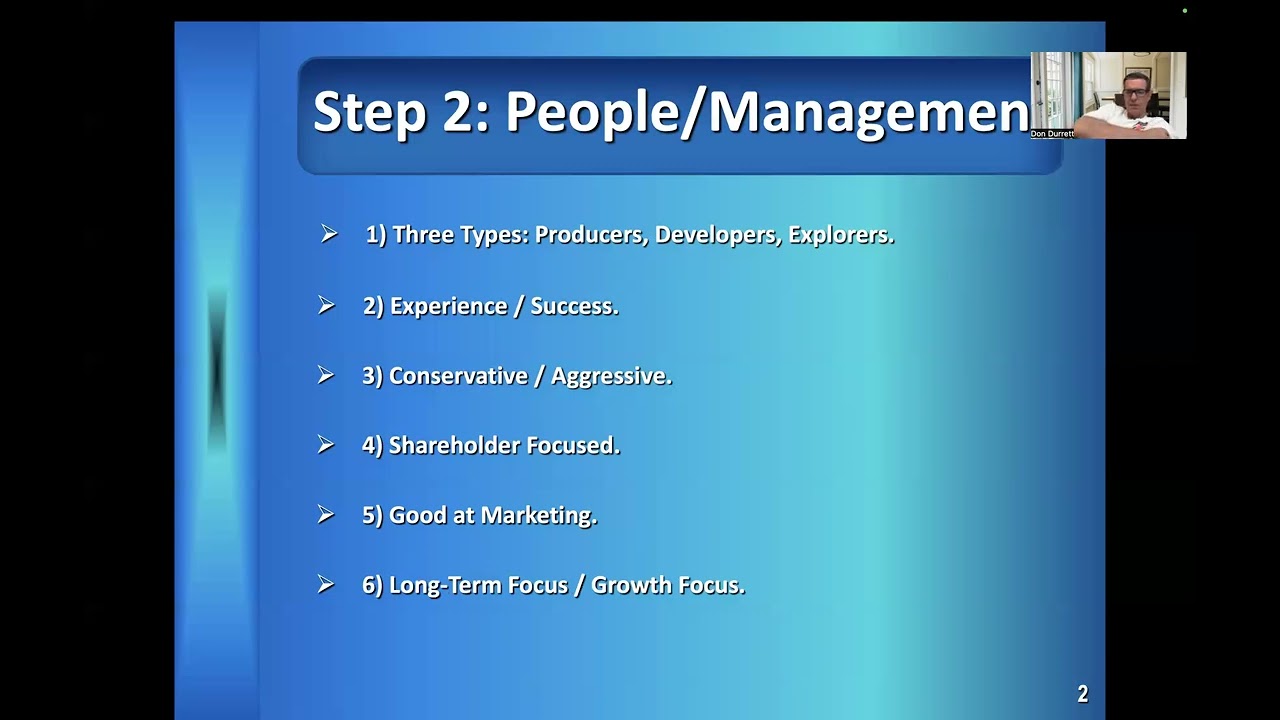
Masterclass: Investing in Gold/Silver Mining Stocks (Part 4)

Masterclass: Investing in Gold/Silver Mining Stocks (Part 4)

Don Durrett
about 2 months ago

Key Highlights

brief
  • In the speaker's producer tier ranking, First Majestic is placed one level below the elite producers he identifies (with Newmont at the top).

The author's 10-step checklist turns mining stock analysis into a discipline: size the deposit first, end with a numeric rating. Prefer gold deposits above 1.5 million ounces with grades of at least 1 g/t (open pit) or 5 g/t (underground) and recovery above 80%. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) should run about one-third of gold's spot price, with a 10% annual inflation assumption. Tight share structures (under ~150 million shares), conventional debt, and half-warrant financings protect per-share value; full warrants, heavy dilution, and reverse splits are red flags. Estimate a miner's future market cap using free cash flow times a 5-20x multiple, then divide by today's market cap for a clean growth-rate view.

Lab Report | Aug 20 Daily Market Overview & Deep Dive on Athena, Mackay, Orogen, Sirios

Lab Report | Aug 20 Daily Market Overview & Deep Dive on Athena, Mackay, Orogen, Sirios

CEO.CA
about 2 months ago 53:30

Key Highlights

brief
  • First Majestic owns the Hermano mine in New Mexico, which the host calls one of its best-performing mines and which generates a significant cash-flowing royalty for Orogen Royalties.
  • Beyond that royalty link, the host's read-across is the gold and silver breakout he describes in the market overview rather than any company-specific call on First Majestic.

Athena Gold's new Red Lake hit of 23.85 g/t (grams per tonne) over 5 metres, near surface, is the standout result. The host reads Sirios' 2.4 g/t over 48.5 metres at Cheech as high-grade shoots being tested beneath the open pit. Mackay Gold & Silver adds a core rig to test the historic Sutro tunnel intersection on the Comstock, Nevada, inside a 20,000-metre program. Orogen Royalties adds a 2% net smelter royalty on the Haldane silver project, and the host prefers its geologist-led model. With bond yields at multi-year highs and debt near $40 trillion, the host says all roads lead to gold, now above its 200-day average.

Lab Report | Aug 13 Daily Market Overview & Deep Dive on AMEX, Pan American, Arizona, WRLG

Lab Report | Aug 13 Daily Market Overview & Deep Dive on AMEX, Pan American, Arizona, WRLG

CEO.CA
2 months ago 49:23

Key Highlights

brief
  • He groups First Majestic with Pan American Silver, Agnico Eagle and Newmont as majors he believes are still priced closer to development-stage valuations on his Lassonde curve, even though they are established operators.
  • He cites First Majestic as the precedent behind his interest in Arizona Gold & Silver: drilling down to the boiling zone there is what created one of its best-producing mines.

Laboucan argues algorithmic trading keys off the day's headline narrative, not longer-term reality, which creates an opening for investors who look past daily swings. Turning a discovery into a mine takes 20 to 30 years, so gold, silver and copper supply cannot respond quickly to rising prices. Free cash flow - the cash that actually reaches the bank - is Laboucan's preferred measure, ahead of accounting earnings, at producers large and small. Mapping each name on the Lassonde Curve, he finds all four priced earlier than their actual development stage, a gap he frames as the opportunity. His gold case leans on debt stress: the yen carry trade - cheap Japanese borrowing funding US debt - keeps needing intervention that never lasts.

SILVER To 'Super Surge' After Debt-Based COLLAPSE - 'We're In the Red Zone': Francis Hunt

SILVER To 'Super Surge' After Debt-Based COLLAPSE - 'We're In the Red Zone': Francis Hunt

Commodity Culture
2 months ago

Key Highlights

brief
  • The guest notes First Majestic 'has always pursued ounces in the ground aggressively,' naming it among the silver miners he would rather own via stock certificates than via an ETF.

Hunt argues a bond market failure since 2020 puts the dollar on a debt collapse path, with silver potentially surging to $1,000-plus. He expects a near-term disinflationary sell-off in metals before a 'super surge' once bond contagion forces the Fed's hand. Falling wedge breakouts in gold, silver, and mining ETFs (GDX, SILJ, Hecla) all flag the same bullish continuation pattern. Extreme-strike call-option volume reflects call-writing and position management rather than insider conviction of imminent moves. Physical coins and bars held in your hand are the only true hedge when counterparty risk spikes in paper-metal claims.

Power Metallic Mines ($PNPN | $PNPNF): Maiden MRE & Exploration Updates

Power Metallic Mines ($PNPN | $PNPNF): Maiden MRE & Exploration Updates

Investor TV
2 months ago

Key Highlights

brief
  • Terry Lynch recommends First Majestic as a senior silver producer he would buy for a conservative investor.
  • Paired with Pan American Silver in his list of cheap senior silver names as a reasonable way to play the metals.

Power Metallic's maiden MRE for Lion and Nisk slipped to end of August; management argues it implies $1B+ NPV against a ~$200M market cap. Lion's roughly 5% Cu grade is an order of magnitude above the average operating copper mine, framing the project's unusual economics. Management plans to skip PFS and move Lion straight from maiden MRE to feasibility, with a PEA follow-up targeted by mid-November 2026. Muon-based geophysics is being deployed across the 5.5 km gap between Lion and Nisk to vector deeper drilling more cost-effectively.

Articles

The Gold Bull Makes the Case for First Majestic as a Leveraged Silver Play

The Gold Bull argues First Majestic Silver (AG) is a leveraged way to hold silver: 57% of revenue comes from silver, production jumped after the Gatos acquisition, and the balance sheet holds $435 million in cash. Rising 2026 cost guidance and slightly lower planned production are the main offsets, with fourth-quarter results due February 19.

8 months ago
First Majestic Silver Stock Pure Leverage to Silver Price
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord