Avino Silver & Gold Mines Ltd
ASMAvino Silver & Gold Mines Ltd., together with its subsidiaries, engages in the acquisition, exploration, and advancement of mineral properties in Canada. It primarily explores for silver, gold, and copper deposits. The company owns interests in 42 mineral claims and four leased mineral claims, including Avino mine area property comprising four exploration concessions covering 154.4 hectares, 24 exploitation concessions covering 1,284.7 hectares, and one leased exploitation concession covering 98.83 hectares; Gomez Palacio property consists of nine exploration concessions covering 2,549 hectares; Santiago Papasquiaro property comprises four exploration concessions covering 2,552.6 hectares and one exploitation concession covering 602.9 hectares; and Unification La Platosa properties, which include three leased concessions located in the state of Durango, Mexico. It also owns 100% interests in the Minto and Olympic-Kelvin properties located in British Columbia, Canada; and 14 quartz leases in Eagle property located in the Mayo Mining Division of Yukon, Canada. The company was incorporated in 1968 and is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Avino Silver & Gold Mines Ltd
Sector
Precious Metal
Founded
April 16, 1996
Employees
239
Reporting Currency
USD
Contact Phone
604-682-3701
Website
www.avino.comHeadquarters Address
570 Granville Street , Vancouver , BC V6C 3P1 , CA
Identifiers
ISIN
CA0539061030Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

Beaver Creek 2026 - Best Stocks
Key Highlights
detailed- Durrett says the mill for La Preciosa will not be finished until 2030, yet expects the shares to react in the middle of 2028.
- He lists Avino as one of the names most exposed to a takeover, pointing to insider ownership below 20%.
- He calls the valuation ridiculously cheap, saying it trades at about $557 and setting his own target at roughly $175 to $200.
- Two big projects mean he thinks growth this decade could be substantial, though the build timeline is long.
Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.

The Silver Price Was Not The Problem | Quanajuato Silver Q2 Earnings 2026
Key Highlights
brief- Realized $68.90/oz silver in Q2, between AYA's $68.29 and Endeavour's $70.16 in the host's peer price ranking.
- Per the host's methodology note, Avino's $38.75 AISC spreads costs over equivalent ounces priced at a budget silver price of $45.30, a different denominator than Guanajuato uses.
Guanajuato Silver's Q2 was nominally profitable, but AISC (All-In Sustaining Cost, the full cost to produce an ounce) at $71.66 topped per-equivalent-ounce revenue of $70.62. Operating five Mexican mines, the company retired most of its Ocean Partners gold debt using $9.2M of cash this quarter. Bolañitos, the mine acquired in January, is the most expensive ounce in the portfolio at $90.11 AISC, while contract-mined Topia is cheapest at $45.19. At a 24% EBITDA margin (peer median 47%), the stock looks cheap on assets but expensive on earnings at 25x P/E versus 14x. Management expects costs to fall once Bolañitos integrates; the Q3 scorecard hinges on higher tons, AISC starting with a 5, and working capital direction.
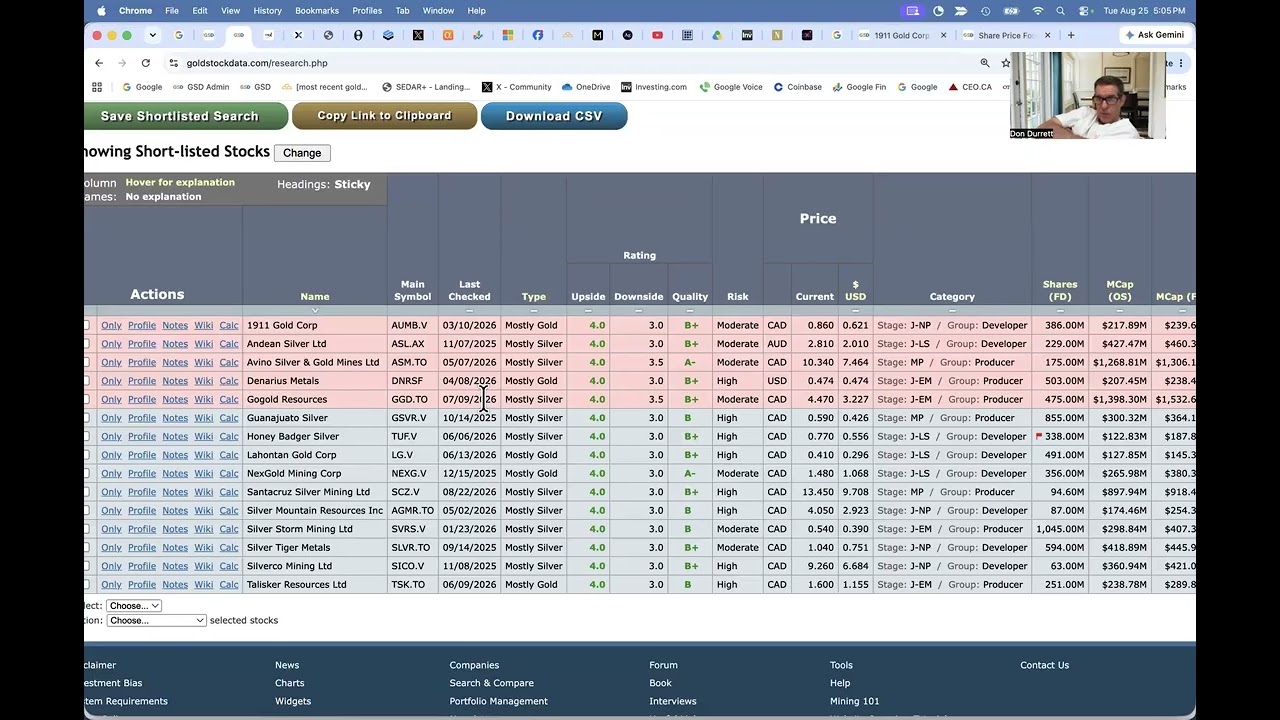
Gold/Silver Miners: Low Hanging Fruit (August 2026)
Key Highlights
detailed- The guest calls Avino an 'undervalued producer with organic production growth planned' — currently mining ~4M oz/yr off a 350M oz silver-equivalent resource, set to roughly double organically to ~8M oz over the next three years without dilution.
- He tags Avino as another likely hostile-takeover candidate because the valuation is 'very, very cheap' and insider ownership is low.
- He highlights a ~20x earnings multiple while production is actively ramping — growth, in his view, is not yet priced in.
Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.
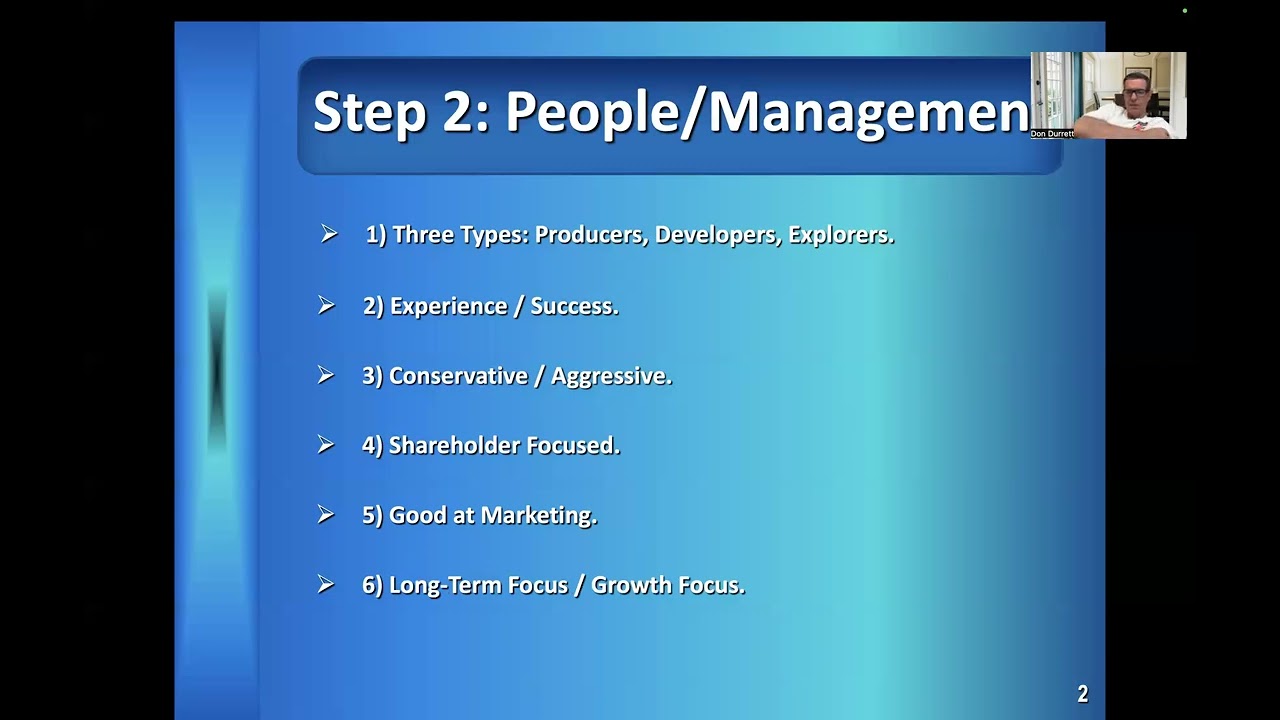
Masterclass: Investing in Gold/Silver Mining Stocks (Part 4)
Key Highlights
brief- The speaker uses Avino to illustrate resource-driven growth, noting the company is sitting on roughly 350 million ounces of silver while currently mining only around 3 million ounces a year — implying significant growth runway from its existing resource base.
The author's 10-step checklist turns mining stock analysis into a discipline: size the deposit first, end with a numeric rating. Prefer gold deposits above 1.5 million ounces with grades of at least 1 g/t (open pit) or 5 g/t (underground) and recovery above 80%. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) should run about one-third of gold's spot price, with a 10% annual inflation assumption. Tight share structures (under ~150 million shares), conventional debt, and half-warrant financings protect per-share value; full warrants, heavy dilution, and reverse splits are red flags. Estimate a miner's future market cap using free cash flow times a 5-20x multiple, then divide by today's market cap for a clean growth-rate view.

Deep Sea Minerals ($SEAS | $DSEAF): Potential NASDAQ Uplisting & Exploration Strategy
Key Highlights
brief- Don says Avino is mining a very large Mexican project underground but would prefer to pivot to open pit.
- He includes Avino in his Mexico permit-play group of names that stand to gain if open-pit permits in the country start moving.
Deep Sea Minerals received BCSC final receipt for its C$50 million shelf prospectus on July 28, advancing its planned NASDAQ uplisting. Polymetallic nodules lie loose on the seafloor; explorers map them with AUV and ROV video and sample with box cores — no drilling or blasting. The guest argues no commercial-scale nodule production exists yet, so proving harvesting machines run reliably is the industry's central risk, not discovery. Deep-sea licenses span several regulators (NOAA, BOEM, Cook Islands, ISA); the CEO says spreading applications across them mitigates jurisdiction risk. The hosts argue permit-ready Mexico silver developers such as GoGold and Silver Tiger trade depressed and could rerate as construction nears.

50 buy-the-dip stocks (July 17, 2026)
Key Highlights
detailed- Avino is expected to grow organically to about a million ounces a year for the rest of the decade, and he says he loves the organic growth.
- He expects no dilution will be required to fund that growth.
- Capex is very low, which he pairs with the story itself as the reason he likes the name.
He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.
Dave Erfle- Precious Metals Rebound: Key Technical Levels, Fed Speculation, Mining Sector Valuations
Key Highlights
brief- The host says Avino received the very first permit amendment in Mexico under the current administration, ahead of the other amended permits he lists.
Gold miners' bullish percentage index hit zero, a washout not seen since 2015, while producers earn record margins near $2,300 an ounce. Island reversals lifted GDX above 85 and GDXJ above 110; both levels now define the sector's short-term risk. The Fed faces 4.2% inflation and cannot absorb higher debt service, boxing itself in on either rate path. Global miners trade near five times EBITDA — a cash-earnings multiple — versus seven-plus in 2023, historically cheap. Junior developers hold funding into 2027 without near-term dilution as Mexico's concession-first regime speeds permits.

Gold/Silver Miner Buy The Dip List (June 2026)
Key Highlights
brief- Durrett says it is unusual for an established producer like Avino to carry what he frames as 25-bagger upside, and ties that to his $200 per ounce silver assumption.
- He says the math works if Avino grows output to about 8 million ounces a year while keeping its cost base under control, and that cost control is the crux of the number.
Gold and silver broke below their 200-day moving averages, and the host calls the 25% to 47% drop a buyable correction in a bull market. His trigger is the gold-to-S&P 500 ratio — gold's price divided by the index — near 0.6 today; 0.8–0.9 signals gold outperforming stocks. The watchlist spans producers, developers and explorers, with price assumptions of $7,000 gold and roughly $175 to $190 silver. Producers adding ounces rank above one-off development stories, since incremental production flows straight to free cash flow and lifts valuations quickly. He expects another, deeper dip before year-end tied to an S&P selloff, so he is assembling names to buy at lower prices.

Larry Lepard: Silver Miners Easily Double as Monetary Debasement Drives Commodity Supercycle
Lepard argues that unavoidable monetary debasement will drive a commodity supercycle, pushing gold toward $10,000/oz and significantly boosting silver miners. The guest targets emerging producers as the "sweet spot" for investment, balancing the high upside of developers with the lower risk of established mines. Lepard advocates taking profits during major rallies to manage the inherent volatility of junior mining equities, citing his own experience with Avino Silver.
Don Durrett and John Feneck Interview Scorpio Gold ($SGN | $SRCRF) CEO on 50,000 m Drill Program
Key Highlights
brief- John Feneck says he bought Avino at 53 cents US about a year ago on Don Durrett's recommendation and watched it run to roughly $10 over the following 12-18 months.
Scorpio Gold is fully funded for a 50,000 m Nevada drill program, targeting growth from 740,000 oz toward 2 million oz this year. The CEO frames an eventual sale to a mid-tier as the goal, but says the company is not locked into any path. Grade is the differentiator: holding roughly 1.26 g/t against a 0.6 g/t Nevada open-pit average supports premium margins and strategic value. Durrett argues gold's pullback is a warning that the S&P is overextended, so he would buy junior dips rather than chase. The hosts frame junior mining returns as asymmetric: size positions small, buy capitulation, and only risk what you can afford to lose.
Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario
Key Highlights
brief- Don Durrett names Avino among the undervalued silver producers he considers best set up as of the interview, with five-bagger-plus potential in his view.
Mayfair Gold is permitting a 4,800 tonne-per-day starter pit at Fenn-Gib provincially, cutting years off the federal route to first production. Projects under 5,000 tonnes per day permit provincially in Ontario, avoiding a federal review where no new (greenfield) mine has won approval since 2019. Management guides to a sub-$1,200 AISC (All-In Sustaining Cost — the full cost to produce an ounce) and first gold in 2030. Staying small preserves optionality: regional high-grade and underground tonnes can sweeten mill feed (raise average grade) without expanding throughput or new federal permits. Don Durrett favors undervalued, leveraged silver producers while John Fenwick argues war headlines, not fundamentals, gate gold's next move.

Americas Gold and Silver ($USA | $USAS): Silver and Antimony Opportunity in Idaho
Key Highlights
brief- Don Durrett names Avino, alongside Americas Gold and Silver and Endeavour Silver, as one of the few growing silver producers that excites him, in a sector where the top five have no growth.
- In his closing recap he counts Avino among the growth names he expects to be the market's big winners, where he anticipates 3-5 baggers on growing producers.
CEO Paul Andre Huet says the turnaround is on track: silver output stepped up 50% and targets a 3.6 million ounce run rate by year end. Huet reports Galena's measured and indicated resource — the higher-confidence categories — rose 19%, with grades up 21%, past 200 million silver ounces. Huet describes a US Antimony joint venture that turns previously penalized antimony into revenue, with an Idaho plant backed by price protection. Don Durrett frames gold and the S&P 500 as a 'final battle' gold will win, urging investors to stay invested and buy dips. With about $130 million US in cash and no planned equity raise, management says drilling at Galena, Crescent, and Cosala will be funded from operations.

Newsletter Favorites Upside (using New GSD Defaults)
Key Highlights
brief- The host finds it unbelievable that Avino prints as a 20-bagger on steady, all-organic growth yet nobody wants to buy it.
- He attributes the lack of interest to nobody believing in $200 silver.
Raising default price assumptions to $7,000 gold and $200 silver reflects conviction that current metal prices undershoot the macro setup. Screening 90 favorite miners at those prices prints 20-plus-bagger upside for many, but most need three-to-four-year mine builds first. Near-term producers like Guanajuato Silver need no new growth, so they offer immediate leverage if silver reaches $200. A gold-silver ratio squeeze toward 2.5-3% underpins the $175-200 silver target alongside $7,000 gold within 24-36 months. Timeline to getting paid is the key filter: the longer a mine build, the longer investors must wait for the printed upside.

David Wolfin of Avino Silver & Gold Mines talks to Chen Lin | Metals Investor Forum | February 2026
Avino Silver & Gold Mines CEO David Wolfin discusses company operations and strategy at the Metals Investor Forum in Toronto. Avino is focused on sustainable silver and gold production while expanding resources across its district-scale land package in Durango, Mexico. The Metals Investor Forum provides investors direct access to vetted junior mining companies with excellent management and promising properties.

David Wolfin of Avino Silver & Gold Mines Ltd. at Metals Investor Forum in Toronto | February 2026
David Wolfin, President and CEO of Avino Silver & Gold Mines, presents at the Metals Investor Forum in Toronto. The forum features vetted junior mining companies with excellent management, strong financials, and promising properties. Investors gain direct access to management teams, allowing them to ask critical questions and assess leadership quality.

Avino Silver and Gold Mines– Q4 2025 Operations Review, 2026 Exploration Plan At Avino & La Preciosa
Avino Silver reports Q4 2025 operational results with focus on production metrics and cost performance at their Mexican silver-gold operations. 2026 exploration program outlined for both Avino mine and La Preciosa project, targeting resource expansion and new discoveries. Management discusses strategic priorities including potential production growth and timeline for La Preciosa development.

Mike Larson & Dave Erfle - Volatility Ahead, Metals Roaring, Why Silver Stocks Lag the Spike
Key Highlights
brief- Mike Larson identifies Avino Silver & Gold Mines as the standout performer in his 2025 Money Show top picks report, up 567% as he tracked it through the year.
Silver's 2026 breakout above a 45-year resistance at $50 is structurally different from the 1980 Hunt Brothers corner and 2011's CME-driven speculative bubble — it is anchored by a sixth straight supply deficit and critical industrial demand. Despite silver tripling in twelve months, silver equities have not delivered their historical 2–2.5× leverage to the metal, with stocks priced in silver at levels last seen during the 2020 pandemic crash. Gold futures hit record highs above $4,600 as central bank buying, sovereign de-dollarization, and concerns about Fed independence create what the guest calls a "Category 5 hurricane" for precious metals. Dave Erfle is rotating gains from advanced developers into drill-stage juniors under $200M market caps, where raising capital and diluting less aggressively is now possible for the first time in years. The TSX Venture's breakout above 1,000 — a twelve-year neckline — carries a measured target near the 2011 high, roughly 150% higher from current levels if monthly closes confirm.
Peter Boockvar & Brien Lundin - Geopolitics to Metals Mania: Venezuela, Critical Minerals, PMs
Key Highlights
brief- Brien describes Avino (referenced as "Vino") as one of the "autopilot" silver plays expected to be a great performer in the silver bull market
Silver's surge is structurally different — industry is being forced to bid against investors for physical supply for the first time ever. A contrarian oil thesis: WTI at $58 sits in a down cycle, US shale is maturing, and speculative positioning is at 15-year lows. Critical-minerals designation shifts demand dynamics by implying scarcity and encouraging inventory hoarding beyond ordinary consumption. The AI trade is differentiating — investors now punish excessive capex, and the rate of change in spend and returns is slowing. Big copper discoveries have collapsed from hundreds in the 1980s–90s to about six in the past five years, blunting any supply response.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.