
Aya Gold & Silver Inc logo

Aya Gold & Silver Inc

AYA

Aya Gold & Silver Inc., together with its subsidiaries, engages in the acquisition, exploration, evaluation, and development of precious metal properties in Morocco. The company primarily explores for gold, silver, zinc, lead, tungsten, molybdenum, uranium, and copper deposits. Its flagship project is the Zgounder property located approximately 265 kms east of Agadir in the Proterozoic Siroua Massif of the Anti-Atlas Range, Morocco. Aya Gold & Silver Inc. was incorporated in 2007 and is based in Montreal, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Aya Gold & Silver Inc

Sector

Precious Metal

Founded

July 24, 2008

Employees

405

Reporting Currency

CAD

Contact Phone

647 919 2227

Headquarters Address

1320 Boulevard Graham , Montreal , QC H3P 3C8 , CA

Identifiers

Commodity Portfolio

AG Silver Primary

Stock Exchanges

AYA TSX • CAD
AYA:TSE
AYASF OTC • USD
AYASF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Upside Gold ($UG | $UGODF): 3.31 Moz Historical Gold Resource and 5,180 Metres Drilled in BC

Upside Gold ($UG | $UGODF): 3.31 Moz Historical Gold Resource and 5,180 Metres Drilled in BC

Investor TV
8 days ago 24:42

Key Highlights

brief
  • Sophy Cesar says she worked at Aya Gold & Silver back when it was still Maya Gold and Silver, describing it as a very large silver-producing company with a mine in Morocco.

Upside Gold's Kena project in southern British Columbia holds a historical 3.31 million ounce gold resource, with an updated 43-101 estimate expected in Q1 2027. The 2026 drill program reached 5,180 metres, beating its 4,000 metre plan and finishing ahead of schedule, with assay results still pending. Management is targeting 4 to 5 million ounces by adding recent drilling, the Kena copper gold zone, and previously excluded copper and silver values. The host sees the company valued near $850 an ounce in the ground against a $34 million market cap, framing shares as cheap optionality. Flow-through dollars (tax-incentive financing for Canadian exploration) make up $3.7 million of the June raise, already covering the 2027 drill program.

Snail-Mail Stock Promos, Short Sellers & Visible Gold: Junior Mining Insights with Powers & Leni

Snail-Mail Stock Promos, Short Sellers & Visible Gold: Junior Mining Insights with Powers & Leni

MiningStockEducation.com
8 days ago 58:55

Key Highlights

brief
  • Bill Powers notes Aya Gold & Silver was the target of a short report that the company had to address.
  • Bill relays the CEO's claim that the group behind the allegations shelters itself offshore, making legal action very difficult even if there were cause, so the shorts could drive the stock down and profit.

Subdued retail attendance at fall forums contrasts with rising institutional interest; fund inflows look likely to favor isolated stories, not the sector broadly. Twelve-page glossy mailers promoting nickel and tungsten juniors signal heavier promotion; weighing cash, runway, and project substance beats believing the narrative. Specialization pays: pick one commodity or deposit type, learn its signals deeply, and branch out one step at a time instead of staying high-level. Visible gold claims before assays are marketing, not evidence. One company retracted its visible-gold release, so wait for verified results before acting. Site visits and concentration define the co-host's process: see infrastructure firsthand, hold 10 to 15 names, and plan the exit in advance.

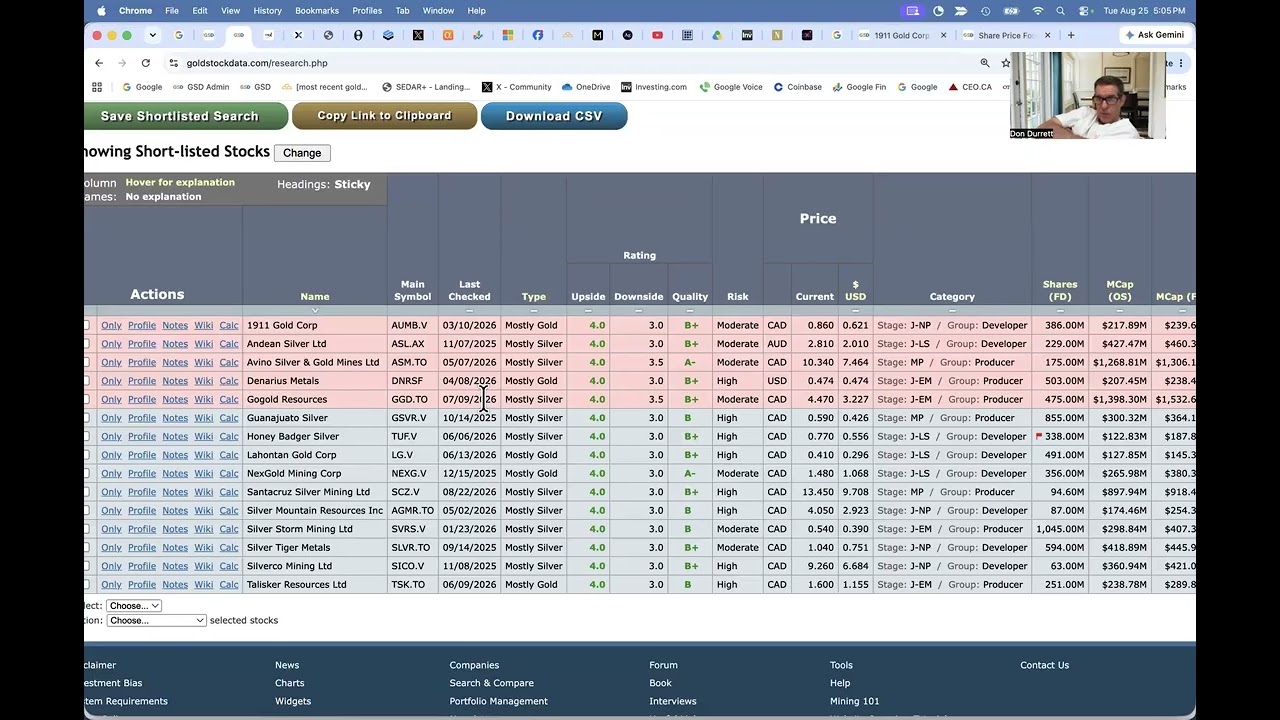
Beaver Creek 2026 - Best Stocks

Beaver Creek 2026 - Best Stocks

Don Durrett
10 days ago 38:24

Key Highlights

detailed
  • Durrett calls Boumadine a thing of beauty and says the risk-reward on Aya is excellent.
  • He keeps the grade at a 3 because the outcome of building Boumadine is uncertain, and says the rating moves to a 3-5 once that mine is built.
  • He says Aya could be a 3-5 right now and describes it as borderline at that level.
  • He frames the company as a growing producer with a growth story.

Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.

Nick Hodge – Beaver Creek Recap, Key Newsflow In Portfolio Stocks, & Outlook On Gold, Silver, Copper

Nick Hodge – Beaver Creek Recap, Key Newsflow In Portfolio Stocks, & Outlook On Gold, Silver, Copper

The KE Report
13 days ago 23:59

Key Highlights

brief
  • Hodge says he wanted to buy Aya Gold & Silver after meeting the company at the Rule Symposium, but the stock got away from him on the chart and has not pulled back commensurately with other names.

Junior resource companies are spinning out unloved assets into new vehicles, a track record Nick Hodge credits with unlocking shareholder value where portfolios stagnate. This year's Beaver Creek precious metals summit was the busiest yet, with institutional money out in force and companies focused on execution over bull-market debates. The guest argues copper is the strongest major metal, supported by data-center buildout, mine supply disruptions, and the absence of US import tariffs. Gold must hold $4,000, in Hodge's view, as a rising dollar and multi-decade bond yields oppose it, setting up a buying opportunity. Silver looks weaker than gold and could retest $55; Hodge is hunting a mid-tier silver producer but wants a better entry before buying.

Aya Gold & Silver ($AYA): From Updated PEA to Development at Boumadine

Aya Gold & Silver ($AYA): From Updated PEA to Development at Boumadine

Investor TV
21 days ago 49:35

Key Highlights

detailed
  • The updated PEA for Boumadine shows an after-tax NPV of $3.5B at base case ($5.5B at spot), an IRR of 93% (128% at spot), payback of 8 months, and a capex-efficiency ratio of 7.6, which the speakers describe as extremely rare for the sector.
  • Management says the decision to build Boumadine is already made: the project is fully permitted, water and power are secured, the site sits at 1,000m elevation in Morocco, and the $463M capex is self-funded with $200M cash and $250-300M of available EBRD debt plus $150-300M of potential offtake prepayments.
  • Boumadine is framed as an early-stage asset that has only seen 5.4km of a 6km structure drilled (320,000m) and remains open to the north and south; the company plans 400,000m of additional drilling in the next 18 months with 20 drills currently turning.
  • Planned production is 350,000 oz gold-equivalent per year at the 8,000 tpd PEA rate, scaling to roughly 425,000 oz at the 10,000 tpd rate being designed into the feasibility study, with cash costs around $998/oz and AISC of $1,100/oz for the first five years.
  • The share structure is unusually tight at 144M shares outstanding, with management, the board and four founding family offices controlling about 46% and BlackRock, VanEck and Vanguard holding roughly 25% combined.

Aya's Boumadine PEA shows a $3.5B base-case NPV and 93% IRR on $463M of capex, with no equity dilution needed. An AISC of $1,100/oz in years one to five keeps Boumadine robust even if silver stays in the low $60s. Full permits plus $200M cash and up to $300M in off-take prepayments leave the project fully funded through construction. The guest calls Boumadine the best gold-silver project globally; the analyst host sees 10x potential as Wall Street ignores the build.

Gold & Silver Just Added $2 Billion to This Project | Aya Gold - Bourmadine PEA

Gold & Silver Just Added $2 Billion to This Project | Aya Gold - Bourmadine PEA

The Deep Dive
26 days ago 13:36

Key Highlights

detailed
  • The host reports the revised Boumadine PEA, published the week before the September 17, 2026 as-of date, more than doubles after-tax NPV to $3.5 billion USD from $1.5 billion, but most of the extra $2 billion comes from higher price assumptions of $3,500 gold and $50 silver versus $2,800 and $30 previously; at near-constant prices he pegs the real improvement closer to 23%.
  • Aya has already made the investment decision to build Boumadine before the feasibility study is done: CEO Benoit LaSalle says construction starts in Q4 2026, and the company is pushing for first production around mid-2029, ahead of the PEA's own Q4 2030 timeline.
  • Where the study clearly improved is on payables, which rise from 73% to 83% of metal shipped on average (gold from 69% to 82%), and on near-flat initial capital of $463 million, up 4% including $99 million of contingency, which the host says Aya plans to fund from cash flow, external debt and $183 million in cash, with the EBRD considering a $200 million loan.
  • On the rock the host argues the project got worse: indicated tons rose 66% at a 19% lower grade, inferred ounces rose just 1% on a 35% grade cut, the strip ratio worsened from 20.9 to 22.6, all-in sustaining costs rose 27% to $1,300 per ounce, and roughly four of every five tons in the mine plan are inferred material that the feasibility study due in the second half of 2027 cannot rely on.
  • On valuation, Aya closed at about 1.1 times NPV (roughly $3.9 billion USD enterprise value); the host calculates that once the Zagounder mine is credited at the 8-10x EBITDA multiple LaSalle himself uses, investors effectively pay around 0.34-0.53 times for Boumadine, a developer-like price rather than a builder's multiple.

Aya's updated Boumadine PEA doubles the after-tax NPV to US$3.5 billion, but higher gold and silver price assumptions do most of the lifting. AISC (all-in sustaining cost — what it really costs to produce an ounce) rose 27% to $1,300 as grades fell and strip ratios worsened. Roughly four of every five tonnes in the mine plan remain inferred; PEAs allow that, but a prefeasibility study cannot, so conversion risk stays. Aya is starting construction in Q4 2026, more than a year before the feasibility study normally used to justify that decision. Aya trades near 1.1 times NPV, above developer peers like AbraSilver and Vizsla, and its Zagounder mine means Boumadine is not free.

Why Gold Producers Are Still Undervalued: Greg Orrell on This Cycle’s Missing Retail Money

Why Gold Producers Are Still Undervalued: Greg Orrell on This Cycle’s Missing Retail Money

MiningStockEducation.com
about 1 month ago 28:24

Key Highlights

brief
  • The fund bought Aya Gold & Silver at a couple of dollars and it later traded at $40, with the fund harvesting multiples of its cost this year
  • Orrell uses Aya as a concrete example of trimming positions when valuations become extreme

Gold decoupled from real yields after 2022 Russia sanctions triggered central bank reserve diversification — a structural shift Orrell expects to persist. Producers still trade below historical NAV multiples because investors haven't priced in $4,500-$5,500 gold; Orrell expects multiples to expand as skepticism fades. OCM Gold Fund holds ~20-23% senior producers, 10-13% exploration/development, ~5% royalties, 5-7% silver — trims losers and lets winners compound. Agnico Eagle leads capital allocation discipline; B2Gold holds junior stakes like Snowline Gold but hasn't executed buyouts, a stark contrast to past reckless exploration. With cash below 1% while retail liquidates, Orrell sees further upside — counter-cyclical positioning in a cycle still missing wider participation.

The Silver Price Was Not The Problem | Quanajuato Silver Q2 Earnings 2026

The Silver Price Was Not The Problem | Quanajuato Silver Q2 Earnings 2026

The Deep Dive
about 1 month ago 13:42

Guanajuato Silver's Q2 was nominally profitable, but AISC (All-In Sustaining Cost, the full cost to produce an ounce) at $71.66 topped per-equivalent-ounce revenue of $70.62. Operating five Mexican mines, the company retired most of its Ocean Partners gold debt using $9.2M of cash this quarter. Bolañitos, the mine acquired in January, is the most expensive ounce in the portfolio at $90.11 AISC, while contract-mined Topia is cheapest at $45.19. At a 24% EBITDA margin (peer median 47%), the stock looks cheap on assets but expensive on earnings at 25x P/E versus 14x. Management expects costs to fall once Bolañitos integrates; the Q3 scorecard hinges on higher tons, AISC starting with a 5, and working capital direction.

Gold/Silver Miners: Low Hanging Fruit (August 2026)

Gold/Silver Miners: Low Hanging Fruit (August 2026)

Don Durrett
about 2 months ago

Key Highlights

detailed
  • The guest says Aya nearly made his low-hanging-fruit list — at a ~$4B market cap he is targeting $75–90B at $200 silver, framing it as a 10-bagger thesis driven by the Boumadene project.
  • He left Aya off the formal list mainly because production doesn't start until 2029.
  • He expects Aya to 'start ripping higher' within a year of the recording.

Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile

Investor TV
about 2 months ago

Key Highlights

detailed
  • Benoit La Salle reports Q2 year-over-year revenue up 151%, net income up 300%, and operating cash flow up 522%, attributing part of the move to the Q2 NASDAQ listing that doubled trading volume and forced out prior OTC short sellers.
  • La Salle describes Zgounder as a de-risked cash machine producing 6 million ounces of silver a year at a Q2 cash cost of $17, with an 11-year mine life and $119 million of operating cash flow in the first half against $140 million of capex (about a 5-month payback).
  • The CEO highlights a 400,000-tonne silver ore stockpile that could keep the plant fed for roughly two quarters if mining stopped, and a positive resource update adding 20 million ounces versus the prior estimate.
  • La Salle outlines Boumazin as roughly six times Zgounder production, targeting 43 million oz/yr (silver equivalent) by mid-2029 with an AISC around $15 and a $450 million capex spread over two years; the project is fully permitted with water, power and land secured.
  • The CEO describes the balance sheet as pristine — 144 million shares outstanding with about 46 million tightly held by board and family offices, $70 million of net debt and $183 million of free cash — and confirms the board plans a structured share buyback once Boumazin financing is finalized.

Aya's Zgounder mine is running as a cash machine: Q2 revenue up 151% YoY, operating cash flow up 522%, with payback on $140M capex inside five months. Boumadiene is targeting 37M ounces of silver a year at an AISC (all-in sustaining cost) under $15, lifting Aya to roughly 43M ounces by mid-2029. Q3 and Q4 historically deliver about 60% of annual silver production at the Moroccan operations because winter weather slows Q1 and Q2. A 400,000-ton ore stockpile gives the mill roughly two quarters of feed if mining halts, materially de-risking any short-term pit disruption. At a roughly $4B market cap, even conservative silver prices imply material upside as Boumadiene approaches commissioning.

Live Q&A with Rick Rule and Steve Barton

Live Q&A with Rick Rule and Steve Barton

Rule Investment Media
2 months ago

Key Highlights

detailed
  • The speaker has AYA at a 5 rating — high — but says the stock has run up so much it is starting to price in 18 months of successful execution that has not yet occurred.
  • He praises management as superb implementers with high asset quality and credits a prior Rule Classroom interview with helping force a short-covering rally he describes as a religious experience for the shorts.
  • He is a self-described huge Benoit LaSalle fan, having invested with the CEO for nearly three decades, but calls the current valuation expensive.
  • He argues that if the team executes against the feasibility study the way they historically did at AYA and before that at SEMAFO, the current market cap will prove more than justified.

Rising price is not the same as rising value; resource cycles typically run years, so time preference matters as much as entry timing. Focused copper producers like Southern Copper deliver more leverage than diversified majors such as BHP or Rio Tinto treat copper as a side business. Resource category confidence (measured and indicated versus inferred) and on-site infrastructure matter as much as headline ounces when comparing deposits. Royalty and streaming businesses reward patient capital over years; the next big deals will likely syndicate into bite-sized opportunities for tertiary players. Asymmetric exploration bets work only when the loss is affordable, with Rule framing NG Energy as a possible ten-bagger against a 30 to 50% loss.

50 buy-the-dip stocks (July 17, 2026)

50 buy-the-dip stocks (July 17, 2026)

Don Durrett
3 months ago

Key Highlights

detailed
  • Aya Gold & Silver's Boomerang project is due to go into construction next year, with production in 2029 or possibly late 2028.
  • He argues the Zgander mine alone roughly equals the company's current market cap, so Boomerang comes free — and Boomerang is larger.
  • For that reason he does not expect the company to be sold, and he calls Boomerang one of the better projects going.

He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.

The Best Silver Bull Market in 30 Years? |  Bradley Langille - GoGold

The Best Silver Bull Market in 30 Years? | Bradley Langille - GoGold

The Deep Dive
3 months ago

Key Highlights

brief
  • Langille holds Aya up as the scale benchmark, saying GoGold at over 9 million silver-equivalent ounces would be a significant mid-tier in the silver space, 'more like an AYA silver.'

GoGold's newly received Los Ricos South permit unlocks construction in Mexico, with detailed engineering already 80% complete and dirt moving within a month. GoGold brings $284 million in cash and no debt to the build, with 12-year-old Parral tailings generating about $60 million free cash flow yearly. Los Ricos South targets 7.3 million silver-equivalent ounces yearly at $12 AISC (All-In Sustaining Cost — true cost per ounce), toward 15 to 17 million. The Eagle Zone's first 18 months could generate close to half a billion dollars of after-tax free cash flow, nearly repaying the project's capex twice. Langille credits 30 years of Mexican relationships and community benefit for permitting wins, and calls this the best silver bull market of his career.

I Asked The Greatest Junior Mining Investors What They Are Buying Right Now | Rule Symposium

I Asked The Greatest Junior Mining Investors What They Are Buying Right Now | Rule Symposium

Palisades Gold Radio
3 months ago

Key Highlights

brief
  • Prins names Aya Gold and Silver as a pure-play silver miner and part of where she sees value, defining pure play as a miner very close to the silver itself that does not have to process other metals in its deposit.
  • Her case for the group rests on silver having been the most severely and most quickly depressed precious metal, hit by a very high volume of paper trading.

Gold and silver fell 30-50% from highs, and multiple guests frame the pullback as a buying window for quality developers, not a trend break. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) explains the margin math: $4,000 gold against a $2,000 AISC. One guest argues gold pays no dividend, so valuation must run against debt, money supply and GDP instead of cash flow. Royalty companies and prospect generators are presented as the safer way to play gold and silver than owning operators outright. Several guests expect a wave of mining M&A, because producers shed high-cost operations and hold cash without a growth pipeline.

Criag Hemke - Busy Week Ahead: Inflation Data, Fed Testimony

Criag Hemke - Busy Week Ahead: Inflation Data, Fed Testimony

The KE Report
3 months ago

Key Highlights

detailed
  • Craig Hemke says he raised a little cash on the Friday before the July 13, 2026 recording specifically to buy Aya Gold & Silver, describing it as essentially a silver producer despite the gold in its name.
  • Host Shad confirms the company is almost all silver, with what he calls one of the purest silver mines in Morocco.
  • Per the host, Aya is contemplating spinning out the gold asset it holds alongside its Moroccan silver mine.

Hemke argues record deficit spending and soaring interest costs mean the Fed cannot hike for long and will eventually cap yields. Real interest rates (returns after inflation) correlate most closely with gold, so this week's inflation data and Fed testimony could set the trend. Gold and silver sit above year-ago levels, yet miner shares have lagged badly, and Hemke sees fat margins the market ignores. Copper holds near all-time highs on long-term supply shortfalls, and rising copper tends to lift silver, which stays above breakout levels. Rather than time bottoms, Hemke stays fully invested in miners, saying the most uncomfortable moments are the best buying opportunities.

Dr. Nomi Prins: Silver Price 'Heavily Suppressed', Uranium Miners & Gold

Dr. Nomi Prins: Silver Price 'Heavily Suppressed', Uranium Miners & Gold

Palisades Gold Radio
3 months ago

Key Highlights

detailed
  • The guest names Aya Gold & Silver as a prime example of a valuable pure-play silver miner whose deposits are close to the metal and need no processing of other metals.
  • She says Aya's mine in Morocco receives orders instantaneously for physical silver from the Middle East, Asia, China and India, with no disruption in demand for real ounces.
  • In the same passage she cites costs of getting ounces out of the ground at roughly $20, arguing producers keep making money with silver around $60 as of the interview and would earn far more at higher prices.

Silver's paper price trades far below physical reality: a sixth straight supply-deficit year means mine output is bought immediately by industrial and solar demand. Uranium holds near $85 while utilities contract at $95-$100, so miners' share-price lag against a firming price is the opportunity. Major gold miners sit on large cash with costs near $1,800 against $4,100 gold, positioning them to acquire or fund junior developers. A 35-year survey cited by the guest finds gold beat cash roughly five-to-one after inflation, with strong juniors multiplying that edge. Oil has normalized into a $70-$80 band as depleted strategic reserves need replenishing, favoring Colombian producers whose heavy crude US refineries process.

Benoit La Salle, Pres. & CEO of Aya Gold & Silver Inc. | Rule Symposium 2026: Rick Rule interviews

Benoit La Salle, Pres. & CEO of Aya Gold & Silver Inc. | Rule Symposium 2026: Rick Rule interviews

Rule Investment Media
5 months ago

Key Highlights

detailed
  • The guest argues the second project, Boumadin, is the main source of upside: about $440 million of capital spending for roughly 400,000 ounces of gold equivalent a year over 11 years at an all-in sustaining cost near $900, on a structure he says is far larger than the 5 km drilled so far.
  • He says Boumadin would produce about 37 million ounces of silver a year against about 6 million ounces at the producing mine, roughly six times the output, with construction starting at the end of 2026 and first production targeted for 2029, and he counters the analyst view that buying Aya today means paying full price for Gunda and getting Boumadin free.
  • He describes Gunda, in production, as the largest silver mine in Africa and says Q1 2026 results published the week of the interview showed $17 million of free cash flow for the quarter, with $200-300 million expected for the full year.
  • He says the drilling budget is expanding: 200,000 metres on a $45 million budget in 2025, roughly 240,000 metres on $60 million this year, and another 240,000 metres in 2027, with more than 600 million ounces of silver equivalent found so far at a stated discovery cost of 10 cents an ounce, though he notes infill drilling this year will cost more than that.
  • He says there is no further dilution risk because the company does not need to raise money, has very little debt to be paid off this year and next, and holds cash and silver in the vault; he also says the stock fell from about $18 to $11 during a 2025 short-seller attack and was back near $29 on the night before the interview.

Aya Gold & Silver's Gunda mine, described as Africa's largest silver mine, generated $17 million of free cash flow in Q1 alone. The Boumadin project needs $440 million for 400,000 gold-equivalent ounces over 11 years at an AISC (All-In Sustaining Cost) of $900 per ounce. Management targets $200-300 million of free cash flow this year, funding growth from cash with no planned equity raise and little debt. A 2025 short-seller report alleging weak reserves and misused funds cut the shares from $18 to $11; third-party audits refuted it. Management points to Morocco's pro-mining rules and an underexplored 1,600-kilometer belt it is drilling with $60 million this year.

Don Durrett & John Feneck Explore First Tellurium’s ($FTEL | $FSTTF) PyroDelta Energy Stake

Don Durrett & John Feneck Explore First Tellurium’s ($FTEL | $FSTTF) PyroDelta Energy Stake

Investor TV
5 months ago

Key Highlights

brief
  • Don lists Aya Gold & Silver among his nine 'Mormon' silver producers that he expects to be highly profitable at $200 silver and urges viewers to buy now.

PyroDelta's thermoelectric generators (solid-state devices that turn waste heat into electricity) need only a 20°C differential and run 24/7. First Tellurium (CSE: FTEL), which management calls the world's only tellurium-focused company, owns 83% of PyroDelta plus a high-grade British Columbia project. Acceptance into DARPA's Lift Challenge (Dayton, Ohio, August 2) brings prize potential and introductions to defense primes and drone-delivery buyers. Durrett argues small silver producers gain huge margin above $200 silver, though he cautions developers take years and often disappoint before paying off. Co-hosts note 131 million shares out with roughly 35% in friendly hands, giving the 11-cent junior room to move on DARPA news.

Interview with Upside Gold CEO (April 29, 2026)

Interview with Upside Gold CEO (April 29, 2026)

Don Durrett
6 months ago

Key Highlights

brief
  • The guest lists Aya Gold & Silver among the junior mining companies she worked at earlier in her career, across her 15-plus years on TSX, Venture and CSE listed names.

Upside Gold is drilling toward a 2021 resource of 3.31 million gold ounces in southern British Columbia, targeting 30-40% growth. Growth rests on three pillars: historical drilling, 10,000 meters of new drilling, and adding never-credited copper and silver. Low-grade bulk mineralization near surface, with roughly 95% gold recovery in testing, underpins the open-pit optionality case. The host frames the shares at about $20 per ounce in the ground, far below recent Canadian and Guyana exploration deal prices. Management argues a refreshed resource estimate by early 2027 could revalue the project toward development-stage multiples.

Newsletter Favorites Sorted by Quality (April 2026)

Newsletter Favorites Sorted by Quality (April 2026)

Don Durrett
6 months ago

Key Highlights

detailed
  • Don Durrett describes Aya as a Northern Africa and Morocco story.
  • He says it is very close to being a 4-3-5 A.
  • The gap is Boumadden, where he says the outcome is still an unknown.
  • He could probably make it a 3.5 on the strength of Morocco alone, but not until Boumadden is built.

Durrett ranks the 89 gold and silver stocks he owns on upside, downside risk, and company quality — a system investors can copy. His 'three-five' score marks a likely five-bagger — a stock he expects could multiply roughly five times from current levels. Only four holdings earn an A, reserved for low costs, clean balance sheets, and consistent execution — Australian mid-tier producers dominate the top. Country risk caps otherwise strong names: West African, Mexican, and Colombian exposure keeps ratings below top marks. He flags likely takeover targets among focused developers and producers still generating free cash flow.

Articles

Aya Gold & Silver's revised Boumadine PEA doubles NPV to $3.5 billion — but the rock got thinner

The Deep Dive reviews Aya Gold & Silver's revised Boumadine PEA: after-tax NPV doubled to $3.5 billion on higher metal prices, better payables, and three extra mine years, while initial capital rose just 4% to $463 million. But grades fell, the strip ratio worsened, AISC rose 27% to $1,300/oz, and about four of five planned mill tonnes remain inferred.

26 days ago
Gold & Silver Just Added $2 Billion to This Project | Aya Gold - Bourmadine PEA
Read article

Aya Gold & Silver: Zgounder Cash Engine Funds a 43 Moz Boumadine Build

Aya CEO Benoit La Salle outlines Q2 results (revenue +151%, operating cash flow +522% YoY) from Zgounder, a $17/oz cash-cost mine, with a 400,000-ton stockpile de-risking near-term production. The bigger story is Boumadine: a permitted, 8,000-tonne-per-day build targeting ~43 Moz/year by mid-2029, AISC near $15, and an updated PEA due in weeks.

about 2 months ago
Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord