
Cabral Gold Inc logo

Cabral Gold Inc

CBR

Cabral Gold Inc. operates as a mineral exploration and development company with primary focus on gold properties in Brazil. Its flagship project is the Cuiú Cuiú gold project located in the state of Para in northern Brazil. Cabral Gold Inc. was formerly known as San Angelo Oil Limited. Cabral Gold Inc. is based in Vancouver, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Cabral Gold Inc

Sector

Precious Metal

Founded

March 12, 2015

Employees

23

Reporting Currency

CAD

Contact Phone

604-676-5663

Headquarters Address

409 Granville Street , Vancouver , BC V6C 1T2 , CA

Identifiers

Commodity Portfolio

AU Gold Primary

Stock Exchanges

CBR TSXV • CAD
CBR:CVE
CBGZF OTC • USD
CBGZF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Beaver Creek 2026 - Best Stocks

Beaver Creek 2026 - Best Stocks

Don Durrett
10 days ago 38:24

Key Highlights

brief
  • Durrett puts Cabral at about a 5 million ounce project, likes where it is headed, and says it probably belongs on his top 25 and should re-rate quickly.
  • He says his takeover concern eased - he no longer thinks the company is for sale because management realises what it has.

Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.

Live Interview with Brien Lundin

Live Interview with Brien Lundin

Rule Investment Media
11 days ago 59:26

Key Highlights

detailed
  • Lundin personally owns Cabral Gold and says 'I love Cabral right now,' with no plans to sell any shares anytime soon, even though the stock is no longer in his recommended portfolio because it 'got away' from his earlier call.
  • He says Cabral has just started producing and selling gold at Cuiu Cuiu, with the first gold sale worth about $10 million in revenue.
  • He argues Alan Carter's low-capex early-production strategy fits the new market: at today's gold prices the company may never need to dilute shareholders again to fund what he calls an extraordinary exploration project.

Brien Lundin says gold and long bond yields are sending one signal — currencies will be depreciated to manage unpayable government debt. He favors producers: majors offer 4-5x potential with dividends and net cash, and eventually they must turn to M&A to refill depleted pipelines. Better-funded juniors now drill seriously, but developers advancing projects alone may cap takeover premiums near 20% instead of the 200% of past cycles. Strategic-metals politics invite government and generalist capital that ignores project economics, reviving deposits the industry had written off as uneconomic. Lundin stays bullish on K2 Gold's Mojave drilling, Prospector Metals around $0.80-$0.90, and Cabral's low-capex early production funding exploration without dilution.

Versamet Royalties–Record Q2 Earnings Metrics, Royalty & Streaming Partner Updates, Growth Into 2027

Versamet Royalties–Record Q2 Earnings Metrics, Royalty & Streaming Partner Updates, Growth Into 2027

The KE Report
about 2 months ago

Key Highlights

detailed
  • Cabral Gold's QUQU oxide project in Brazil is described by the guest as 'way ahead of schedule,' with first gold expected in September.
  • This contribution was not in prior 2026 guidance - it comes on at relatively small scale later in 2026, but the cash flow is expected to fund further drilling.
  • The longer-term prize, in the guest's view, is the sulfide mineralization underneath the oxide cap, which Cabral is advancing with production cash flow.

Versamet posted record Q2 with revenue up 392% and EBITDA up 747% year-over-year, underscoring the cash-flow strength of its royalty model. The 3.52% Eskay Creek gold stream, due mid-2027, should lift attributable production to roughly 35,000 GEOs (gold equivalent ounces) versus 20–23K in 2026. Versamet's operator partners — Equinox, West African, Endeavour Silver — deliver asymmetric upside, since mine-life gains and grade improvements flow straight to its bottom line. Rosh Pinah's RP 2.0 expansion is ~95% complete and is on track to nearly double the mine's throughput to 1.4 million tons annually. Surprise catalysts — Cabral Gold's Cuiú Cuiú pour in September 2026 and Southern Copper's El Palar build starting 2027 — add ounces plus copper exposure.

Erik Wetterling – Value Proposition In Nevada King Gold, Cabral Gold, and Rua Gold

Erik Wetterling – Value Proposition In Nevada King Gold, Cabral Gold, and Rua Gold

The KE Report
3 months ago

Key Highlights

detailed
  • The Phase 1 gold-in-oxide heap leach at Cuiu Cuiu is nearly built, with commissioning started in the week before the interview (mid-July 2026), and Erik expects it to make Cabral self-funding so exploration can proceed without repeated dilution.
  • Erik backs the saprolite-first plan: mining near-surface, easy-to-process ore for early revenue that can fund exploration and the larger project without constant capital raises.
  • The district case rests on immense historic placer workings — Erik calls it possibly the second-largest placer gold rush in Brazil ever — plus strong bedrock drill holes, signaling substantial primary gold sources across the large land package.
  • Erik sees G Mining next door as a potential natural exit if Cabral proves up something large, and expects the story to do pretty well at $4,000 gold.

Nevada King trades at a steep discount to its strategic investor's entry while drilling 40,000 metres across a brownfield Nevada oxide gold project. Cabral Gold's Phase 1 heap leach (recovering gold from loose near-surface rock) is roughly 85% built and commissioning in Brazil. Rua Gold pairs a fast-tracked starter underground project in New Zealand with antimony (a critical mineral) and district-scale exploration upside. The guest argues cheapness is the best offense and defense, making proven ounces plus exploration optionality an asymmetrical setup. Early revenue from a small starter operation can fund exploration and shield juniors from sector sentiment and dilution.

Optionality Update - April 2026

Optionality Update - April 2026

Don Durrett
6 months ago

Key Highlights

detailed
  • Durrett believes G Mining Ventures has Cabral Gold in its sights because it is right next door to their operations, though a takeover probably would not come until 2028.
  • He says the stock has started to rip at a $244 million market cap and could easily grow to 4 million ounces, while he models it at 2 million.
  • He suggests Cabral may get a break in the near term because G Mining just spent its money on G2 Goldfields.

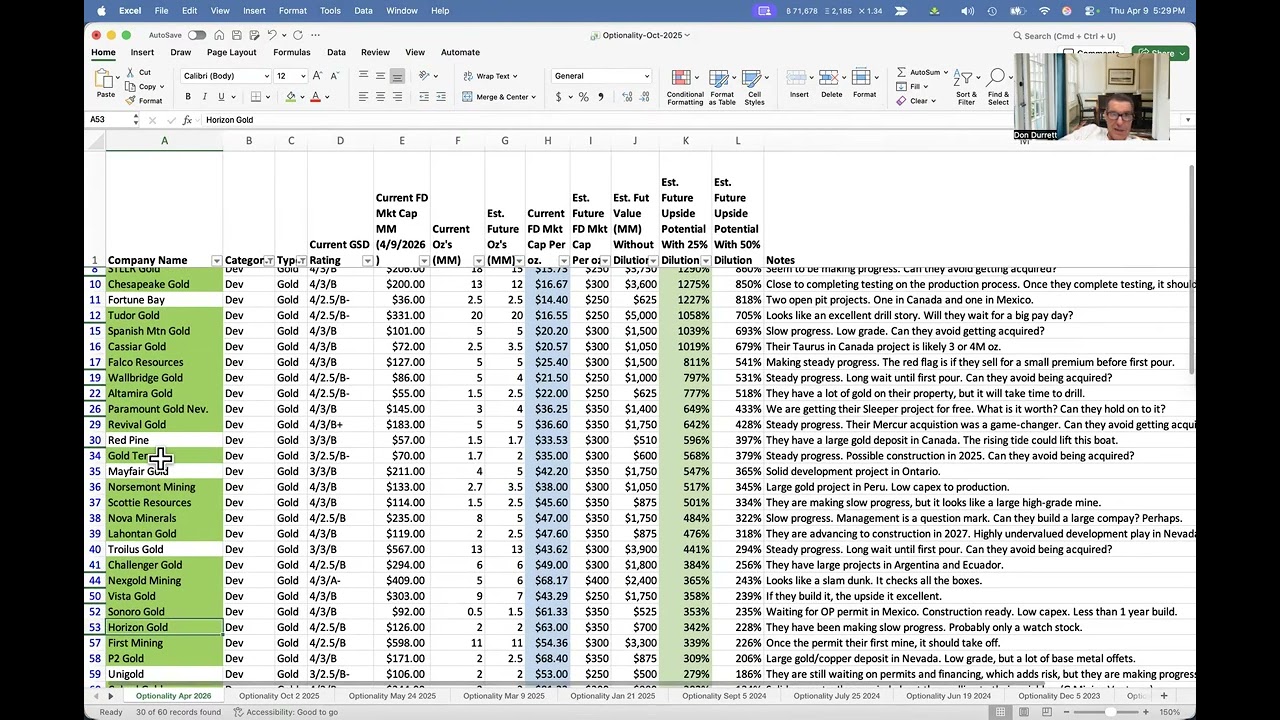
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Newsletter Favorites Upside (using New GSD Defaults)

Newsletter Favorites Upside (using New GSD Defaults)

Don Durrett
7 months ago

Key Highlights

brief
  • The host says he thinks G Mining Ventures is going to acquire Cabral.

Raising default price assumptions to $7,000 gold and $200 silver reflects conviction that current metal prices undershoot the macro setup. Screening 90 favorite miners at those prices prints 20-plus-bagger upside for many, but most need three-to-four-year mine builds first. Near-term producers like Guanajuato Silver need no new growth, so they offer immediate leverage if silver reaches $200. A gold-silver ratio squeeze toward 2.5-3% underpins the $175-200 silver target alongside $7,000 gold within 24-36 months. Timeline to getting paid is the key filter: the longer a mine build, the longer investors must wait for the printed upside.

Erik Wetterling – PDAC Review – Value Proposition In Cabral Gold, Sonoro Gold, and Cerro de Pasco

Erik Wetterling – PDAC Review – Value Proposition In Cabral Gold, Sonoro Gold, and Cerro de Pasco

The KE Report
7 months ago

Erik Wetterling shares PDAC insights on Cabral Gold, Sonoro Gold, and Cerro de Pasco, highlighting their current value propositions for investors. Discussion focuses on investment merits and catalysts for each company following the PDAC conference. Analysis provides retail investors with actionable research on emerging gold and silver opportunities.

Newsletter Favorites Overview (Feb 2026)

Newsletter Favorites Overview (Feb 2026)

Don Durrett
8 months ago

Key Highlights

brief
  • Don expects Cabral Gold to get acquired by its neighboring shark company, which he says just buys and builds, so he wants to own the acquirer.

Durrett argues there is limited time left to buy gold and silver producers while they are still cheap, expecting one more significant dip. His Newsletter Favorites list leans on quality Canadian and Australian mid-tier producers, which he expects to re-rate as the bull market warms up. Companies whose second and third projects get no market value offer free upside — you pay for the first asset and get the rest for nothing. Cheap forward free-cash-flow multiples persist in West Africa and among silver producers, where weak sentiment discounts heavy leverage to metal prices. Australian producers like Ramelius reaching major-sized valuations is, in his view, the first sign the junior gold bull market is broadening.

Articles

Cabral Gold Nears First Production at Cuiú Cuiú: A Self-Funding Exploration Thesis

On the KE Report, Erik Wetterling argues Cabral Gold is executing its base case: the Phase 1 gold-in-oxide heap leach at Cuiú Cuiú is about 85% built and in commissioning, and its revenue could self-fund exploration across a Brazilian district with extensive placer workings — with G Mining operating next door as a possible natural exit.

3 months ago
Erik Wetterling – Value Proposition In Nevada King Gold, Cabral Gold, and Rua Gold
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord