Chesapeake Gold Corp
CKGChesapeake Gold Corp., a mineral exploration and development company, focuses on the discovery, acquisition, and development of gold and silver deposits in North and Central America. The company also explores for zinc ores. The company's flagship project is the Metates project, which comprises 12 mineral concessions totaling 4,261 hectares located in Durango State, Mexico. It also holds interest in Talapoosa gold project in the state of Nevada. The company was formerly known as Chesapeake Gold Ltd. and changed its name to Chesapeake Gold Corp. in May 2002. Chesapeake Gold Corp. was founded in 1993 and is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Chesapeake Gold Corp
Sector
Precious Metal
Founded
October 9, 2003
Reporting Currency
CAD
Contact Phone
778-731-1362
Website
www.chesapeakegold.comHeadquarters Address
1166 Alberni Street , Vancouver , BC V6E 3Z3 , CA
Identifiers
ISIN
CA1651841027Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

Beaver Creek 2026 - Best Stocks
Key Highlights
detailed- Durrett argues a roughly $177 million valuation against about 15 to 18 million ounces of gold is around $10 an ounce on the ground, and calls the valuation ridiculous for what the company has.
- A dispute with the Mexican government over the San Vicente lease, which sits in the middle of the deposit, has delayed the project by about a year.
- He expects to win the lease back but notes the company will not start a PFS until it has it.
- He says the sulfide heap leach technology works and could be worth roughly $10 million a year in licensing, and expects another company to use it next year.
- He expects the project to be built and describes it as another one too big to fail.
Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.
Goldgroup Mining ($GORO): Building a Multi-Asset Gold and Silver Producer
Goldgroup's $15M acquisition of Gold Resource Corp added the Don David silver-gold mine, transforming a single-asset producer into a multi-asset Mexican platform. A 26,000-meter drill program at San Francisco targets resource expansion; restart capital is roughly $25M with a target output of about 50,000 ounces a year. Goldgroup is advancing the Back 40 copper-gold project in Michigan but cites an 18-month permitting risk in a Democratic-leaning state. Eric Sprott, Cala, and other insiders control roughly 70% of the float, sharply limiting the risk of a lowball takeover. Forced Russell 2000 selling after a 15-day inclusion window wiped out half the market cap — a mechanical dip that disciplined investors exploited.

Deep Sea Minerals ($SEAS | $DSEAF): Potential NASDAQ Uplisting & Exploration Strategy
Key Highlights
brief- Don says Chesapeake has not yet submitted its permit for a big open-pit project, expects approval to follow Discovery's, and argues the stock is valued as if it will never be permitted.
- The host likes Chesapeake and says the CEO is hoped to appear on the show later in the year.
Deep Sea Minerals received BCSC final receipt for its C$50 million shelf prospectus on July 28, advancing its planned NASDAQ uplisting. Polymetallic nodules lie loose on the seafloor; explorers map them with AUV and ROV video and sample with box cores — no drilling or blasting. The guest argues no commercial-scale nodule production exists yet, so proving harvesting machines run reliably is the industry's central risk, not discovery. Deep-sea licenses span several regulators (NOAA, BOEM, Cook Islands, ISA); the CEO says spreading applications across them mitigates jurisdiction risk. The hosts argue permit-ready Mexico silver developers such as GoGold and Silver Tiger trade depressed and could rerate as construction nears.

50 buy-the-dip stocks (July 17, 2026)
Key Highlights
detailed- A PFS is due this year for Chesapeake Gold and he thinks the metallurgy is fine despite concerns some people raise.
- He values the roughly $190M market cap against about 15M oz of gold plus significant silver, which he sees as producing enormous free cash flow.
- The catch is the wait: open-pit greenfield projects have not yet been permitted, though he argues the first one approved would be a major catalyst for Chesapeake.
He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.

Triumph Gold ($TIG) Advances Projects in Yukon and Utah | Interview with Don Durrett and John Feneck
Key Highlights
detailed- The analyst has Chesapeake as the third of three Mexican greenfield open pits he is watching, and argues that a permit going through for Discovery or Sonora would open the door for Chesapeake too.
- The host notes Chesapeake has not yet submitted its application — 'they're down the road' — making it the furthest behind of the group.
- The analyst counts Chesapeake among the best gold and silver projects in Mexico, which he calls the world's top-three silver producer and too important to ignore despite country risk.
Triumph Gold's CEO argues the company stayed deliberately idle through the bear market and is now spending. A $5.4 million raise funds three drill rigs, a 45-person camp, and re-logging all 150,000 metres of historic core. The CEO says old drill logs plus 30,000 soil samples are being reassessed with AI to define a major discovery target. A Utah silver project carries a 12-tonne bulk sample grading 45 ounces per tonne, with drilling targeted for late summer. The analysts frame both assets as undervalued versus what they estimate the ground is worth per ounce.

Gold/Silver Miner Buy The Dip List (June 2026)
Key Highlights
detailed- Durrett says Chesapeake is a development project in Mexico that will take a while to deliver.
- He notes no greenfield project has been permitted yet, and says Chesapeake is waiting on Discovery Silver's permit as the signal to proceed, with Sonoro a further catalyst.
- He frames the build as at least two years and possibly three.
- He calls it a long-distance play but with a lot of leverage.
Gold and silver broke below their 200-day moving averages, and the host calls the 25% to 47% drop a buyable correction in a bull market. His trigger is the gold-to-S&P 500 ratio — gold's price divided by the index — near 0.6 today; 0.8–0.9 signals gold outperforming stocks. The watchlist spans producers, developers and explorers, with price assumptions of $7,000 gold and roughly $175 to $190 silver. Producers adding ounces rank above one-off development stories, since incremental production flows straight to free cash flow and lifts valuations quickly. He expects another, deeper dip before year-end tied to an S&P selloff, so he is assembling names to buy at lower prices.

Newsletter Favorites Sorted by Quality (April 2026)
Key Highlights
brief- Don Durrett says Chesapeake Gold has to get its permit before it can move up to B+.
Durrett ranks the 89 gold and silver stocks he owns on upside, downside risk, and company quality — a system investors can copy. His 'three-five' score marks a likely five-bagger — a stock he expects could multiply roughly five times from current levels. Only four holdings earn an A, reserved for low costs, clean balance sheets, and consistent execution — Australian mid-tier producers dominate the top. Country risk caps otherwise strong names: West African, Mexican, and Colombian exposure keeps ratings below top marks. He flags likely takeover targets among focused developers and producers still generating free cash flow.
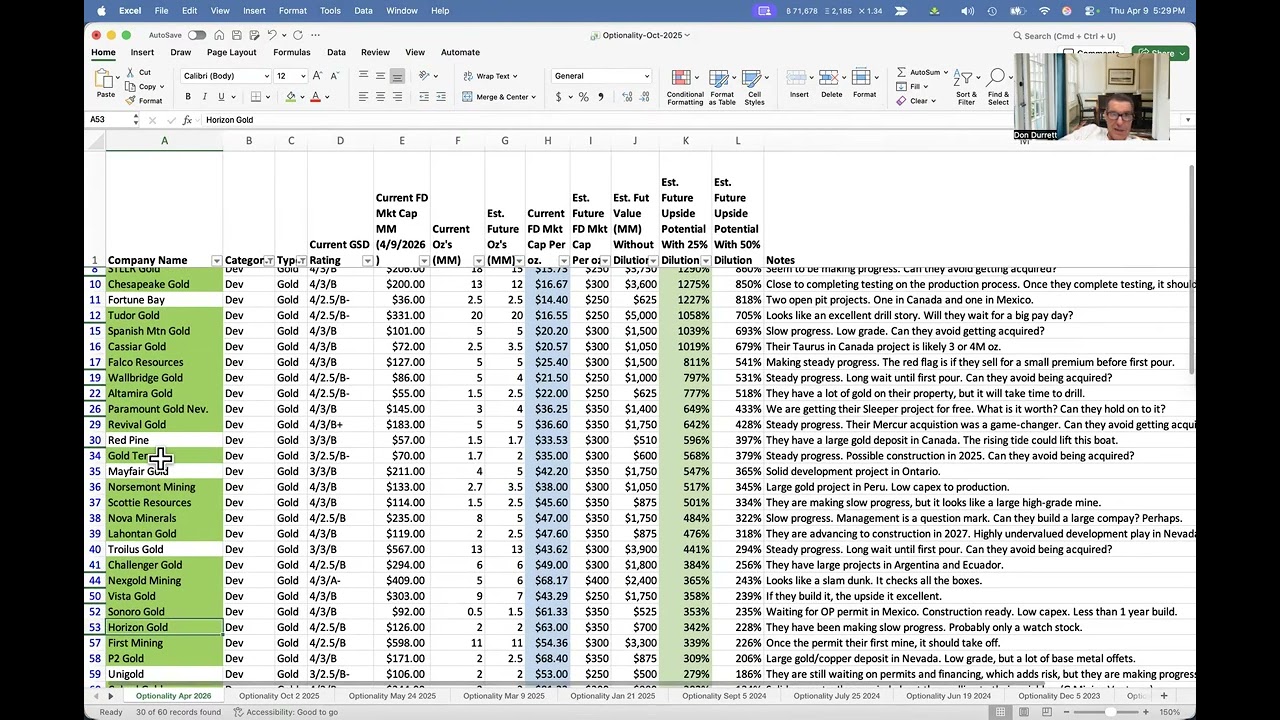
Optionality Update - April 2026
Key Highlights
brief- Durrett expects Chesapeake Gold to receive its permit, possibly this year, which he says would completely change the stock's dynamic and make it very much in demand.
- He describes it as two open-pit projects that are very cheap.
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Newsletter Favorites Upside (using New GSD Defaults)
Key Highlights
detailed- The host says Chesapeake Gold prints as roughly a 50-bagger at $7,000 gold, with a $173 million market cap he considers ridiculous.
- He explains the discount: a legal issue on one of its leases is putting downward pressure on the stock, and it still needs its permit for a big open pit followed by an approximately three-year build.
- He notes the project models 200,000 ounces of gold and 2.5 million ounces of silver, generating about $1.4 billion of free cash flow at $7,000 gold.
- He frames it as a long-term spec bet and says he would be very happy with a five-bagger since he is late in the cycle and would exit early rather than wait for the full move.
Raising default price assumptions to $7,000 gold and $200 silver reflects conviction that current metal prices undershoot the macro setup. Screening 90 favorite miners at those prices prints 20-plus-bagger upside for many, but most need three-to-four-year mine builds first. Near-term producers like Guanajuato Silver need no new growth, so they offer immediate leverage if silver reaches $200. A gold-silver ratio squeeze toward 2.5-3% underpins the $175-200 silver target alongside $7,000 gold within 24-36 months. Timeline to getting paid is the key filter: the longer a mine build, the longer investors must wait for the printed upside.

Newsletter Favorites Overview (Feb 2026)
Key Highlights
brief- Don is a big fan of Chesapeake Gold, which he expects to do a PFS this year, and he sees it getting closer to a B plus.
- He points to roughly 15 million ounces of gold plus a big chunk of silver getting no value at about $2 billion market cap, and says Chesapeake could be the next Highcroft - an overnight 10-bagger once it takes off.
Durrett argues there is limited time left to buy gold and silver producers while they are still cheap, expecting one more significant dip. His Newsletter Favorites list leans on quality Canadian and Australian mid-tier producers, which he expects to re-rate as the bull market warms up. Companies whose second and third projects get no market value offer free upside — you pay for the first asset and get the rest for nothing. Cheap forward free-cash-flow multiples persist in West Africa and among silver producers, where weak sentiment discounts heavy leverage to metal prices. Australian producers like Ramelius reaching major-sized valuations is, in his view, the first sign the junior gold bull market is broadening.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.