Fresnillo plc
FRESFresnillo Plc is the world's largest primary silver producer and Mexico's second-largest gold producer, boasting a diversified portfolio of long-life, low-cost assets. The company's primary operations include the Fresnillo and Saucito silver mines, and the Herradura and Noche Buena gold mines, all located in Mexico. With a strong track record of operational execution and a robust balance sheet characterized by a net cash position, Fresnillo stands as a pillar in the precious metals mining industry.
The company's investment thesis is anchored in its extensive mineral reserves and resources, underpinned by a commitment to continuous exploration and mine optimization. Fresnillo's strategy focuses on maintaining low-cost production, optimizing asset performance, and advancing its pipeline of development projects, notably the Juanicipio mine (operational and ramping up) and the San Julián project. This pipeline ensures long-term production stability and growth potential.
However, Fresnillo's operations are entirely concentrated in Mexico, a Tier 3 jurisdiction. While the company has historically navigated this environment successfully, it faces ongoing risks related to security, community relations, and potential shifts in mining regulations or taxation. The recent judicial reform in Mexico and proposed changes to mining laws require careful monitoring, although Fresnillo's strong local relationships and infrastructure provide a competitive moat.
Financially, Fresnillo is highly robust, generating substantial free cash flow at current metal prices. The company's strict capital allocation discipline, characterized by a progressive dividend policy and self-funded growth, aligns well with shareholder interests. Its valuation remains attractive relative to peers, trading at a reasonable EV per ounce and FCF multiple, making it a compelling, albeit jurisdictionally concentrated, investment in the precious metals sector.
Data Quality
Market Cap
$24.95B
Total valuation
Stock Price
$3,390
▲ 3.43% today
Free Cash Flow
N/A
Annual
Financial Position
$660.85M
Net cash positive
PEG Ratio
ⓘN/M
Not meaningful
Analysis
Score Interpretation
Hover any criterion below to reveal its full rationale, key metrics, strengths, concerns, and source documentation.
Criterion Detailed Analysis
Recommendation
Fresnillo Plc is a high-quality, major precious metals producer with world-class silver assets and a fortress balance sheet. The company's low-cost operations and strong free cash flow generation make it a resilient investment in the mining sector. However, its exclusive operations in Mexico (Tier 3 jurisdiction) introduce political and regulatory risks that weigh on its overall score. The stock is fairly valued at current levels, offering a balanced risk-reward profile for investors seeking liquid exposure to the silver and gold markets. Long-term growth is supported by a solid development pipeline and exploration upside, though geographic diversification remains a notable gap in the company's strategy.
Red Flags
| Criterion | Severity | Score | Description |
|---|---|---|---|
| jurisdiction | Medium | 5.00 | 100% of operations are located in Mexico (Tier 3 jurisdiction), exposing the company to political, regulatory, and security risks. |
| industry_partnerships | Low | 6.00 | Limited strategic partnerships beyond the Juanicipio JV, which may restrict opportunities for geographic diversification. |
Scenario Analysis
Bull Case
Bull case assumes silver prices exceed $35/oz and gold prices surpass $2800/oz, driven by strong industrial demand and macroeconomic uncertainty. Successful ramp-up of Juanicipio and favorable resolution of Mexican regulatory issues contribute to re-rating.
Base Case
Base case assumes silver prices remain stable around $30/oz and gold at $2650/oz. Production meets guidance, and the company continues to generate strong free cash flow, maintaining its dividend.
Bear Case
Bear case considers a decline in silver prices below $22/oz due to global economic slowdown, coupled with adverse regulatory actions in Mexico that increase operational costs or delay permits.
Audit Trail
| # | Source |
|---|---|
| 1 | Annual Report 2024: Financial statements, operational performance, reserve/resource estimates |
| 2 | NI 43-101 Technical Reports: Resource estimates for Fresnillo, Saucito, Herradura, and Juanicipio mines |
| 3 | Corporate Governance Report 2024: Executive compensation, insider ownership |
| 4 | Fraser Institute Annual Survey: Jurisdictional risk assessment for Mexico |
Financials
Core Metrics
Annual Production
N/A
Troy oz per year
Revenue
$4.63B
Latest reported
Net Income
$1.06B
Annual
Enterprise Value
$24.29B
Net debt: -$660.85M
Adj. EBITDA
$1.98B
EV/EBITDA 12.25x
Income & Cash Flow
Waterfall · Revenue to Free Cash Flow
Key P&L Ratios
N/A
Free Cash Flow Generated
Balance Sheet & Leverage
Capital Structure
- Equity $10.57B
- Long-Term Debt $0.00
- Short-Term Debt $0.00
- Cash & Equivalents $1.32B
Leverage & Coverage
-$660.85M
Net Debt (Strong)
Cash Uses & Returns
- Capital Expenditures $973.89M
- Dividends Paid $528.68M
- Share Buybacks $0.00
- Interest Expense $0.00
- Debt Repayment / Other $1.14B
Profitability & Returns
Returns
Margins
Liquidity & Coverage
Yield
Valuation
Valuation Multiples
Share Structure & Ownership
Share Structure
- Outstanding 738.00M 738.00M
- Options 5.00M 5.00M
- RSUs 7.00M 7.00M
- Warrants 0.00 0.00
Per-Share & Buyback Metrics
$0.00
Remaining Buyback Capacity
Health Indicators
Strength across all solvency and liquidity metrics
6.0% of 1.0x threshold
0.0% of 3.0x threshold
0.0% of 3.0x target
100.0% of 48 months target
10.7% of 15% threshold
Asset Pipeline
Jurisdiction Exposure
Geographic distribution of mining properties · Equal-weighted (no NPV data)
- Mexico100.0% · Tier 3 · 4 properties
Operating Mines
Distribution across development stages · Equal-weighted (no NPV data)
- Production (Steady-State)75.0% · 3 Assets
- Production (Ramp-Up)25.0% · 1 Asset
Cost Structure
All-in Sustaining Cost (AISC) breakdown • Peer-leading efficiency
$17/oz • 100%
Fresnillo Mine
Herradura Mine
Juanicipio Mine
Saucito Mine
Information
Key Information
Legal Entity
Fresnillo plc
Sector
Precious Metal
Founded
May 27, 2008
Employees
7,179
Reporting Currency
GBP
Contact Phone
52 55 5279 3000
Website
www.fresnilloplc.comHeadquarters Address
Calzada Legaria No. 549 , Mexico City , DF 11250 , MX
Identifiers
ISIN
GB00B2QPKJ12Commodity Portfolio
Liquidity
- Avg dollar volume (50d)
- —
- Last trade date
- Jul 30, 2026
- Days since last trade
- 74
- Last evaluated
- Oct 12, 2026 10:30 PM
Stock Exchanges
Organization
Management Team
Octavio Alvídrez
Chief Executive Officer
Specialization: Chief Executive Officer | Fresnillo plc | World's Largest Primary Silver Producer
Octavio Alvídrez serves as Chief Executive Officer of Fresnillo plc, the world's largest primary silver producer and Mexico's largest gold miner. Listed on the London Stock Exchange and constituent of the FTSE 100, Fresnillo operates a portfolio of world-class mining assets across Mexico. Alvídrez has led the company through periods of significant operational transition, navigating challenges from declining ore grades at legacy mines while advancing new development projects to sustain the company's position as the globe's preeminent silver producer. A mining engineer by training, Alvídrez brings deep operational expertise to the executive suite. Prior to ascending to the CEO role at Fresnillo, he served as General Manager of the Madero Mine for Peñoles, Fresnillo's parent company and one of Mexico's most storied industrial conglomerates. This hands-on operational background in underground mining operations has informed his approach to managing Fresnillo's complex portfolio of underground and open-pit operations, including the flagship Fresnillo and Saucito silver mines, the Herradura gold mine, and the San Julián and Juanicipio operations. Beyond his corporate responsibilities, Alvídrez has played a prominent role in the broader mining industry. He served as President of The Silver Institute, the leading global industry association for silver, and continues as a Board member. He has also been actively involved with the Lowell Institute for Mineral Resources at the University of Arizona, one of the premier mining research institutions in the United States, and is a member of the Mexican Mining Chamber. These positions reflect his standing within the international mining community and his commitment to industry advancement. For mining investors, Alvídrez's commentary carries significant weight due to Fresnillo's outsized influence on global primary silver supply. His insights on Mexican mining policy, silver and gold market fundamentals, operational challenges in mature mining districts, and capital allocation strategies at one of the industry's most closely watched producers make him a key voice in the precious metals sector. Under his leadership, Fresnillo has navigated issues common to many senior precious metals producers—grade decline, cost inflation, community relations, and the imperative of replacing depleted reserves—making his strategic decisions a bellwether for the broader industry.
Insider Ownership
15.00%
Mario Arreguín
Chief Financial Officer
Specialization: Chief Financial Officer | Fresnillo plc | Precious Metals Mining Executive
Mario Arreguín serves as Chief Financial Officer of Fresnillo plc, the world's largest primary silver producer and one of Mexico's most significant gold miners. Listed on the London Stock Exchange (LSE:FRES) and headquartered in Mexico City, Fresnillo operates a portfolio of major precious metals assets across Mexico. Arreguín's role places him at the financial helm of a company that is a bellwether for the global silver market and an important player in Latin American gold production. Prior to joining Fresnillo, Arreguín held the position of Chief Financial Officer at Peñoles, the Mexican mining and metals conglomerate that is Fresnillo's parent company and one of the largest non-ferrous metals producers in Mexico. His career also includes experience in financial services at Valores Finamex, providing him with a well-rounded perspective spanning corporate finance, capital markets, and mining operations. Arreguín holds an MBA from The University of Chicago Booth School of Business, complementing his strong technical and financial foundation. He has also been associated with Stanford University in an educational capacity. His academic credentials from two of America's premier institutions underscore the analytical rigor he brings to capital allocation decisions in the mining sector. As CFO, Arreguín has been a regular participant in Fresnillo's earnings calls and investor presentations, communicating financial results, cost management strategies, and capital expenditure plans to the global investment community. For mining investors, his commentary on Fresnillo's all-in sustaining costs, production guidance, and expansion timelines at assets like the Juanicipio project provides direct insight into the operational economics of large-scale precious metals mining in Mexico.
Insider Ownership
5.00%
Industry Partnerships
MAG Silver
Joint Venture
Project: Juanicipio
Ownership: 56.0%
Source: Annual Report, JV Agreements
Partner Market Cap
$1.50B
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos
A $40M Company Created $2B in Mining Value | John-Mark Staude - Riverside Resources
Key Highlights
brief- He points to a Sonora royalty project that Fresnillo is involved with, where Riverside holds a 2% net smelter return royalty over some of the claims in the key starter-pit area rather than the entire project.
- He cites it as the first of the royalties he expects could bring cash flow to Riverside.
Riverside Resources has spun out seven companies worth over $2 billion combined while its own market cap sits near $40 million. Its next spinout, Ravenna, would hold five Mexican properties in Sonora while Riverside keeps royalties across all of them. The guest says gold is the priority because it needs less development capital and permits faster than large copper projects. A net smelter royalty is a cut of a mine's revenue; Riverside holds 2% stakes at Tahuehueto and Sugarloaf Peak. Five new projects in southern British Columbia, spanning rare earths, gold and copper, extend the project-generation pipeline.

This Copper Giant Holds 1.2 Billion Silver Ounces | Jordan Pandoff
Nova Sül would rank Lumina as the world's third-largest silver producer at full output — backed by 15Mt copper and 1.2Boz silver in inventory. Lumina could fund the $6.4B Nova Sül build with EU debt and a silver stream — IPO was 4x oversubscribed at $300M. Poland's capped 2012 mineral extraction tax gives Nova Sül asymmetric leverage — at spot copper and silver, the post-tax NPV triples versus the PEA. Twin identical $3B shaft complexes let Lumina scale by reusing one design across the continuous Kupferschiefer copper-silver seam. Sulmierzyce (Silmir Zisha) is a potential spinout with 6Mt copper and 300Moz silver — ongoing drilling is expected to grow that resource materially.

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile
Key Highlights
brief- Don Durrett argues that, as of August 2026, Fresnillo is the only major silver producer still ahead of Aya on a gold- or silver-equivalent production basis.
Aya's Zgounder mine is running as a cash machine: Q2 revenue up 151% YoY, operating cash flow up 522%, with payback on $140M capex inside five months. Boumadiene is targeting 37M ounces of silver a year at an AISC (all-in sustaining cost) under $15, lifting Aya to roughly 43M ounces by mid-2029. Q3 and Q4 historically deliver about 60% of annual silver production at the Moroccan operations because winter weather slows Q1 and Q2. A 400,000-ton ore stockpile gives the mill roughly two quarters of feed if mining halts, materially de-risking any short-term pit disruption. At a roughly $4B market cap, even conservative silver prices imply material upside as Boumadiene approaches commissioning.

McFarlane Lake Mining CEO And Largest Shareholder Discuss Latest Corporate News.
Key Highlights
brief- Michael Gentile cites Fresnillo's acquisition of Probe Gold at roughly $70-$80 per ounce in the ground as a valuation comparable for similar-sized deposits.
McFarlane Lake's Juby project grew to 6.2M oz inferred+indicated, a 50% jump from 4.2M oz with only 13,000m of drilling. The CEO projects another 3-4M oz on the way to a 10M oz target with 50,000-70,000m of additional drilling. Hanging wall drilling at the Juby deposit is hitting mineralization previously classified as waste, which could improve the strip ratio. Largest shareholder Gentile argues the US Treasury's bigger bond intervention signals yield curve control — bullish for gold. McFarlane trades at $25-27 per ounce in the ground versus $70-80 per ounce for peers like Probe Gold and Banyan Gold.

SILVER To 'Super Surge' After Debt-Based COLLAPSE - 'We're In the Red Zone': Francis Hunt
Key Highlights
brief- Fresnillo is cited by the guest as 'a very big producer,' placing it alongside First Majestic and Hecla as a silver miner whose chart pattern 'falls into the same kind of pattern' as the metals themselves.
Hunt argues a bond market failure since 2020 puts the dollar on a debt collapse path, with silver potentially surging to $1,000-plus. He expects a near-term disinflationary sell-off in metals before a 'super surge' once bond contagion forces the Fed's hand. Falling wedge breakouts in gold, silver, and mining ETFs (GDX, SILJ, Hecla) all flag the same bullish continuation pattern. Extreme-strike call-option volume reflects call-writing and position management rather than insider conviction of imminent moves. Physical coins and bars held in your hand are the only true hedge when counterparty risk spikes in paper-metal claims.
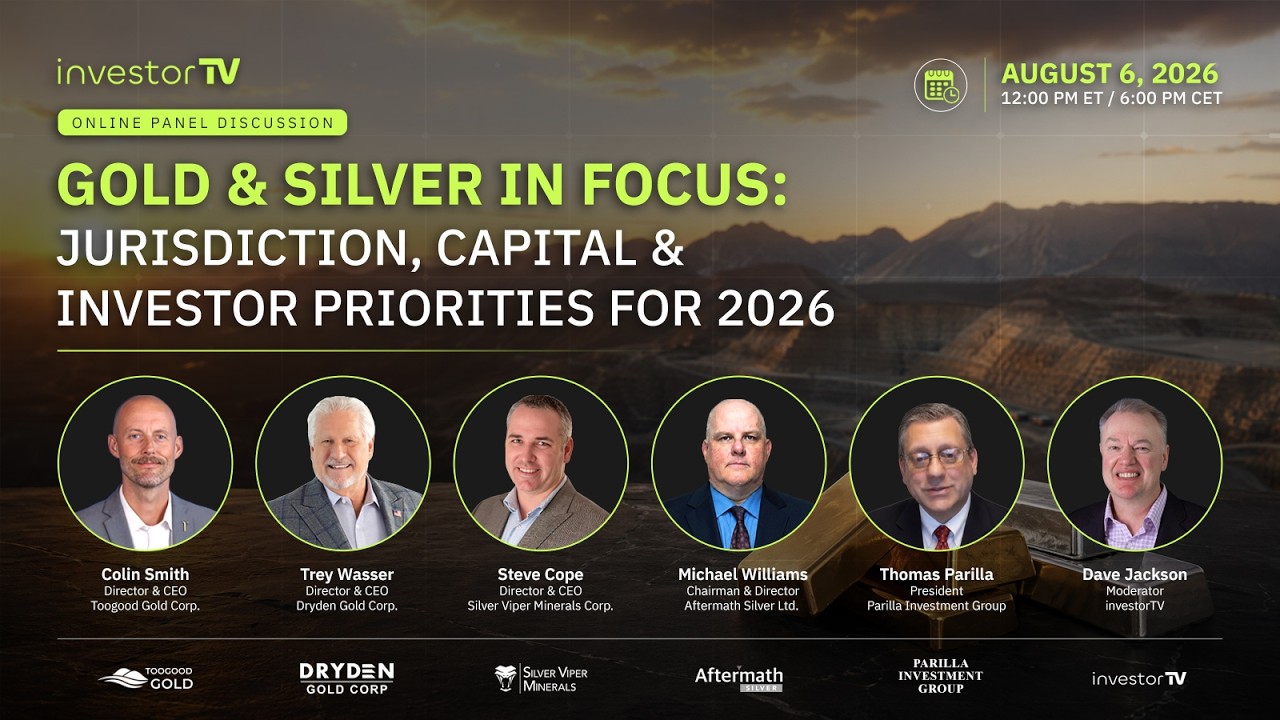
Gold & Silver in Focus: Jurisdiction, Capital & Investor Priorities for 2026 | August 6, 2026
Key Highlights
brief- Steve Cope says Fresnillo's silver threshold for partnership is 200 million silver-equivalent ounces to move the needle for the world's largest silver miner.
- Fresnillo joined Silver Viper's bidding war for Kineto, with Cope emphasizing that the Mexican-first miner prioritized the team's commitment to Mexico and local communities alongside asset quality.
Gold and silver sit at generational highs with structural fundamentals intact; both remain in the early innings of a multi-decade bull market. Junior mining equities have lagged physical metals despite record prices, creating a generational buying window for investors who pick the right teams. Grade and jurisdiction together drive valuation; Nevada, Ontario, Quebec, and Newfoundland command premiums that attract major capital today. Strategic backing by senior producers and funds like Fresnillo, Agnico, Alamos, and Eric Sprott acts as due diligence and signals quality. Capital discipline separates winners: leading juniors put 80 cents of every dollar into the ground and share evidence through steady news flow.

Mexico’s Next Silver Mine On Schedule for 2027 Production | Silver Tiger
Key Highlights
brief- Peter Gadsdon raises the Max Silver/Fresnillo JV as a precedent where commissioning-stage power access held the project back, using it to frame his question on whether Silver Tiger's CFE power grant materially de-risks the December 2027 pour.
Silver Tiger's fully permitted Stockwork Zone heap leach in Sonora, Mexico remains on schedule for commissioning and first doré pour in December 2027. About 200 workers are on site running three shifts a day; earthworks are underway and concrete work is set to start in October. CEO Glenn Jessome argues disciplined execution — not silver or gold price — drives shareholder value, with roughly $1 billion NPV at current prices. CFE granted life-of-mine grid power access via an 18-month third-party build, and redundant on-site generators let the project start regardless of timing. The underground PEA is being advanced to PFS, high-grade drilling has resumed to the north, and Mexico's improving permitting climate supports a broader re-rating.

Live Q&A with Rick Rule and Steve Barton
Key Highlights
brief- The speaker notes Fresnillo is cheaper than Pan American Silver, but warns that concentrating silver exposure in Mexico adds political-risk concentration.
- He flags this valuation argument alongside Buenaventura as a key reason some investors prefer those names despite the political risk.
Rising price is not the same as rising value; resource cycles typically run years, so time preference matters as much as entry timing. Focused copper producers like Southern Copper deliver more leverage than diversified majors such as BHP or Rio Tinto treat copper as a side business. Resource category confidence (measured and indicated versus inferred) and on-site infrastructure matter as much as headline ounces when comparing deposits. Royalty and streaming businesses reward patient capital over years; the next big deals will likely syndicate into bite-sized opportunities for tertiary players. Asymmetric exploration bets work only when the loss is affordable, with Rule framing NG Energy as a possible ten-bagger against a 30 to 50% loss.
Delta Gold Technologies ($DGQ | $DGQTF) CEO on Gold's Role in Quantum Computing
Key Highlights
brief- Per the guest, Fresnillo PLC made a hostile takeover bid for MAG Silver that the company publicly called a 'take under' — a dynamic he says Delta Gold must be aware of.
Delta Gold's CEO argues gold's electron spins could enable a new qubit design, with patents filed by University of Toronto and Penn State. The company holds exclusive licenses to university patents, funds one million dollars per university yearly, and targets 2028 for partnership talks. Qubit error rates remain the bottleneck: today's best run one error per 6.5 million operations, a billion times less stable than a laptop. Hosts urge junior-mining investors to expect losing half on any stock, diversify broadly, and judge holdings over years, not single quarters. Don Durrett calls the venture a roll-your-dice bet: the R&D and patents are done, but whether it becomes a computer is unproven.

50 buy-the-dip stocks (July 17, 2026)
Key Highlights
detailed- Fresnillo was expensive at one point but is trading around $32 as of mid-July 2026, and he notes it has come down quite a bit.
- At $7,000 gold and $200 silver he calculates both Fresnillo and First Majestic as eight-baggers.
- He calls that level of valuation unbelievable and says both have become very cheap.
He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.
Silver Could Sink Lower Before the Bull Run Resumes | James Anderson - Guanajuato Silver
Key Highlights
brief- The guest names Fresnillo, which he calls the largest silver mining company in the world, as the owner of several dormant mines sitting immediately adjacent to Guanajuato Silver's operations in the Guanajuato district.
- He says Fresnillo has shown no interest in selling those assets and that he respects that position, while arguing that a deal to consolidate them would be the most logical expansion path for Guanajuato Silver.
Anderson says silver's slide from the mid-$90s to the mid-$60s isn't over; he expects a bottom in months, not years, with the supply deficit unfixed. The guest calls the AI investment boom a bubble that resolves badly either way - mass job displacement, or trillions of capital mispriced and sold. Guanajuato Silver budgets 2026 conservatively at $54 silver and $3,920 gold, then sold some metal forward near the highs. Record Q1 revenue of $43 million included Bolanitos only from January 15; elevated AISC (all-in sustaining cost) reflects deliberate drilling and tunneling, not operating failure. Growth now hinges on consolidating the Guanajuato district; Fresnillo's adjacent dormant mines are the prize for a company built on acquisitions.

Javier Reyes, Head of Luca Mining Corp. | Rule Symposium 2026: Rick Rule interviews
Key Highlights
brief- The guest says Luca Mining recently bought a large block of ground at Tahuahuitl from Fresnillo, which he calls the largest silver company in the world, at a reasonable price thanks to the existing relationship, extending Luca's exploration footprint.
Luca Mining is now self-funding: it ended 2025 with roughly $25 million cash and cut debt from $60 million to about $1 million. The guest explains the model: buy fully permitted, underperforming Mexican assets cheaply, fix community and capital problems, then repeat the process. Its two Mexican operations hold close to 4 million combined gold-equivalent ounces (all metals valued as gold), with drilling at full speed on both. Q1 2026 added $10 million cash and over 15,000 gold-equivalent ounces; management targets 100,000, then 250,000 ounces via acquisitions. The guest argues Mexico is fast becoming a safer, top-ranked mining jurisdiction, and Luca is acquiring assets before that becomes widely recognized.

Why This Gold Company Keeps Spinning Out Assets | John Mark Staude - Riverside Resources
Riverside Resources is actively spinning out assets, including the Blue Jay project and its Mexico portfolio, to unlock shareholder value. The company is strategically shifting towards a royalty-focused model by organically creating royalties instead of purchasing them. With key partnerships and projects across Mexico and British Columbia, Riverside anticipates multiple catalysts over the next 12 months.
Don Durrett & John Feneck Explore First Tellurium’s ($FTEL | $FSTTF) PyroDelta Energy Stake
Key Highlights
brief- Don lists Fresnillo among his nine 'Mormon' silver producers that he expects to be highly profitable at $200 silver and urges viewers to buy now.
PyroDelta's thermoelectric generators (solid-state devices that turn waste heat into electricity) need only a 20°C differential and run 24/7. First Tellurium (CSE: FTEL), which management calls the world's only tellurium-focused company, owns 83% of PyroDelta plus a high-grade British Columbia project. Acceptance into DARPA's Lift Challenge (Dayton, Ohio, August 2) brings prize potential and introductions to defense primes and drone-delivery buyers. Durrett argues small silver producers gain huge margin above $200 silver, though he cautions developers take years and often disappoint before paying off. Co-hosts note 131 million shares out with roughly 35% in friendly hands, giving the 11-cent junior room to move on DARPA news.

Newsletter Favorites Sorted by Quality (April 2026)
Key Highlights
detailed- Don Durrett calls Fresnillo the number one silver producer, at about 50 million ounces of silver a year.
- He says he is surprised he has not rated it a 3.5 on the downside because he sees it only as a marginal five-bagger.
- That marginal multiple profile is what keeps Fresnillo out of the 3.5 bucket.
- He is also surprised his downside rating is only a 3, which he attributes to Fresnillo being all in Mexico.
Durrett ranks the 89 gold and silver stocks he owns on upside, downside risk, and company quality — a system investors can copy. His 'three-five' score marks a likely five-bagger — a stock he expects could multiply roughly five times from current levels. Only four holdings earn an A, reserved for low costs, clean balance sheets, and consistent execution — Australian mid-tier producers dominate the top. Country risk caps otherwise strong names: West African, Mexican, and Colombian exposure keeps ratings below top marks. He flags likely takeover targets among focused developers and producers still generating free cash flow.

Americas Gold and Silver ($USA | $USAS): Silver and Antimony Opportunity in Idaho
Key Highlights
brief- Don Durrett says Fresnillo has no growth in the pipeline, grouping it with the large silver producers without production growth.
- He nonetheless includes Fresnillo among the no-growth names he still wants to own because he expects them to do extremely well in the bull market.
CEO Paul Andre Huet says the turnaround is on track: silver output stepped up 50% and targets a 3.6 million ounce run rate by year end. Huet reports Galena's measured and indicated resource — the higher-confidence categories — rose 19%, with grades up 21%, past 200 million silver ounces. Huet describes a US Antimony joint venture that turns previously penalized antimony into revenue, with an Idaho plant backed by price protection. Don Durrett frames gold and the S&P 500 as a 'final battle' gold will win, urging investors to stay invested and buy dips. With about $130 million US in cash and no planned equity raise, management says drilling at Galena, Crescent, and Cosala will be funded from operations.

A Closer Look at LaFleur Minerals' Low CAPEX Path to Gold Production
Key Highlights
brief- The CEO calls Fresnillo's buyout of Probe Gold a big event for the area, noting most of those projects sit near the Beacon Mill.
- LaFleur will look at whether projects Fresnillo may consider non-core after the Probe takeover could be brought into LaFleur.
LaFleur Minerals' new PEA (Preliminary Economic Assessment) charts a $31M CAD restart built around its wholly-owned Beacon Gold Mill. The $2,750 gold base case yields an AISC (All-In Sustaining Cost — what it really costs to produce an ounce) just under $1,600. CEO Paul Ténière says a 100,000-tonne bulk sample feeds the mill first, with the full production decision following those results. Beacon Mill refurbishment is just over 50% complete and on budget, with the first gold pour targeted for later in 2026. Regional M&A — Probe Gold's buyout by Fresnillo — could free up non-core projects near LaFleur's mill, management says.

Uranium Market Update | Justin Huhn and Jimmy Connor
Key Highlights
brief- The host cites Fresnillo, which he calls the world's largest silver producer, as a Mexican company that acquired a Quebec-based gold developer in late 2025 for about $800 million, to illustrate how buyers pay up for safe jurisdictions.
- The host calls that deal price fairly cheap next to names like NexGen, using it to argue top mining jurisdictions command a premium.
Strait of Hormuz disruption risks sulfur supply for uranium processing; Namibia's Husab and Rossing face output losses if imports stall for weeks. Kazatomprom's growth increasingly serves the east: almost half of 2025 sales went to China, and its new JV project's output goes entirely to Russia. Term uranium sits near $90 a pound with spot around $83; Sprott's physical trust has bought about 6 million pounds of its 2026 allotment. US executive orders target 10 large new reactors under construction by 2030, yet America consumes 45 to 50 million pounds yearly and produces far less. The guest argues NexGen's Arrow is the supply linchpin, but timeline slippage and Kazakh mine decline rates leave the 2030s supply gap unresolved.

Newsletter Favorites Overview (Feb 2026)
Key Highlights
detailed- Don says Fresnillo is starting to get pricey - he recommended it under $10 and it now trades around $52 at a $38 billion market cap.
- He still thinks it has legs, showing as roughly a 3-bagger with potential for 4 or 5.
- He calls it a shark that will keep growing by acquisition - he expects it to acquire neighbor Cabral - and he wants to own the sharks.
Durrett argues there is limited time left to buy gold and silver producers while they are still cheap, expecting one more significant dip. His Newsletter Favorites list leans on quality Canadian and Australian mid-tier producers, which he expects to re-rate as the bull market warms up. Companies whose second and third projects get no market value offer free upside — you pay for the first asset and get the rest for nothing. Cheap forward free-cash-flow multiples persist in West Africa and among silver producers, where weak sentiment discounts heavy leverage to metal prices. Australian producers like Ramelius reaching major-sized valuations is, in his view, the first sign the junior gold bull market is broadening.

McEwen Buys Golden Lake | A Small Deal With a Big Lesson
Key Highlights
brief- The host cites Fresnillo's acquisition of development-stage Probe Gold as a 39% premium benchmark against the 60% premium McEwen paid for Golden Lake
McEwen's all-stock acquisition of Golden Lake at a 60% premium validates the closeology thesis for penny juniors sitting next to producing mines. Golden Lake's Jewel Ridge claims sit adjacent to McEwen's Eureka/Gold Bar complex, sandwiched next to the Windfall and Lookout Mountain discoveries. Junior deal premia dwarf typical mining M&A: Core/New Gold at 16%, Fresnillo/Probe Gold at 39%, IAMGOLD/Northern Superior at 27%. McEwen's 2025 plan calls for 36,000 meters of drilling in Nevada, with Eureka central to extending Gold Bar's mine life.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.