Hecla Mining Company
HLHecla Mining Company, together with its subsidiaries, discovers, acquires, develops, and produces precious and base metal properties in the United States and internationally. The company mines for silver, gold, lead, and zinc concentrates, as well as carbon material containing silver and gold for sale to custom smelters, metal traders, and third-party processors,; and doré containing silver and gold. It owns 100% interests in the Greens Creek mine located on Admiralty Island in southeast Alaska; the Lucky Friday mine situated in northern Idaho; the Casa Berardi mine located in the Abitibi region of northwestern Quebec, Canada; and the San Sebastian mine situated in the city of Durango, Mexico. The company also holds 100% interests in the Fire Creek mine located in Lander County, Nevada; and the Hollister and Midas mines situated in Elko County, Nevada. Hecla Mining Company was incorporated in 1891 and is headquartered in Coeur d'Alene, Idaho.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Hecla Mining Company
Sector
Precious Metal
Founded
March 17, 1980
Employees
1,830
Reporting Currency
USD
Contact Phone
208 769 4100
Website
www.hecla-mining.comHeadquarters Address
6500 North Mineral Drive , Coeur d'Alene , ID 83815-9408 , US
Identifiers
Commodity Portfolio
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos
Building a 500,000-Ounce-a-Year Gold Producer | Patrick Downey - Orezone Gold
Key Highlights
brief- Downey says Orezone bought the Hecla assets in Quebec, now anchored by the Casa Berardi mine, where a newly published baseline Life of Mine study shows about 116,000 oz/yr over a 14-year mine life.
Orezone CEO Patrick Downey calls the past 12 months the best mining sentiment of his 40-year career, with good projects finally getting financed. Downey maps a path from about 230,000 ounces of annual gold production to roughly 500,000 ounces, pointing to Bomboré, Casa Berardi and the development pipeline. He argues the market gives zero value to Heva-Hosco in Quebec, where a 2012 feasibility study showed roughly 105,000 ounces a year over 14 years. The year ahead looks catalyst-rich: a Heva-Hosco study, drill results at Casa Berardi and Bomboré, and a life-of-mine study (a whole-mine plan). Downey says Orezone holds over $100 million in cash with little or no debt and would buy back stock if the discount persists.

This 100-Year-Old Silver Mine Keeps Getting Bigger | Oliver Turner - Americas Gold and Silver
Turner says a decade of capital starvation ended in 2025; new exploration money at Galena has already produced six new high-grade discoveries. Galena is one of the world's highest-grade silver mines — about 500 g/t (grams of silver per tonne) — with more than 200 million ounces. A renegotiated smelter contract now pays for all byproducts, and a planned antimony leaching facility with US Antimony should lift recoveries further. The guest points to de-bottlenecking (clearing production constraints) at Galena as what to watch, targeting 3.2 to 3.6 million silver ounces this year.
Jason Webber of Silver North Resources Ltd. talks to Peter Krauth | Metals Investor Forum Sept. 2026
Key Highlights
detailed- Weber says Hecla's deep drilling in the Keno Hill district keeps returning very high grades from 600-800 meters depth, showing these silver zones continue well below the 350 meters Silver North has drilled so far.
- Weber credits Hecla with actively sharing 100 years of district exploration data with the industry, which he says makes Silver North's own exploration at Haldane more successful.
- Per Weber, Hecla's geologists say any hole that hits silver must be followed up, because an intercept that looks low-grade or uninteresting can turn into a high-grade one just 50-100 meters later.
- Weber notes Silver North's Haldane claim package butts directly against Hecla's, about 20 kilometers from Hecla's Keno facilities, and that Hecla's arrival in the district gave it added credibility.
Silver North's CEO argues brand-new discoveries in Yukon's century-old Keno Hill district show historic silver camps still hide overlooked high-grade veins. Haldane returned 13 meters of 818 grams per ton silver with gold — high grades that can add ounces quickly even in small deposits. Hecla's arrival in the district adds credibility and shared century-old data, and weak drill intercepts can flag high-grade 50 to 100 meters away. At Veronica, the company targets CRD (carbonate replacement) deposits near Coeur's Silvertip mine, using geophysics, soils, and mapping to ground-truth anomalies. Two rigs have drilled since early July with no assays (lab metal analyses) back yet; results from late September into January are the catalyst.
Jason Webber of Silver North Resources presents at Metals Investor Forum in Vancouver | Sep 2026
Key Highlights
detailed- Per Webber, Hecla is in production next door at the Keno Hill mine and its claim package holds most of the district's roughly 65 identified silver deposits.
- Webber credits Hecla with sharing 100 years of district data and exploration know-how that helped Silver North make its new discoveries.
- The 6-9 g/t gold turning up in Silver North's intersections has caught Hecla's attention, and per Webber the miner wants to pin down where that gold enters the system.
Silver North pivoted from metal-agnostic explorer to silver-focused company in 2023, centered on the historic Keno Hill silver district in the Yukon. Haldane drilling has hit silver in 80% of 24 holes, including 13 meters averaging 818 grams per ton with a gold credit. Intersections run 6 to 9 grams per ton gold in places, enough that neighbouring producer Hecla is investigating where the gold enters the system. Only about 10% of 12 kilometers of mapped vein-hosting structures have been drilled, leaving ample discovery runway across the 100-year-old district. Roughly 24 holes and 6,200 meters from the 2026 program should start reporting news flow by end of September, running through January.
Banyan Gold Targets Q4 PEA at AurMac After 8.6 Million Ounce Resource
Key Highlights
brief- Called out by the interviewer as Banyan's next-door neighbour doing a fantastic job.
Banyan Gold's AurMac deposit now hosts 8.62 million ounces (indicated plus inferred) at a 0.30 g/t cutoff, with a maiden PEA due in Q4 2026. The maiden PEA (preliminary economic assessment — first economics for a project) is due in Q4, with analyst ranges of 30,000-40,000 tpd and 250,000+ ounces annually. High-grade drilling in the Airstrip-Powerline gap — 13.03 g/t gold over 14.2 metres in hole AX-26-874 — could lift early production years if mineralization connects. First holes at Nitra, 25 km west, hit Roaring Fork and Seattle Creek — 5.70 g/t gold with 544 g/t silver — pointing to district scale. Recently added to the GDXJ index, Banyan expects C$30-40 million by end-2027 and plans eight rigs from 15 January 2027 for at least 70,000 metres.

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile
Aya's Zgounder mine is running as a cash machine: Q2 revenue up 151% YoY, operating cash flow up 522%, with payback on $140M capex inside five months. Boumadiene is targeting 37M ounces of silver a year at an AISC (all-in sustaining cost) under $15, lifting Aya to roughly 43M ounces by mid-2029. Q3 and Q4 historically deliver about 60% of annual silver production at the Moroccan operations because winter weather slows Q1 and Q2. A 400,000-ton ore stockpile gives the mill roughly two quarters of feed if mining halts, materially de-risking any short-term pit disruption. At a roughly $4B market cap, even conservative silver prices imply material upside as Boumadiene approaches commissioning.
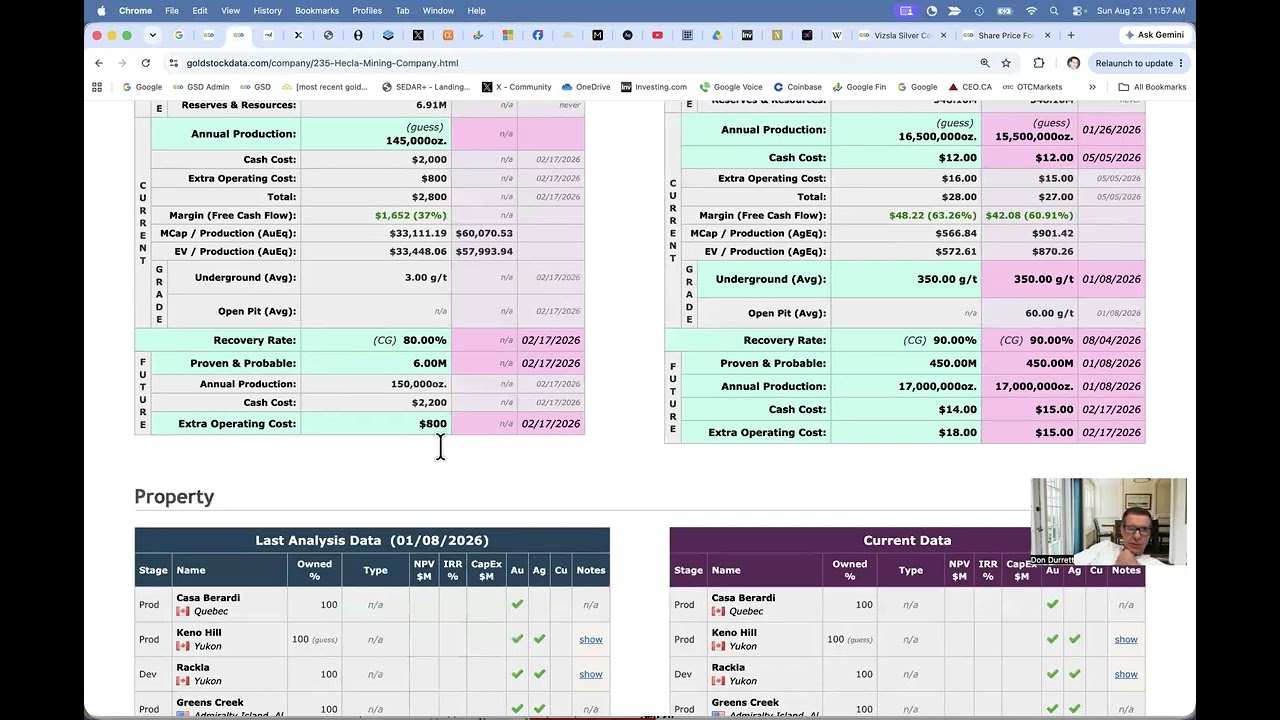
Share Price Forecast Tool (August 2026)
Key Highlights
detailed- Don's model has Hecla roughly doubling within 12 months only if silver reaches an all-time high near $110, while his three-year case at $200 silver makes it a four- to five-bagger with a target around $100.
- GoldStockData currently rates Hecla a five-bagger — about 520% upside with a $128 target — which Don reproduces using future fully diluted market cap and cash-flow growth rather than resources.
- He puts Hecla's current free cash flow at about $650 million, growing toward $3 billion, on all-silver production with an AISC around $17.
- Don expects Hecla to keep buying back shares, so he holds the share count roughly flat in the three-year case instead of adding dilution.
- In tail scenarios, $250 silver makes Hecla a six-bagger and $300 an eight-bagger, and a 33 multiple would mean a nine- or ten-bagger.
A share price forecast tool turns production, share count, cost, and silver price assumptions into 12-month and three-year return scenarios for miners. Durrett models Hecla at roughly a double in 12 months near $110 silver, and a four- to five-bagger at $200 silver in three years. Developer Vizsla Silver prints the biggest scenarios: a 30-bagger at $200 silver and 40-bagger at $250 silver, with $480 million cash limiting dilution. AISC (all-in sustaining cost — what it fully costs to produce an ounce) and the price-to-cash-flow multiple are the main levers besides metal price. He adjusts developer share counts for expected dilution and capex (upfront capital spending), and expects producer buybacks to shrink share counts.
Mining Can Make You Rich or Wipe You Out | Ross Beaty
Beaty likens exploration investing to a casino — high risk, low return, though rare 10-bagger discoveries can emerge on the Lassonde curve. Equinox Gold targets ~1.9 million ounces of annual production via Nevada's new Railroad mine and existing assets, with no further deals required. Beaty personally bought $10 million of Equinox shares after retiring, citing the team's growth runway and a strong balance sheet. Lumina Metals' Polish copper-silver deposit ranks among the world's largest, with $6 billion capex financing plausibly available in today's market. Beaty kills project interest in the first hour over non-geological issues: no water, no power, hostile communities, or missing roads.
Ted Oakley: 'An Accident Waiting To Happen', Why You Need to Own Hard Assets & Oil and Gas
Key Highlights
detailed- The guest says he sold HL in the low $30s and bought it back near $15 in mid-July 2026, calling it one of his most opportunistic recent trades during the precious-metals correction.
- He picks HL as the one clean silver miner he wants to own alongside physical silver, noting silver is still a buy and will chase gold higher.
- He prefers HL over smaller, more volatile silver miners because, in his words, he has owned it a long time and 'they do well.'
- He frames HL as part of his hard-asset thesis: at least 10% of a portfolio should sit in miners plus gold to offset currency debasement.
A 35-40% mid-July correction left gold miners cheap on cash flow — Oakley's firm is buying producers back at these levels. Roughly 10% in gold and miners is the minimum hedge against Western debt loads, aging demographics, and continued money printing. Royalty models sidestep cost creep because the operator pays the royalty before operating expenses rise. Energy stocks stay profitable at $70 oil, and U.S. dependence on imported uranium and critical minerals leaves long-term supply at risk.

SILVER To 'Super Surge' After Debt-Based COLLAPSE - 'We're In the Red Zone': Francis Hunt
Key Highlights
brief- The guest specifically chose Hecla Mining for his silver chart because it is 'big in silver,' using it to illustrate a falling-wedge breakout with a noted ~$14 level referenced against the ~$56 silver and ~$4,000 gold print.
- Hecla is grouped with First Majestic and Fresnillo as silver miners whose technicals are tracking the silver price, though the guest warns these charts are an investment vehicle rather than a clean trading tool because of downside gaps.
Hunt argues a bond market failure since 2020 puts the dollar on a debt collapse path, with silver potentially surging to $1,000-plus. He expects a near-term disinflationary sell-off in metals before a 'super surge' once bond contagion forces the Fed's hand. Falling wedge breakouts in gold, silver, and mining ETFs (GDX, SILJ, Hecla) all flag the same bullish continuation pattern. Extreme-strike call-option volume reflects call-writing and position management rather than insider conviction of imminent moves. Physical coins and bars held in your hand are the only true hedge when counterparty risk spikes in paper-metal claims.
Why They Bought This Gold Mine | Patrick Downey - Orezone Gold Corp.
Key Highlights
brief- Hecla is receiving 9.9% equity as part of the consideration paid by Orezone for the acquired asset.
Orezone financed a $160M gold-mine acquisition with less than 10% dilution by leaning on Franco Nevada and its own cash. Franco Nevada funded $100M of the upfront price and contributed technical due diligence; Orezone added $60M of its own cash. Hecla took 9.9% equity in the deal, plus deferred payments of $30M and $50M at 18 and 30 months. Orezone first established its Bambori (Bomboré) operations into a strong cash-flowing base before pursuing the acquisition.
Gold & Silver Breakout! Endgame Is Near | David Morgan
Key Highlights
brief- Morgan cites a Hecla Mining spokesperson with direct federal government ties he met at the Montana Mining Association gathering in Butte, asking whether the federal government would consider rebuilding a strategic silver stockpile.
- Hecla Mining is framed only in passing as the most publicly identifiable silver-focused name at the gathering; no production, reserve, or financial figures for the company are discussed.
David Morgan calls a confirmed breakout in silver and gold, but warns a final August flush-down is still possible. COMEX silver isn’t being drained — registered inventory oscillates between roughly 30M and 90M ounces — though the LBMA float sits tighter than headlines suggest. Short-term manipulation is real (a JP Morgan spoofing fine topped $900M) but, Morgan argues, the long-term trend cannot be suppressed. Industrial buyers now absorb roughly 60% of annual silver supply versus 35% twenty-five years ago — Morgan likens it to a structural buyback. The yen carry trade unwind risks cascading into international debt markets, reinforcing Morgan’s warning that the global monetary “end game” is near.
Masterclass: Investing in Gold/Silver Mining Stocks (Part 3)
Key Highlights
brief- The host groups Hecla with Coeur as a producer with no growth pipeline visible in the next three years
Don Durrett walks through his producer, developer, and explorer checklists for getting an edge in gold/silver mining stocks. Producers must score 7-9 on his 10-point rubric: long-life flagship mines, clean balance sheets, and at least a 5x bagger at his $7,000 gold. Developers must check all six boxes: NPV at 2x CapEx or better, 25%+ IRR at spot, and at least a 10x bagger to absorb dilution. Explorers shine in bear markets because they are inelastic; buy gold in the ground below 1% of spot and enter early in the Lassonde curve. Specific calls: Alamos Gold and Kenros screen as 6x baggers in the current correction, while Vizsla Silver's NPV runs at 5x its CapEx.

Live Q&A with Rick Rule and Steve Barton
Key Highlights
brief- Rule is not a Hecla shareholder, citing a poor 20-year asset allocation track record where reserve/resource additions from margin generated on ounce sales have been net negative — destroying rather than adding capital
- He notes Hecla is generating meaningful cash now and is extremely leveraged to a silver price spike, with an American-silver premium benefit
Rick Rule frames currency debasement and a structural copper deficit as multi-year themes, and treats the uranium pullback as a buying window rather than a topping signal. Two majors as shareholders of a junior like Founders Metals create real auction tension if a discovery is made, plus adult supervision and a tighter effective float. Rule sizes lithium as a processing-bottleneck story, not a raw-material shortage, and flags direct lithium extraction from oil and gas brines as the long-term threat to hard-rock producers. Abitibi 'orphan' deposits such as Emperor Metals can now monetize via nearby mills, removing the capex bar that once left them undeveloped in past cycles. Rule is constructive on Cameco, Origin Royalties, Alamos, Emperor, B2Gold, and Cheniere; he is cautious on lithium juniors and explicitly refuses to time the uranium market.

Why Gold Is Refusing to Break | Patrick Downey - Orezone Gold
Key Highlights
brief- Sold the Casa Berardi mine in Quebec to Orezone Gold in March 2026 as part of a deal package that included $160M upfront and a 9.9% equity stake in Orezone for Hecla.
The guest reads gold's flat trend near $4,000 as stabilization before another leg higher, supported by central bank, ETF, and currency demand pillars. Orezone added Casa Berardi with less than 10% dilution by leaning on Franco-Nevada's upfront funding and Bomboré's free cash flow. The Casa Berardi deal gives Orezone a self-funded two-mine platform aiming for 220,000–250,000 oz in 2026, ramping toward 300,000 and 500,000 oz. Casa Berardi sits on a 37-kilometre prospective belt in the Abitibi; Orezone plans 100,000 to 120,000 metres a year to revive the orogenic system. Quebec's existing permits and underground expertise made Casa Berardi accretive without the greenfield permitting risk.

Gold & Silver Opportunities: Discovery, Development & Growth | July 16, 2026
Key Highlights
brief- Shawn Khunkhun cites Hecla as the only company of its kind in North America today, in business for 140 years, and the benchmark Contango Silver & Gold merged to compete with.
- He says Hecla reached a valuation of nearly $20 billion in Q1 2026 on the strength of that existing business.
Central bank buying of over 850 tonnes took gold to record levels in January 2026, and the panel says producer margins sit at historic extremes. Silver is heading into a sixth straight year of supply deficit, with annual mine output falling from 1.2 billion ounces toward 800 million. Robert Eckford argues jurisdiction now outranks project size, and points to New Zealand's six-month permitting as the competitive edge. Peter Espig's rule: fund projects that are not yet cash generative with equity, and reserve debt for producing mines expanding output. Chris Kerlow uses a barbell portfolio — about 80% in large producers, 20% in juniors expected to generate most of the returns.

50 buy-the-dip stocks (July 17, 2026)
Key Highlights
brief- Hecla shows up as another eight-bagger on his list of 50 buy-the-dip names.
- He says buying a Hecla at an eight-bagger valuation is absolutely crazy.
He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.
THESE Gold & Silver Stocks a Screaming BUY - 'More Bullish Than Ever': John Feneck and Don Durrett
Key Highlights
brief- Durrett puts Hecla at the top of his 12-month silver-producer picks, together with Core Mining.
- He argues Hecla and comparable names are in good North American locations, trade in New York and will be bought for scarcity because few listed stocks fit that description.
Durrett frames the metals selloff as a correction, not the end of the gold bull market, which he says only breaks below $3,000. Both guests attribute the drop since March 1st to the Iran war rather than mine fundamentals, and warn of another seasonal dip this fall. Feneck's development picks include Silverco, Blackrock Silver and Silver 47, each trading far below its spring highs on unchanged plans. Durrett's stock lists split by horizon: quality North American producers for a year, developers for three-to-five-year multi-bagger attempts. Feneck is bullish on tungsten equities despite an 8-9x spot price surge, because China supplies about 80% and no ETF or futures market exists.

GoGold Fully Funded: Los Ricos South Construction Starts - Path to 17 Moz
Key Highlights
brief- The guest names Hecla as a good comparable because its cost of production is very low, and says GoGold aspires to reach those cost levels over time.
GoGold holds $284 million in cash against roughly $250 million of updated capex, funding the Los Ricos South silver-gold build in Jalisco debt-free. The CEO guides to $12-15 AISC (All-In Sustaining Cost — what it really costs to produce an ounce), a margin that holds up if prices fall. Permits are secured, detailed engineering is 80% complete and the SAG mill is ordered, so the 24-month build could finish early. Output is slated to rise from about 2 million ounces (Moz) silver-equivalent to 9 Moz, then 15-17 Moz once Los Ricos North is built. Management calls the district generational: 15 years of planned reserves plus untested old workings and targets such as San Pedro Alco.
Why Silver and Gold Are Headed Back to All-Time Highs | Shawn Khunkhun - Contango Silver & Gold
Key Highlights
brief- Khunkhun says Hecla, not First Majestic or Pan American, is the right comparison for Contango because its projects sit in the US and Canada.
- He frames Hecla as the mid-tier producer Contango aims to resemble, noting Contango traded near a $600 million valuation at the time of the interview versus roughly $10 billion for Hecla.
Contango retired all its gold hedges, which President Shawn Khunkhun presents as conviction that gold is bottoming even if silver retests $50 to $55. The direct shipping ore model (DSO — selling high-grade rock to outside mills) skips new plants and tailings permitting, cutting capital and timelines. Khunkhun argues the merger discount is fading: gold peers average about 0.7 NAV (net asset value), and silver producers can trade at twice that. A Kitsault Valley resource estimate arrives in July, switched to S-K 1300 reporting after the merger, with 40,000 metres of drilling feeding catalysts. Khunkhun guides 75,000-80,000 ounces in 2027 at a $1,200-1,300 AISC (All-In Sustaining Cost — full production cost per ounce), implying $200 million potential free cash flow.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.