Kootenay Silver Inc logo

Kootenay Silver Inc

KTN

Kootenay Silver Inc., an exploration stage company, engages in the acquisition, exploration, and development of mineral properties in Mexico and Canada. The company explores for silver, gold, lead, and zinc ores. It primarily holds interests in the La Cigarra silver project covering an area of approximately 18,000 hectares located within the Parral Mining District in the state of Chihuahua, north central Mexico; Promontorio and La Negra silver discoveries situated in Sonora, Mexico; Columba Silver project located in Chihuahua, Mexico; and Copalito Silver-gold project located in Sinaloa, Mexico. The company was formerly known as Kootenay Gold Inc. and changed its name to Kootenay Silver Inc. in February 2012. Kootenay Silver Inc. is based in Vancouver, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Kootenay Silver Inc

Sector

Precious Metal

Founded

October 25, 2007

Reporting Currency

CAD

Contact Phone

604 601 5650

Headquarters Address

595 Howe Street , Vancouver , BC V6C 2T5 , CA

Identifiers

Commodity Portfolio

AG Silver Primary
AU Gold Byproduct
PB Lead Byproduct
ZN Zinc Byproduct

Stock Exchanges

KTN TSXV • CAD
KTN:CVE
KOOYF OTC • USD
KOOYF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

They Found 54 Million Ounces of Silver, Now They Want More | Dale Brittliffe - Kootenay Silver

They Found 54 Million Ounces of Silver, Now They Want More | Dale Brittliffe - Kootenay Silver

The Deep Dive
18 days ago 5:41

Key Highlights

detailed
  • The guest says the flagship Colombo Silver project yielded a maiden inferred resource of 54 million ounces of pure silver (not silver equivalent) in mid-2025, and describes the team as now focused on growing that number through the current 60,000-meter program.
  • The recently published La Cigarra PEA returned an NPV of $1.3 billion and a 64% IRR at $67/oz silver and $4,200/oz gold, as quoted in the interview, after the company had been waiting for higher silver prices to advance the asset.
  • Colombo is described as a large epithermal system with main vein widths averaging 4.5 meters, high-grade cores, and stockwork veining extending up to 10 meters into the wall rock, which the guest cites as the reason for the long drill intercepts reported to date.
  • Drilling started on Colombo in 2019 and the current 60,000-meter program is more than halfway complete; the next phase is shifting from extending known veins to testing new epithermal veins that have not yet been drilled.
  • Mexico permitting remains the main hurdle to production, but the guest notes recent open-pit permit approvals (citing Teck's San Nicolas as an example) and says engineering work — metal rock leaching, acid-base analysis, and tailings — is underway to advance La Cigarra toward pre-feasibility.

Kootenay's $1.3 billion NPV La Cigarra PEA (Preliminary Economic Assessment — first look at project economics) shows what stronger silver prices unlock for advanced projects. Kootenay is past halfway through a 60,000-metre drill program designed to grow its maiden 54-million-ounce Columba inferred resource. Production has become the dominant theme at the Beaver Creek summit, pulling investor attention back to advanced silver developers. Mexico's open-pit permitting queue is starting to clear, with the first new approvals signaling progress for stalled projects. Columba's epithermal system (veins formed from low-temperature fluids near the surface) hosts wide silver veins with high-grade cores and broad stockwork halos.

Kootenay Silver's 14-Year Mine Plan

Kootenay Silver's 14-Year Mine Plan

VRIC Media
3 months ago

Key Highlights

detailed
  • The CEO says the newly launched PEA for La Saguera shows positive economics with a 14-year mine life.
  • Per the PEA, production averages 4.5 million ounces of silver a year over the 14 years, with the first five years above 6 million ounces annually.
  • He stresses these are pure silver ounces, not silver-equivalent.
  • He argues a mine life beyond 10 years gives the company time to ride out commodity cycles, convert more ounces to reserve, and work through startup issues.

A mine life beyond 10 years gives a project time to ride out commodity cycles and fix startup problems, the guest argues. Kootenay Silver's La Saguera PEA (Preliminary Economic Assessment — an early economics study) outlines a 14-year mine life averaging 4.5 million silver ounces yearly. The first five years are expected to run above 6 million ounces of silver — pure silver ounces, not silver-equivalent.

The Silver Bull Market Is Just Getting Started - Here’s Why

The Silver Bull Market Is Just Getting Started - Here’s Why

VRIC Media
3 months ago

Key Highlights

detailed
  • The PEA released in mid-2026 on La Cigarra is what moves Kootenay from explorer to developer: at the banks' $50/oz forward silver price the study shows a $763 million after-tax NPV and a 41% after-tax IRR, rising to about $1.2 billion NPV at $65/oz, per the CEO on the July 2026 interview.
  • La Cigarra's economics are a 14-year initial mine life averaging about 4.5 million ounces of silver a year, more than 6 million ounces a year in the first five years, roughly $18-20 per ounce all-in sustaining cost, and just under 64 million payable ounces.
  • Capital cost is about $332 million including more than $50 million of contingency, which the CEO calls a sensible buffer because PEA-to-PFS costs tend to inflate, producing an after-tax payback of just under two years.
  • A fall 2026 drill program of about 7,000 meters within a budgeted 10,000 meters costing just over $3 million targets the gap between the Sangrigoria and Las Carolinas pits, which sits inside the existing pit shell and was never drilled; the CEO sees potential for 10-20 million ounces there and expects an answer by year end, with about $34 million in the treasury.
  • Columba in the same Chihuahua district is being expanded by roughly 60,000 meters of drilling toward 100 million ounces from a high-grade inferred resource above 280 grams per tonne; the CEO says the 100 million target is aspirational, a resource update is due around the end of 2026 into Q1 2027, and the two projects are to carry separate strategies such as building, a joint venture or a sale.

Kootenay Silver now develops two Mexican silver projects after a preliminary economic assessment (PEA) on La Cigarra showed $763 million after-tax NPV at $50 silver. AISC (All-In Sustaining Cost - what it really costs to produce an ounce) is forecast below $19, with payback under two years at La Cigarra. The guest argues silver is forming a new price band several times higher than the mid-$20s range it occupied for years. A 7,000-metre fall drill program targets the undrilled gap between two deposits, a low-cost path to 10 to 20 million more ounces by year end. Columba's high-grade inferred resource is being drilled toward 100 million ounces, funded by about $34 million in cash.

This Could Be Silver’s Next Monster Mine | AbraSilver Diablillos DFS

This Could Be Silver’s Next Monster Mine | AbraSilver Diablillos DFS

The Deep Dive
3 months ago

Junior miners cannot choose when good news lands, and this feasibility study hit on a day silver fell more than 5%. Phase one is a 25-year open pit processing 9,000 tonnes of ore a day, averaging 10.3 million silver-equivalent ounces annually. The first five years average 20.3 million silver-equivalent ounces, so the profile is heavily front-loaded rather than level. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) of $19.98 and $722 million of capital look readily financeable. Senior producers trade above one times NAV while developers sit at a discount; the host puts this project near the peer average.

SILVER Back to Triple Digits THIS Year? 'Dramatic' Move Coming

SILVER Back to Triple Digits THIS Year? 'Dramatic' Move Coming

Commodity Culture
4 months ago

Key Highlights

detailed
  • James McDonald says the PEA released in June 2026 on the La Seguera deposit shows an after-tax NPV of USD$763M and a 41% IRR using a $50/oz consensus long-term silver price, transitioning Kootenay from explorer to developer.
  • La Seguera hosts 60Moz measured and indicated plus 17Moz inferred, and a 10,000m drill program starting in fall 2026 targets a gap in the resource shell that McDonald estimates could add another 10-20Moz, potentially followed by a resource update and PEA refresh.
  • Columba carries a 54Moz inferred maiden resource at 284 g/t from a year before the interview; the company is roughly halfway through a 60,000m expansion drill program, with a resource update expected around end-2026 that could justify a second PEA.
  • March 2026 step-out holes at Columba's D-vane returned intercepts including 34m at roughly 500 g/t, 17m at nearly 650 g/t, and 98m at over 200 g/t (true width about half), per McDonald, with about 60% of current ounces in that zone and all zones open.
  • McDonald says the La Seguera PEA outlines a 14-year mine life producing over 6Moz annually in its first five years, and argues the market has not yet recognized the value of the four-deposit pipeline, which he says is well financed.

The guest argues silver's 50% slide from January's $120-plus peak is consolidation inside a bull market, with triple digits possible this year. Six consecutive deficit years and a 10-to-20-year mine development timeline mean silver supply cannot quickly respond to rising demand, the guest notes. Governments now treat silver as strategic: US stockpiling, Russian central-bank buying, Saudi ETF purchases, and Chinese export controls tighten available supply. A first PEA (Preliminary Economic Assessment — early-stage mine economics) gives Kootenay's La Seguera a $763M after-tax NPV and 41% IRR at $50 silver. High-grade Columba drill results, including 98 metres at 200 g/t (grams per tonne) silver, feed a 60,000-metre program and a year-end resource update.

This Silver Project Looks Great, If Mexico Lets It Happen | Kootenay Silver La Cigarra PEA

This Silver Project Looks Great, If Mexico Lets It Happen | Kootenay Silver La Cigarra PEA

The Deep Dive
4 months ago

Key Highlights

detailed
  • The host argues Kootenay's new PEA for La Cigarra in Chihuahua, Mexico shows a $763 million after-tax NPV at a 5% discount rate, a 41% IRR, and payback inside two years — based on $50 silver as of the recording (around 2026-06-19).
  • The host notes the plan is a conventional open pit producing an average of 4.6 million ounces of silver per year over a 14-year mine life, with years 1-5 front-loaded at about 6.2 million ounces, and over 94% of revenue expected from silver despite it being effectively a lead-zinc mine.
  • The host lays out the capital and cost picture: $332 million initial capital plus $80 million sustaining, operating cash costs of $16.85 per silver equivalent ounce and all-in sustaining costs of $18.73 per ounce — figures he thinks look low versus current market realities, warning costs almost always rise through the development curve.
  • The host highlights the valuation gap: the $763 million NPV translates to about C$1.1 billion against an enterprise value of roughly $111 million at recording time, roughly a 0.1x multiple on the base case and 0.06x on the spot model ($67+ silver, $1.3 billion NPV, 64% IRR), with another 261 million ounces on other properties not counted.
  • The host cautions the project carries inferred resources requiring more exploration before pre-feasibility, permitting for a Mexican open pit is a major risk despite Chihuahua's mining-friendly district (two operating neighbors, 450 million ounces produced since 1650), and the PEA news release was light on mine plan, processing, and infrastructure detail.

Kootenay Silver's La Cigarra PEA projects a $763 million after-tax NPV at $50 silver, and $1.3 billion at spot pricing. The company trades near 0.1x NPV on a $111 million enterprise value, a discount partly attributed to Mexican open-pit permitting risk. A planned 14-year open pit averaging 4.6 million ounces of silver yearly carries $332 million initial capital and $1,873 per ounce AISC (all-in sustaining cost — what it really costs to produce an ounce). The production plan includes inferred resources (less certain resource estimates), so further exploration is needed before the project can advance to pre-feasibility. Permitting for open-pit mining in Mexico remains the key overhang, even in Chihuahua where mining has operated for centuries.

Galactic Gold is Hunting for Untapped Gold Next to Canada's Newest Major Mine

Galactic Gold is Hunting for Untapped Gold Next to Canada's Newest Major Mine

CEO.CA
4 months ago 8:29

Key Highlights

detailed
  • Ken Berry says he co-founded Kootenay Silver with Jim McDonald more than 24 years ago, and that it holds four key silver projects in Mexico with more than 400Moz of silver in the ground.
  • Berry says Galactic used Kootenay's contact network, especially European investors based primarily in Switzerland, to help fill its recent financing.
  • Kootenay has completed multiple financings over its history, experience Berry cites as part of the Galactic team's background.
  • Berry notes Kootenay's CEO Jim McDonald also serves as one of Galactic Gold's advisors.

Galactic Gold assembled 57 kilometres of strike length — how far the gold-bearing structure runs — next to Equinox Gold's new multi-million-ounce mine in Ontario. Metal Earth research by Laurentian University — over $140 million of Ontario funding — targets orogenic fault systems that spawn some of the largest gold deposits. A completed 2,300-kilometer airborne survey (VTEM and MAG geophysics) prioritized three to four targets, including Sturgeon Bridge, for drilling in coming months. A recently closed C$2 million financing, upsized from C$1 million, leaves about 55 million shares outstanding with Swiss and Canadian institutional participation. The team co-founded Kootenay Silver and took Northern Vertex from exploration into production in Arizona, a track record spanning 25 to 30 years.

#96 Digging for Dollars #24 Raising $100M, Execution is Everything

#96 Digging for Dollars #24 Raising $100M, Execution is Everything

CEO.CA
6 months ago 44:30

Key Highlights

detailed
  • Guest Tony Rita pitches Kootenay as a Mexico silver company with a market cap around $159 million, four assets, three with resource estimates, totaling over 400 million ounces of silver — a sum he admits is not 43-101 compliant.
  • The company holds over $25 million in cash and will publish a maiden PEA, which he expects will reframe the La Sagara project and act as a share price catalyst.
  • Kootenay plans about 40,000 metres of drilling in 2026, expanding known high-grade zones and testing never-drilled targets for discovery potential.
  • The judges dig or re-dig the story, arguing the stock was beaten down with Mexico broadly even though Kootenay sits in a safer part of the country.

Amex Exploration's Perron feasibility study shows how grade and low capex create value: $1.13B after-tax NPV at $3,500 gold and about a half-year payback. AISC (all-in sustaining cost — what an ounce really costs to produce) near $910 and third-party toll milling keep Perron buildable without heavy upfront infrastructure. Tectonic Metals founder Tony Reda explains raising roughly $100M after one drill year at the Flat project, a camp-scale Alaska gold play beside 40M-ounce Donlin. Dig This Deal pitches: Kootenay Silver offers 400M silver ounces ahead of its first PEA (preliminary economic assessment); copper picks highlight jurisdiction risk. Takeaways for any junior: net asset value (NAV) to capex ratios gauge financeability, strip ratios rival grade, and buildable projects make the best takeover candidates.

De-risking Is The Strategy

De-risking Is The Strategy

VRIC Media
6 months ago

Kootenay Silver CEO outlines two primary paths for mining projects: building into production or positioning for strategic acquisition. Advancing and de-risking assets is presented as a core strategy to maximize project value regardless of the chosen exit path. The discussion highlights how proper asset de-risking directly enhances shareholder value and attracts potential acquirers in the mining sector.

Optionality Update - April 2026

Optionality Update - April 2026

Don Durrett
6 months ago

Key Highlights

brief
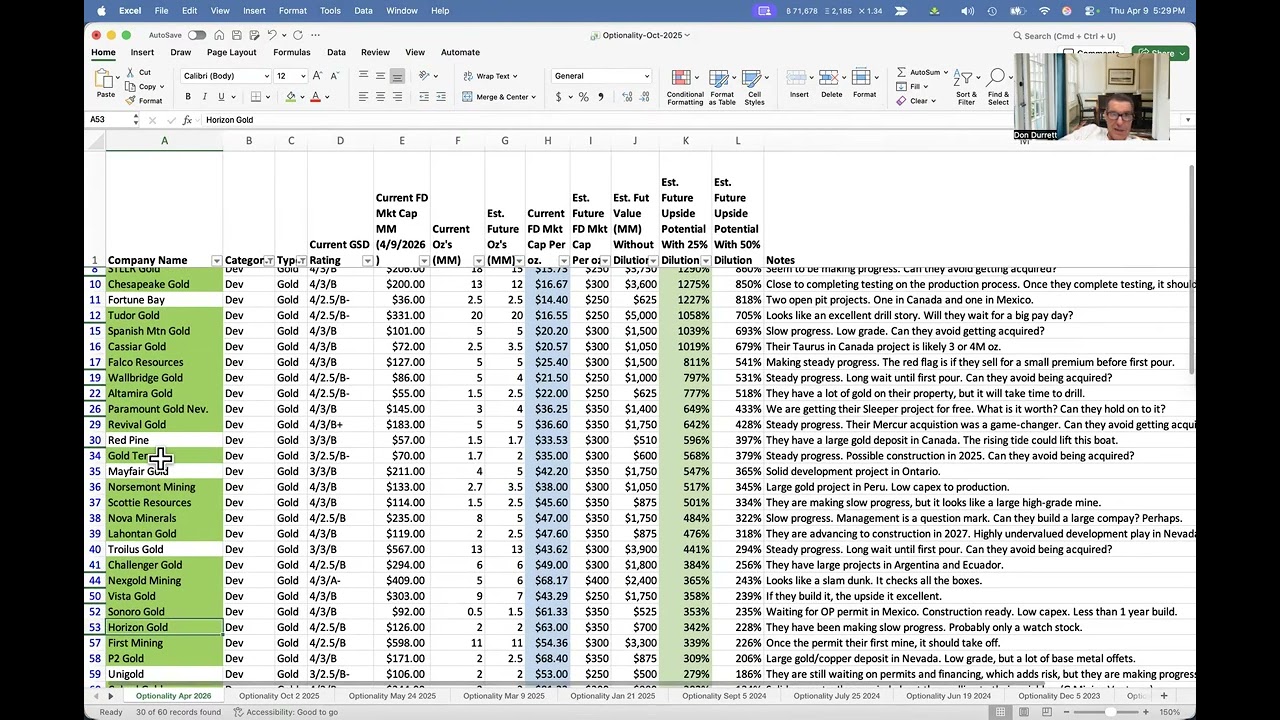
  • Durrett counts Kootenay Silver among silver explorers he could see pivoting to development rather than staying an exploration play.

G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Positioned for a Silver Breakout

Positioned for a Silver Breakout

VRIC Media
6 months ago

Kootenay Silver strategically positioned its projects years ahead for a potential silver price breakout. Company updated resources and prepared development plans early to capitalize on strengthening market conditions. Early preparation allows rapid project advancement as silver market fundamentals continue to improve.

Articles

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord