Mayfair Gold Corp logo

Mayfair Gold Corp

MFG

Mayfair Gold Corp. acquires, explores, evaluates, and develops mineral properties. It holds 100% interests in the Fenn-Gib gold project with 21 fee simple patented properties, 153 patented leasehold mining claims, and 144 unpatented mining claims covering an area of approximately 4,800 hectares located in the Guibord, Munro, Michaud, and McCool Townships in northeast Ontario, Canada. The company was incorporated in 2019 and is based in Matheson, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Mayfair Gold Corp

Sector

Precious Metal

Founded

January 27, 2026

Reporting Currency

USD

Contact Phone

800-342-6705

Headquarters Address

489 McDougall Street , Matheson , ON P0K 1N0 , CA

Identifiers

Commodity Portfolio

AU Gold Primary

Stock Exchanges

MINE AMEX • USD
MINE:NYSEAMERICAN
MFG TSXV • CAD
MFG:CVE
MFGCF OTC • USD
MFGCF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Drew Anwyll: This Gold Mine Could Generate $1.4 BILLION in Free Cash Flow

Drew Anwyll: This Gold Mine Could Generate $1.4 BILLION in Free Cash Flow

VRIC Media
about 1 month ago 23:08

Key Highlights

detailed
  • Drew Anwyll says Fenn-Gib can generate ~$1.4B of free cash flow over the first six years at ~$4,400/oz gold, based on the pre-feasibility (average ~1.5 g/t grade in the first six years, 6:1 strip ratio, high-grade material at surface).
  • Mayfair completed FEED with Senco in early August 2026 and submitted its application for Ontario's new 1P1 (One Project, One Process) permitting stream the same month; Anwyll expects to hear back within weeks and is aiming to be the first company out of the process, with the 1P1 stream cutting the normal ~3-4 year Ontario permitting timeline to ~18 months to 2 years.
  • The company held ~$23M cash at end of Q2 2026 with a ~$2M/month burn — runway into Q1 2027 but not all the way to a construction decision; Anwyll is targeting roughly $300M of project debt against ~$450M capex, with the balance as equity, and expects the debt facility to close around Q4 2026 / Q1 2027.
  • A construction decision is targeted for 2028; Fenn-Gib holds ~4.3M oz of resource but only ~25% (~1M oz reserve) is in the initial mine plan, with high-grade material deliberately brought forward in the schedule.
  • A new VP Exploration, Audrea De Lazer, has been hired to target the south block along the Porcupine Destor Fault, with a drill program expected to start in January 2027 once the ground freezes.

Anwyll projects roughly $1.4B of free cash flow from Fenn-Gib's first six years, driven by near-surface high-grade ore at current gold prices. Ontario's new One Project, One Process framework could halve the typical 3-4 year permit timeline — Mayfair has applied. Anwyll targets roughly $300M of debt against an estimated $450M initial capex, with a 2028 construction decision on the line. First Nations partnership with Abitibi and Ishibek is a Section 35 permitting prerequisite, not a stakeholder checkbox. Beyond the planned first mine, Mayfair positions itself as a multi-mine operator, with a south block pipeline along the Porcupine-Dester fault.

Nick Campbell: This Could Be The Next Billion Tonne District

Nick Campbell: This Could Be The Next Billion Tonne District

VRIC Media
about 1 month ago 21:08

Key Highlights

brief
  • The speaker says he was CEO of Mayfair Gold before leaving to take the CEO role at Phoenix Metals, and that he brought in Drew Anwell, now Mayfair's CEO, as a serious mine builder during his tenure.

A 55,000-metre systematic drill program is finally testing the historic Greenwood Copper-Gold District in BC for scale across three targets. Three main zones — Phoenix South, JD Golden Crown, and Lexington — could together host a billion-tonne district at high grades. Existing roads, rail, power, a permitted mill, and tailings storage save roughly a couple hundred million dollars of development capex. Phoenix is fully funded with $50M cash for a two-year exploration program, giving investors two years of news flow without dilution. First Lexington drill results are expected in October, with Phoenix target results in November — assays take roughly six weeks.

GOLD Just Became a Real Alternative to the Dollar (Here’s Why): Nick Campbell

GOLD Just Became a Real Alternative to the Dollar (Here’s Why): Nick Campbell

Commodity Culture
about 1 month ago 47:26

Key Highlights

brief
  • The guest says he was previously CEO of Mayfair Gold and recently stepped down to take the Phoenix Metals role, with Drew Anwell taking over as Mayfair's CEO.
  • He notes he remains a Mayfair shareholder and describes the team he built there as high quality.

Gold's structural bull case rests on central bank diversification away from the USD, accelerated by the 2022 dollar weaponization. Copper supply stays tight because major mines need roughly 25 years from discovery to production, supporting prices above $6/lb. Phoenix Metals controls the consolidated Greenwood copper-gold district in British Columbia, with bulk-tonnage (large-volume, low-grade) potential of up to a billion tonnes. CEO Nick Campbell's track record spans Silvercrest and Artemis, both of which he helped grow from small-cap juniors to multi-billion-dollar producers. First Lexington drill results are due October 2026, with a PEA (Preliminary Economic Assessment) on the permitted mill targeted for next year.

Live Q&A with Rick Rule and Steve Barton

Live Q&A with Rick Rule and Steve Barton

Rule Investment Media
2 months ago

Key Highlights

brief
  • Rule is trying to bring himself to rank Mayfair but says the resource statement differs from the reserve statement and he cannot get to a million mineable ounces in his own mind
  • He states he will not rank the company until he sees that level of in-situ recoverable reserves

Rick Rule frames currency debasement and a structural copper deficit as multi-year themes, and treats the uranium pullback as a buying window rather than a topping signal. Two majors as shareholders of a junior like Founders Metals create real auction tension if a discovery is made, plus adult supervision and a tighter effective float. Rule sizes lithium as a processing-bottleneck story, not a raw-material shortage, and flags direct lithium extraction from oil and gas brines as the long-term threat to hard-rock producers. Abitibi 'orphan' deposits such as Emperor Metals can now monetize via nearby mills, removing the capex bar that once left them undeveloped in past cycles. Rule is constructive on Cameco, Origin Royalties, Alamos, Emperor, B2Gold, and Cheniere; he is cautious on lithium juniors and explicitly refuses to time the uranium market.

Jeff Clark’s 5 Best Mining Stock Picks Right Now

Jeff Clark’s 5 Best Mining Stock Picks Right Now

VRIC Media
3 months ago

Key Highlights

brief
  • The interviewer cites Mayfair Gold, which he says has roughly a 3 million ounce resource and a 1 million ounce reserve.
  • It is used to frame the resource-builder stage, where the open question is whether the balance converts to reserves, a step the guest says de-risks the asset for a producer or acquirer.

Jeff Clark invests in four junior mining stages — pre-discovery, pre-resource, resource builder and pre-producer — and avoids developers and producers. Each of his five picks has given back January gains, and he argues those pullbacks make the entry points attractive right now. Turning resources into reserves cuts project risk and makes a company more attractive to senior buyers, even when the resource barely grows. His five: A2 Gold, Pacifica Silver, Stallion Uranium, Sun Peak Metals in Saudi Arabia, and Getty Copper, which he ranks lowest risk. Pre-discovery stories can take three to six drill programs, and he warns a compelling geophysical footprint does not guarantee another deposit.

Jeff Clark: SILVER Is 50% Off—and the Biggest Opportunity Is Coming

Jeff Clark: SILVER Is 50% Off—and the Biggest Opportunity Is Coming

VRIC Media
3 months ago

Key Highlights

brief
  • The host raises Mayfair Gold as an example of a resource builder, citing a roughly 3 million ounce resource and 1 million ounce of reserves, and asks how the remaining ounces get converted into reserves.
  • The guest answers generally that many resource builders either grow the resource or convert it to reserves, and that conversion reduces risk and makes the asset more attractive to a senior or a producer looking for ounces.

The guest treats big sector corrections as buying opportunities, having loaded up on the COVID dip and buying this sell-off now. Silver is the better-value metal — its equities fell over 50%, and the gold-silver ratio near 68 sits above its long-run average of 55. He skips developers and producers, concentrating on four stages: pre-discovery, pre-resource, resource builders, and pre-producers. Converting resource to reserve cuts risk more than growing it, because conversion is what makes an asset saleable to a senior. His screening rules: a pro-mining jurisdiction, management actually investing its own money, and a deposit big enough to matter to a producer.

RPX Gold ($RPX | $RDEXF): A Staged Strategy Toward Gold Production in Ontario

RPX Gold ($RPX | $RDEXF): A Staged Strategy Toward Gold Production in Ontario

Investor TV
4 months ago

Key Highlights

brief
  • Michaud counts Mayfair's CEO among RPX's directors, part of a board he says is determined to build value rather than sell; the hosts note that gives RPX 'two CEOs on their board.'

RPX Gold's staged plan mines small starter pits and hauls ore to area toll mills (third-party processing plants), funding growth without heavy shareholder dilution. Startup capex sits under $50 million, with roughly $75 million in targeted annual free cash flow to fund drilling and the eventual underground decision. The consolidated property holds a 1.7-million-ounce resource drilled only to about 300 meters along a seven-kilometer gold structure. No on-site mill or tailings means no Environmental Assessment (EA) is required, with management hoping for permits in place by summer 2027. Both analysts frame the June metals break as a normal bull-market correction in which silver falls harder than gold, creating buying windows in juniors.

Mayfair Gold’s Timmins Advantage

Mayfair Gold’s Timmins Advantage

VRIC Media
4 months ago

Key Highlights

detailed
  • CEO Drew Anwyll calls the Fenn-Gib location near the Timmins mining camp one of the best he has worked in, citing experienced, mining-familiar government agencies in the area.
  • The project sits less than an hour from Timmins' skilled mining workforce, with additional labor available from Cochrane, Kirkland Lake, and Matheson.
  • The town of Matheson is strongly supportive of the project — the company knows the mayor and CAO, who want to help bring the mine into production.
  • Fenn-Gib has strong existing infrastructure: a highway crosses the property and power is within 17 kilometers of the site (as of the June 2026 interview).
  • Mayfair wants to collaborate with neighbor McEwen Mining so both companies succeed.

Mayfair Gold argues its Fenn-Gibb project's location beside the Timmins mining camp gives it experienced regulators, labour and local support. Skilled mining labour sits less than an hour away in Timmins, with additional workers available in Cochrane, Matheson and Kirkland Lake. Highway access across the property and power within 17 kilometres reduce the practical cost of advancing Fenn-Gibb toward production. CEO Drew Anwyll says Mayfair wants to work with neighbour McEwen so both adjacent operations can succeed.

Mayfair Gold’s Huge Upside & Perfect Timing

Mayfair Gold’s Huge Upside & Perfect Timing

VRIC Media
4 months ago

Mayfair Gold is advancing its Fenn-Gib gold project in Ontario's Timmins region from exploration toward production, focusing on execution during a favorable gold market. CEO Drew Anwyll argues that the project offers significant leverage to higher gold prices due to its large resource base and current market valuation. The company is actively navigating permitting, engineering, and financing milestones, which Anwyll views as key catalysts for creating shareholder value.

Rick Rule: Gold will Soar Over The Next 10 Years

Rick Rule: Gold will Soar Over The Next 10 Years

VRIC Media
4 months ago

Rick Rule argues that rising U.S. deficits and unattractive long-duration bonds create a strong macroeconomic backdrop for gold over the next decade. A wave of mergers and acquisitions is approaching for gold miners, with Rule highlighting Equinox, Calibre, and Orla as potential acquirers or targets. Rule sees uranium demand rising due to global energy security concerns, favoring developers like NexGen and UEC, alongside Uranium Royalty's acquisition strategy.

Post-Forum Interview: Drew Anwyll of Mayfair Gold Corp. with Robert Sinn (May Metals Investor Forum)

Post-Forum Interview: Drew Anwyll of Mayfair Gold Corp. with Robert Sinn (May Metals Investor Forum)

Metals Investor Forum
4 months ago

Mayfair Gold's Fenn-Gib project in Ontario shows strong economics with a $652M after-tax NPV (Net Present Value — the present value of future cash flows) and a 2.7-year payback period. The 4.3 million-ounce gold project targets average annual production of roughly 64,000 ounces over a 14.3-year mine life. Drew Anwyll emphasizes using existing infrastructure in the Timmins gold district to advance the project toward production with capital discipline.

#102 Digging for Dollars #30 Talking our Portfolio and Top Picks

#102 Digging for Dollars #30 Talking our Portfolio and Top Picks

CEO.CA
4 months ago 30:14

Key Highlights

brief
  • Alex Ruggieri's pitch, the show's very first, has not been exciting, a host says, but it has still outperformed the market.

Early private-market entries into juniors re-rated hard when they listed, beating flat TSX Venture and GDXJ benchmarks at mid-year. Sterling Metals' Batchawana Copper Belt consolidation shows why the hosts buy whole districts early instead of waiting for neighbors to prove up. Galantas Gold's $100 million raise shows how a large, well-supported financing lets a near-term producer reach cash flow without repeated dilution. With no senior tungsten producers, Allied Critical Metals' year-end pilot plant in Portugal offers juniors-only exposure to a quintupled price. Stagnant juniors with strong treasuries and intact teams remain the buys — own value before promotion arrives and prices move.

Drew Anwyll of Mayfair Gold Corp. presents at Metals Investor Forum in Vancouver | May 2026

Drew Anwyll of Mayfair Gold Corp. presents at Metals Investor Forum in Vancouver | May 2026

Metals Investor Forum
5 months ago

Drew Anwyll, CEO of Mayfair Gold Corp., presents the company's investment thesis at the Metals Investor Forum in Vancouver. The forum highlights companies vetted by newsletter writers for having excellent management, strong financials, and promising properties. Investors gain exclusive access to assess junior mining management teams through direct, face-to-face Q&A interaction.

Drew Anwyll of Mayfair Gold Corp. presents at Metals Investor Forum in Vancouver | May 2026

Drew Anwyll of Mayfair Gold Corp. presents at Metals Investor Forum in Vancouver | May 2026

Metals Investor Forum
5 months ago

Drew Anwyll, COO of Mayfair Gold Corp., presents a corporate update at the Metals Investor Forum in Vancouver. The presentation highlights the company's promising properties, financials, and management team for potential investors. The forum provides investors a unique opportunity to directly assess junior mining management teams face-to-face.

Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario

Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario

Investor TV
6 months ago

Key Highlights

detailed
  • CEO Nick Campbell's pitch is a deliberately small 4,800-tonne-per-day open pit kept under the 5,000-tonne federal threshold so it can be permitted provincially in 2-3 years, with permits targeted for early 2028 via Ontario's Project One process and first gold in 2030, instead of a billion-dollar mine facing 7-9 years of federal permitting.
  • The Q1 2026 pre-feasibility plan mines 1.47 g/t ore over the first six years for roughly 70,000-75,000 ounces a year at about 90% recovery, with AISC under $1,200/oz and free cash flow of about $150 million a year at $3,100 gold or $249 million at $4,450, on C$450 million of build costs.
  • Financing is set at about $300 million of debt plus roughly $250 million of equity over three years including the $35 million on the balance sheet, funded into mid-2027; Campbell argues a 10% free-cash-flow yield would support a ~$2.5 billion valuation versus a ~$300 million market cap at the time of the interview.
  • Growth is planned by feeding the Timmins mill rather than expanding throughput, using high-grade tonnes from regional underground mines and three properties just acquired from Plato Gold, haulable up to 150 km along Highway 101; any expansion past 5,000 tpd would require the 7-9-year federal track, so the wider 4.3-million-ounce indicated resource could wait until the late 2030s, which Campbell concedes.
  • Alignment is a selling point: about $19 million of insider buying since October 2024 leaves roughly 35% insider ownership (the hosts tally closer to 40%), and Campbell has rebuilt the team since a proxy battle, adding COO Drew Anwyll, a former Barrick North America CFO, and a sales-focused VP of capital markets aimed at generalist investors.

Mayfair Gold is permitting a 4,800 tonne-per-day starter pit at Fenn-Gib provincially, cutting years off the federal route to first production. Projects under 5,000 tonnes per day permit provincially in Ontario, avoiding a federal review where no new (greenfield) mine has won approval since 2019. Management guides to a sub-$1,200 AISC (All-In Sustaining Cost — the full cost to produce an ounce) and first gold in 2030. Staying small preserves optionality: regional high-grade and underground tonnes can sweeten mill feed (raise average grade) without expanding throughput or new federal permits. Don Durrett favors undervalued, leveraged silver producers while John Fenwick argues war headlines, not fundamentals, gate gold's next move.

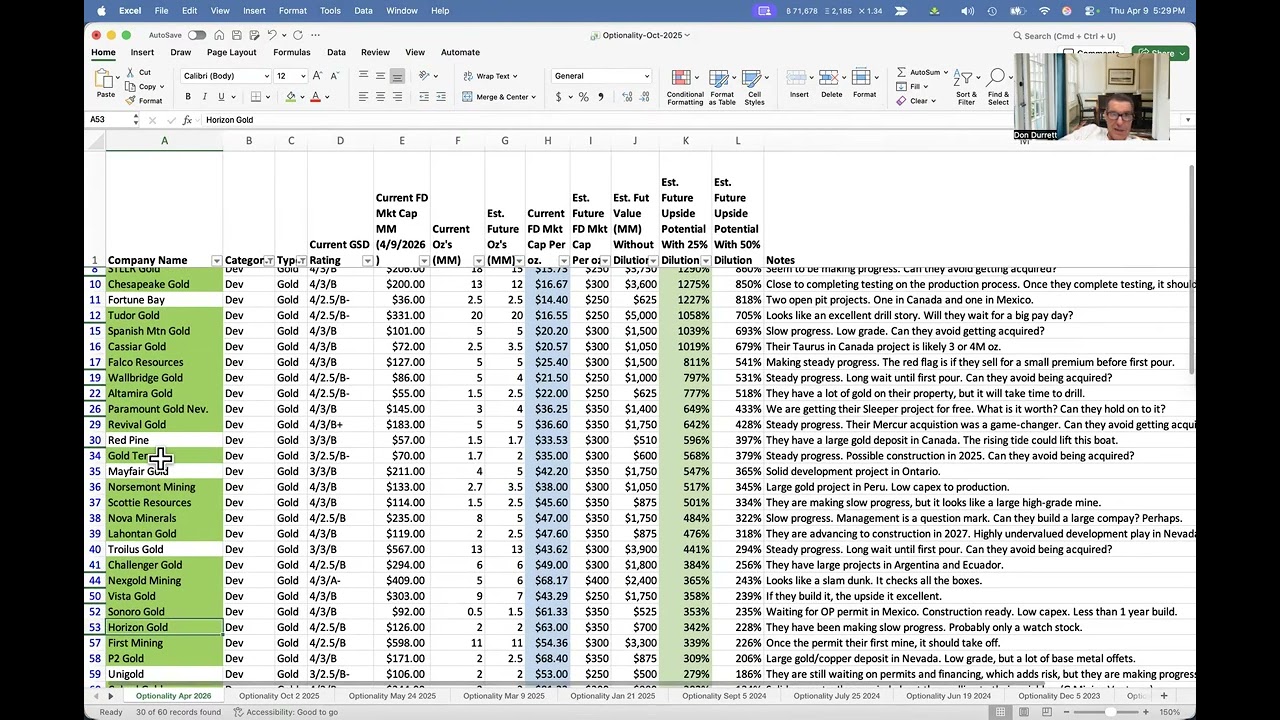
Optionality Update - April 2026

Optionality Update - April 2026

Don Durrett
6 months ago

Key Highlights

brief
  • Durrett says he has thought about buying Mayfair Gold a few times but has not pulled the trigger.

G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Proven Investment Strategies for the “Energy Decade” with Resource Insider’s Jamie Keech

Proven Investment Strategies for the “Energy Decade” with Resource Insider’s Jamie Keech

MiningStockEducation.com
6 months ago

Key Highlights

detailed
  • Keech says Mayfair Gold rolled its board, replaced its management team and has started advancing its assets significantly.
  • Resource Insider is still a shareholder and has made roughly a 100% return on Mayfair over the two years to early April 2026.
  • He calls that return mediocre for the current market, since the stock has underperformed its peers.
  • He offers two readings of that gap - an inferior asset and inferior team that is not valued appropriately, or governance and team problems that leave the stock undervalued - and says Resource Insider sits in the second camp.
  • He says there is still a lot of upside potential at Mayfair and that many of his readers hold the stock as well.

Tech's growth has outrun the physical world's carrying capacity, making energy — not technology — the binding investment constraint of the decade. An audit of 40-plus mining investments found advanced-stage explorers with defined resources and stable jurisdictions consistently outperformed, often doubling to 5X. Grassroots drilling carried a near-100% failure rate, so returns came from private placements bought cheap and listed within 6 to 18 months. An Oklahoma royalty venture and a North Dakota terminal bought at 5.7x EBITDA (core cash earnings) now pay dividends to private investors. Junior mining is a capital-raising game where pressure to raise often turns operators from prey into predators, per Keech.

Nicholas Campbell of Mayfair Gold Corp. presents at Metals Investor Forum in Toronto | February 2026

Nicholas Campbell of Mayfair Gold Corp. presents at Metals Investor Forum in Toronto | February 2026

Metals Investor Forum
7 months ago

Mayfair Gold Corp CEO Nicholas Campbell presents company updates at the Metals Investor Forum in Toronto, targeting retail and institutional investors. The forum highlights vetted junior mining companies with excellent management teams, strong financials, and promising properties selected by newsletter writers. Investors gain exclusive access to assess management quality through direct interaction and critical Q&A sessions at this premier mining investment event.

The Gold Project Everyone Will Judge Wrong | Mayfair Fenn Gib PFS

The Gold Project Everyone Will Judge Wrong | Mayfair Fenn Gib PFS

The Deep Dive
9 months ago

Mayfair Gold's Fenn Gib project delivers strong PFS economics with robust NPV and IRR metrics Project demonstrates competitive all-in sustaining costs positioning it well in current gold price environment Analysis suggests market may be undervaluing the project's near-term production potential and scale

Articles

Mayfair Gold Targets $1.4B in First-Six-Year Free Cash Flow at Fenn-Gib

Drew Anwyll, Mayfair Gold's CEO, says the Fenn-Gib project's first six years of mining could generate about $1.4B in free cash flow at current gold prices, with an average grade of 1.5 g/t and AISC just over $1,200/oz. The company has wrapped up FEED, applied for Ontario's 1P1 permitting track, and is targeting a 2028 construction decision.

about 1 month ago
Drew Anwyll: This Gold Mine Could Generate $1.4 BILLION in Free Cash Flow
Read article
Mayfair Gold's Smaller-Mine Bet: A 4,800-Tonne-a-Day Starter Pit at Fenn-Gib Targets First Gold in 2030

On Investor TV, Mayfair Gold CEO Nicholas Campbell laid out a deliberately small start for the Fenn-Gib project in Ontario's Timmins district: a 4,800-tonne-per-day open pit producing roughly 70,000-75,000 ounces a year, permitted provincially in 2-3 years, with first gold targeted for 2030. Analysts Don Durrett and John Feneck see five-to-10-bagger potential but note the trade-off: most of the 4.3-million-ounce resource may wait until the late 2030s.

6 months ago
Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord