Maple Gold Mines Ltd
MGMMaple Gold Mines Ltd. operates as a gold exploration company in Canada. It holds interest in the Douay gold project with 691 mineral claims covering an area of approximately 369 square kilometers located in the Casa Berardi deformation zone in the Abitibi Greenstone Belt of northern Quebec; and the Joutel project covering an area of approximately 39 square kilometers located in Quebec, Canada. The company was formerly known as Aurvista Gold Corporation and changed its name to Maple Gold Mines Ltd. in November 2017. Maple Gold Mines Ltd. was incorporated in 2010 and is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Maple Gold Mines Ltd
Sector
Precious Metal
Founded
August 2, 2012
Employees
13
Reporting Currency
CAD
Contact Phone
647-265-8688
Website
www.maplegoldmines.comHeadquarters Address
1111 W Hastings St , Vancouver , BC V6E 2J3 , CA
Identifiers
ISIN
CA5651276027Commodity Portfolio
Stock Exchanges
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

Michael Gentile Latest Macro Outlook, Specific Holdings, Featuring McFarlane Lake Mining Limited
Key Highlights
detailed- Gentile calls Maple and McFarlane Lake the two cheapest, 'table-pounding' bulk gold deposits of scale in the Abitibi that investors have not woken up to, trading around US$25-30 per ounce in the ground.
- He credits Maple with 4-5 million ounces of resource today and a credible pathway to 6, 7, 8, even 10 million ounces — arguing the stock cannot make sense at less than 1% of the spot gold price with gold around $4,000.
- He highlights the high-grade underground zone (already about 1 million ounces, a former mine operated by Agnico): every hole drilled in the open ground has hit, and he would not be surprised by 2-3 million ounces at 4-5 g/t within 24 months.
- He adds as breaking news that Maple joins his October European roadshow — another under-followed story he will introduce to institutional investors for the first time.
Fixing a junior's balance sheet can trigger a rerating faster than drilling: clearing debt and pulling in warrants revived a stalled gold developer. Gold developers can trade at a quarter of peers per ounce in the ground once a debt overhang lifts, leaving a wide value gap. Michael Gentile argues gold producers still trade below 1x NAV while copper peers re-rated, so generalist money has yet to arrive in gold. Consistent, low-cost drilling across several juniors keeps adding ounces every few weeks before the market pays attention to the results. The strongest junior positions keep making new highs; add when the story still strengthens instead of selling success by reflex.

Live Q&A with Rick Rule, hosted by Steve Barton 📱
Key Highlights
detailed- Rick has upgraded Maple Gold from a six to a five on his scale.
- He dropped his 'me too' objection after re-examining Abitibi infrastructure: improved roads, power, and - critically - access to processing facilities let a deposit without the reserves to fund its own mill truck material to an adjacent hungry mill.
- He always liked the deposit's size and potential; lack of infrastructure access was the knock that kept the ranking down.
Rick Rule argues resource equities remain reasonably priced after two years of gains, but a 2008-style liquidity crisis could force overexposed investors to sell. Consolidation keeps rewarding shareholders: mergers cut duplicated overhead, and larger miners gain index inclusion, passive buying, and a lower cost of capital. Oil's move from $65 to $105 is anticipatory pricing for rationing, so an unresolved conflict points to higher energy prices ahead. Copper holding firm despite oil-driven slowdown and speculator selling defies Rule's expectations, an anomaly he flags without claiming an answer. In the Q&A, Rule calls Cameco's flood a buying opportunity, favors debt-free Uranium Energy, and explains net present value's blind spots on tier-one deposits.

Live Q&A with Rick Rule, hosted by Steve Barton
Key Highlights
detailed- Rule has upgraded Maple Gold from a six to a five on his scale after rethinking its infrastructure position in the Abitibi.
- He once saw it as a me-too deposit, but says much-improved roads, power and access to nearby under-utilized mills now let deposits too small to fund their own mill generate real value by trucking ore to adjacent mills.
- He credits his Boca symposium interview with Ammar Aljundi for prompting him to re-examine how much Abitibi infrastructure improved over the 40 years he has followed the region.
- He says he always liked the deposit's size and potential — it was the lack of infrastructure access that his upgrade removes.
Rule argues resource equities are not excessive despite two years of gains, but liquidity-crisis risk means checking your own exposure. Mining consolidation looks set to continue; Rule favors owning likely takeover beneficiaries because mergers cut overhead and lower capital costs. Rule calls Cameco's flood-driven sell-off a buying opportunity, since a three-month outage barely dents reserves measured in decades. Build NPV (net present value — discounted future cash flow) from measured and indicated resources only, then add back optionality for growth and tail. Development-stage mining assets deserve a basket approach across several names, Rule says, never a single speculative position.

Dave Erfle – Technical Outlook & Investing Insights Around The Recent Pop Higher In The PM Sector
Gold's fundamental drivers remain strong despite geopolitical uncertainty, with central bank buying and sovereign debt supporting the long-term bullish thesis for precious metals. Technical analysis shows GDX and GDXJ breaking above the key 18-week moving average, but a successful retest of this level as support is needed to confirm the next leg higher. Dave Erfle demonstrates his systematic bull market playbook by trimming multi-bagger positions like Arizona Sonoran Copper to redeploy capital into new high-potential junior mining opportunities.
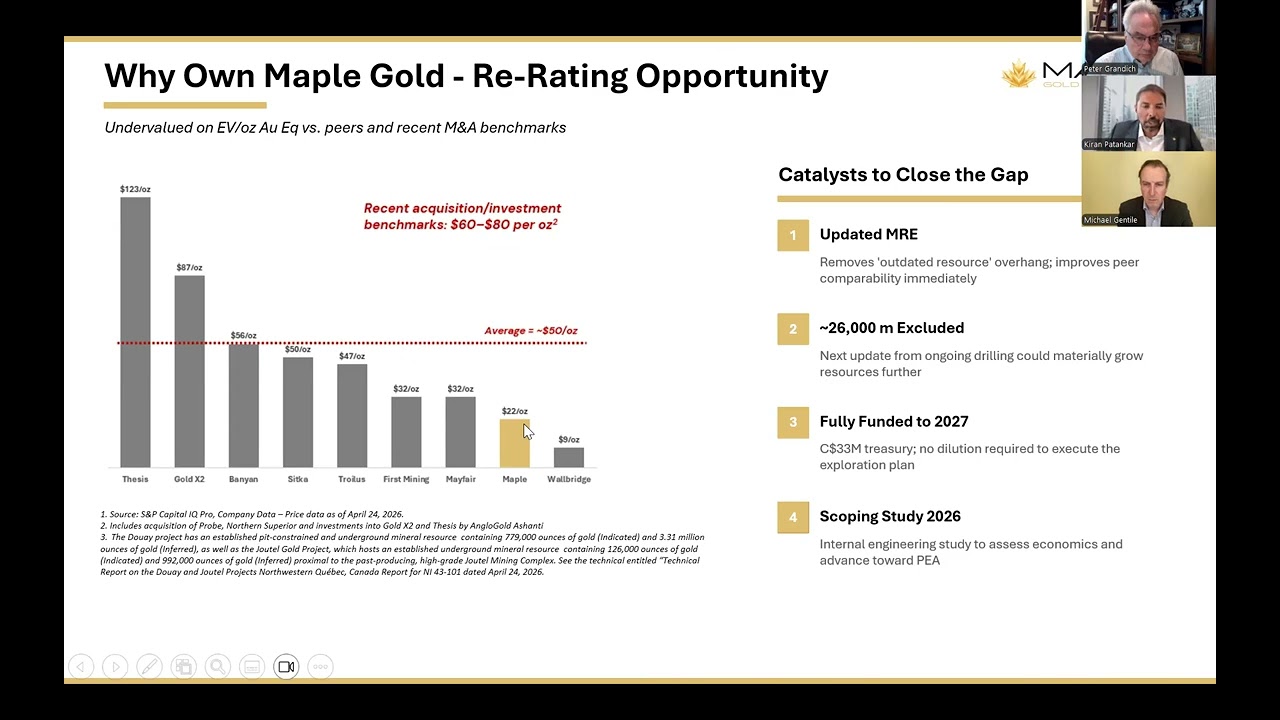
Maple Gold Mines CEO Kiran Patankar Joins Michael Gentile To Discuss Company and Latest News.
Maple Gold Mines CEO Kiran Patankar discusses latest corporate developments and company strategy with host Peter Grandich. Notable investor Michael Gentile shares insights on Maple Gold Mines and his other portfolio holdings including OZ, RDS, and SCRI. Investors gain valuable perspective from a major shareholder's diversified portfolio strategy across multiple junior mining companies.
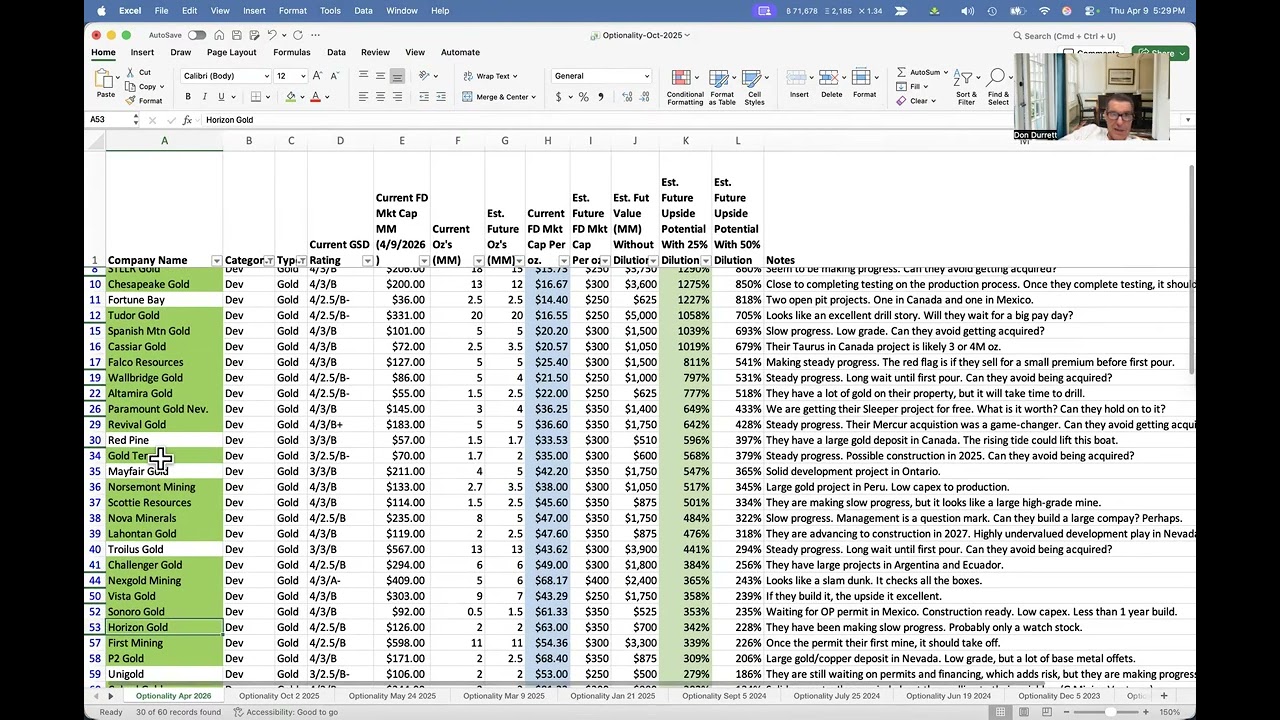
Optionality Update - April 2026
Key Highlights
brief- Durrett says Maple Gold is one of the exploration stocks he owns that has ripped, though it has a little further to go.
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.