Omai Gold Mines Corp logo

Omai Gold Mines Corp

OMG

Omai Gold Mines Corp. explores for and develops base and precious metals. It holds a 100% interest in the Omai prospecting license that covers an area of 4,590 acres, including the past-producing Omai Gold mine located in the Potaro mining district of Guyana, as well as adjoining eastern flats mining permits. The company is based in Toronto, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Omai Gold Mines Corp

Sector

Precious Metal

Founded

January 16, 2012

Reporting Currency

CAD

Contact Phone

416 453 8433

Headquarters Address

82 Richmond Street East , Toronto , ON M5C 1P1 , CA

Identifiers

Commodity Portfolio

AU Gold Primary

Stock Exchanges

OMG TSXV • CAD
OMG:CVE
OMGGF OTC • USD
OMGGF:OTCMKTS

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

Omai Gold Mines – Visual Review & Key Metrics Of The Updated PEA On The Wenot and Gilt Deposits

Omai Gold Mines – Visual Review & Key Metrics Of The Updated PEA On The Wenot and Gilt Deposits

The KE Report
about 1 month ago 32:30

Key Highlights

detailed
  • Ellingham describes the updated PEA (released August 19, about two weeks before the as-of date) as a major step up, with roughly 350,000 oz/year over an 18-year mine life (6.3 Moz total) versus the 2024 starter PEA's 142,000 oz/year.
  • The PEA assumes a 25,000-ton-per-day plant (270% larger than the first estimate), an average grade of 1.35 g/t, and a strip ratio of 5.9 that came in well below analyst expectations of 10, with an NPV of just under $4 billion at a $3,600/oz gold price assumption.
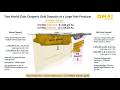
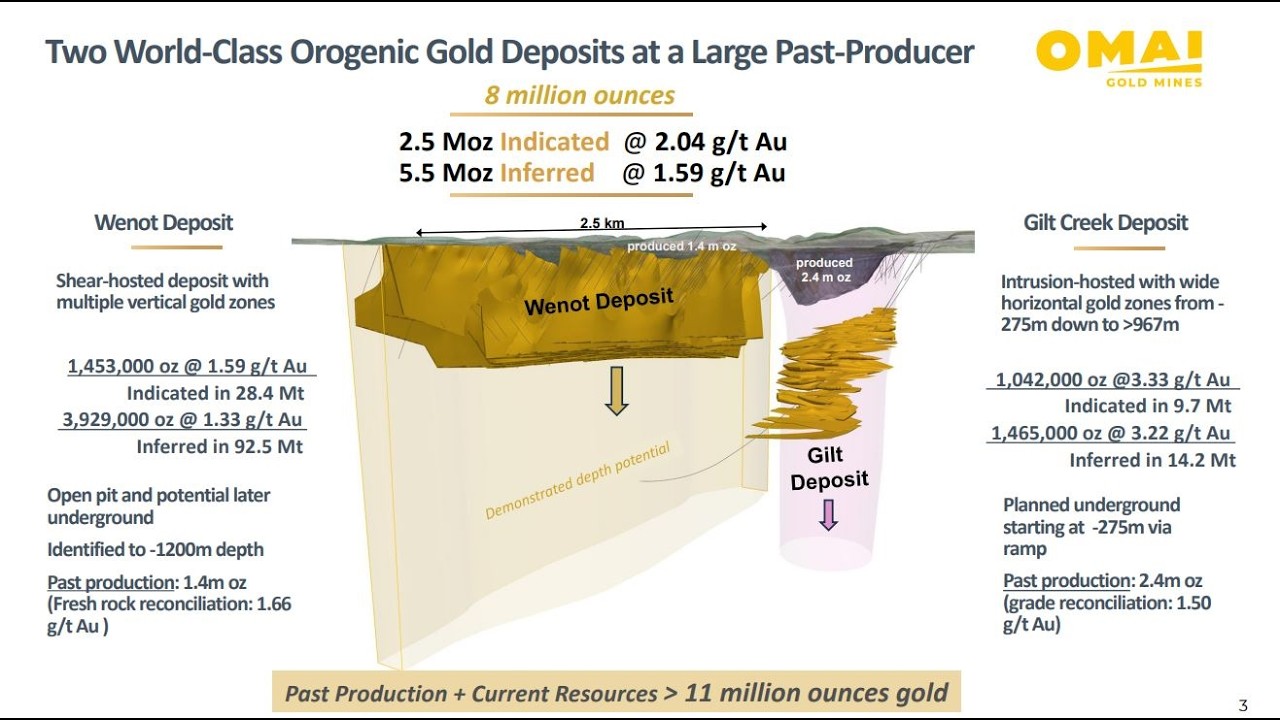
  • Combined Wenot open-pit and Gilt underground resources total about 8 million ounces across M&I and inferred; recent deep drilling extends the Gilt intrusion past 1,200 m vertically and the Wenot geology 700 m below the existing deposit, with the team aiming to push the mine life toward 20 years.
  • Metallurgical test work returned 93-95% recoveries with a 32-hour optimal leach time and no deleterious elements, and feasibility-stage comminution testing is now underway using recently completed wide-diameter core.
  • Ellingham frames Omai as possibly the last large-resource junior in Guyana after recent takeovers of Reunion, G2 Goldfields, and Goldsource; the share price is up 78% YTD against ~10% for the GDXJ.

Omai's updated PEA outlines 6.3 million ounces of payable gold over 18 years, averaging 351k ounces annually at $1,608/oz AISC. The PEA delivers a $4.0 billion after-tax NPV at a 5% discount and a 24% IRR using a $3,600/oz base-case gold price. Targeted drilling of flanking zones pulled the strip ratio down to 5.9, beating analyst expectations of 7.8 to 10. Management is weighing whether to skip a pre-feasibility study and advance straight to a feasibility study on this brownfield past-producer site. Omai stands as the remaining large undeveloped gold project in Guyana after three peer companies were acquired in recent years.

Lab Report | Sep 1 Daily Market Overview & Deep Dive on Radisson, Omai Gold, Cascadia

Lab Report | Sep 1 Daily Market Overview & Deep Dive on Radisson, Omai Gold, Cascadia

CEO.CA
about 1 month ago 38:32

Key Highlights

detailed
  • The host says the PEA supports a $6.2 billion net present value at a 5% discount rate and $4,500 gold, against a C$1.7 billion valuation - trading at about 0.3 of NPV as of the video.
  • The mine plan targets 250,000-300,000 ounces per year, averaging 350,000 ounces over an 18-year life, after an 86% resource increase and with a lower expected strip ratio - the profile the host says major miners want.
  • Hole 193 at the Wanaat deposit cut 11 discrete gold zones, including 5.12 g/t gold over 40.5 meters with 11 g/t over 10.4 meters at 260-290 meters vertical depth.
  • Five rigs are working the 100%-owned Guyana project, with 35,000 of 50,000 meters drilled as of the video, drilling continuing through mid-December 2026, and the Gilt depth test reaching 1,200 meters downhole.
  • The host says a takeover offer would not surprise him at any time, calling a $2.5-3 billion valuation easy to imagine.

Agnico Eagle's $57 million strategic investment gives Radisson a strong vote of confidence, taking the major to roughly 10.45% ownership of the Quebec gold junior. Radisson sits a third of the way up the Lassonde Curve (the value path from discovery to production), where tier-one high-grade peaks reach $1-2 billion. Omai Gold's Guyana project delivered 5.12 grams per ton over 40.5 meters, and an 86% resource increase supports a 350,000-ounce-per-year mine plan. Cascadia hit sulfide mineralization 300 meters beyond its CarMax resource, reinforcing the host's case against rushing resource estimates before defining a system's limits. Rising US debt costs and bond-market stress favor gold and silver, and the host argues generalist investors remain under-exposed to commodities.

A Gold Miner's $4 Billion Study Reads Like a For-Sale Sign

A Gold Miner's $4 Billion Study Reads Like a For-Sale Sign

The Deep Dive
about 2 months ago

Key Highlights

detailed
  • The host argues the PEA reads like a for-sale document for a future builder, not a $1.4B financing plan — analysts closed the call framing OMG as an emerging M&A target for global, intermediate, and large-cap producers.
  • Delivers a $4B after-tax NPV at $3,600 gold (24% IRR, 4.1-year payback), 6.3M payable ounces over 18 years peaking at 436,000 oz/year in year 17; analysts called it a globally relevant long-life production profile.
  • Costs are heavy: $1.4B initial capex, $636M sustaining capex, AISC of $1,600/oz — the highest of the Guyanese projects by a wide margin (vs OCO West ~$1,100, OCO Gani $1,191, Toroparo ~$1,300).
  • Resource confidence is the second weakness: 69% of the 8M ounces is inferred, and management acknowledged they have no conversion statistics yet on what happens to grade.
  • Tailings capacity (90M tons) is short of the 157M-ton mine plan, so the project requires permitting amendments to expand beyond the existing No. 2 facility — a sensitive issue given the site's 1995 tailings failure history.

Omai Gold's updated PEA prices a $4B after-tax NPV at $3,600 gold against a $1.5B market cap, yet AISC climbed 59% in two years to $1,600/oz, capping IRR at 24%. Production scaled to 352,000 oz/year over an 18-year mine life, beating both Stiefel's 268,000 oz Street model and Omai's 300,000 oz guidance. The strip ratio improved to 5.9:1 from 7.8:1 after two years of drilling converted waste into ore at the Wenot super pit. Tailings capacity of 90M tons falls 67M tons short of the 157M-ton mine plan, forcing permitting amendments on the historic OMAI tailings facility. Drift-and-fill is used at the Gilt underground despite geometry that Haywood's Jamie Spratt says favors cheaper bulk long-hole mining.

Omai Gold Mines – Visual Exploration and Development Update At Wenot and Gilt Creek - Upcoming PEA

Omai Gold Mines – Visual Exploration and Development Update At Wenot and Gilt Creek - Upcoming PEA

The KE Report
4 months ago

Key Highlights

detailed
  • The guest expects a combined Preliminary Economic Assessment covering the Wenot open pit and the Gilt Creek underground in roughly four to six weeks from late June 2026, the first study to price both deposits together.
  • She says the resource update published on 14 April 2026, the company's fifth, lifted the combined Wenot and Gilt Creek total to about 8 million ounces in all categories from roughly 6.5 million ounces a year earlier.
  • Five drill rigs have been working since the third week of January 2026 at close to 6,000 metres a month, with infill drilling aimed at converting existing ounces while the resource is still expected to grow.
  • First-phase metallurgical test work returned 93% to 95% gold extraction, and wide-diameter core is being collected for the crushing and grinding work the feasibility study will need.
  • She argues the shares trade at roughly 0.3 times net asset value against about 0.6 for the G2 Goldfields transaction, and that net asset value should rise once the PEA is published.

Omai trades near 0.3 times net asset value while recent Guyana takeovers paid about 0.6 times and $700 an ounce. A Preliminary Economic Assessment (PEA — an early economic study) due within weeks should fold both deposits into one study. Five drills turning roughly 6,000 meters a month keep expanding Wenot, though management says the pit is already big enough. Metallurgical test work returned gold recovery in the 90% range, easing processing risk ahead of the feasibility study. A paved road, nearby grid power options and existing tailings capacity lower both build cost and long-term operating cost.

#104 Digging for Dollars #31 Galantas Gold Raised $100M For A World-Class Restart

#104 Digging for Dollars #31 Galantas Gold Raised $100M For A World-Class Restart

CEO.CA
4 months ago 40:55

Key Highlights

brief
  • The host says he took Omai public and knows Guyana well, which is what drew his attention to the Guyana asset in the stock pitch.
  • He says Omai was his first pitch on the show's Dig This Deal segment last year and that it has done very well for him since.

Galantas closed a $100 million raise, says it is fully funded, and plans to restart Chile's Andacollo gold mine next year for about $60 million. The guest targets 50,000 to 70,000 ounces next year and 90,000 by 2028, with all-in costs near $1,500 an ounce. Royal Gold's stream on Teck takes all gold until 900,000 ounces, which the guest says made the deposit uneconomic to buy. Indiana's 29 identified veins and IOCG (iron-oxide copper-gold) geology leave room for tonnage well beyond today's five million tonnes. Host's junior tier list hands royalty names a B, while 'metals and mining' or 'discovery' names earn an A and an S.

#102 Digging for Dollars #30 Talking our Portfolio and Top Picks

#102 Digging for Dollars #30 Talking our Portfolio and Top Picks

CEO.CA
4 months ago 30:14

Key Highlights

brief
  • One host's top 2025 recommendation is up 200% since it was pitched.
  • He expects Omai will probably be acquired because it is the last great asset in its area.

Early private-market entries into juniors re-rated hard when they listed, beating flat TSX Venture and GDXJ benchmarks at mid-year. Sterling Metals' Batchawana Copper Belt consolidation shows why the hosts buy whole districts early instead of waiting for neighbors to prove up. Galantas Gold's $100 million raise shows how a large, well-supported financing lets a near-term producer reach cash flow without repeated dilution. With no senior tungsten producers, Allied Critical Metals' year-end pilot plant in Portugal offers juniors-only exposure to a quintupled price. Stagnant juniors with strong treasuries and intact teams remain the buys — own value before promotion arrives and prices move.

Live Q&A with Rick Rule

Live Q&A with Rick Rule

Rule Investment Media
5 months ago

Investors should test market capitalization against cash, securities, asset value and realistic economics before speculating in resource equities. Feasibility studies can resolve geology and metallurgy, while financing, processing, offtake and permitting remain decisive development risks. Small metals face sharp supply swings and often lack the scale needed for tier-one mines, increasing commodity and project risk. Royalty companies avoid operating and sustaining-capital bills, while non-operating producers still fund their share of investment. Portfolio concentration should match research capacity; Rick Rule says each holding deserves roughly an hour of review every month.

Omai Gold Mines – Next Batch of High-Grade Gold Drill Results At Wenot,  Upcoming Resource Estimate

Omai Gold Mines – Next Batch of High-Grade Gold Drill Results At Wenot, Upcoming Resource Estimate

The KE Report
7 months ago

Omai Gold Mines reports additional high-grade gold drill results from the Wenot deposit, continuing to demonstrate strong mineralization continuity. Upcoming resource estimate expected to be a significant catalyst for re-rating the company's valuation in near-term. Discussion covers exploration strategy, drilling program expansion plans, and timeline for resource update publication.

Articles

Omai Gold Mines: Heavy Drilling and a $6.2 Billion PEA Build a Majors-Scale Case in Guyana

CEO.CA's Lab Report highlights Omai Gold Mines' 50,000-meter drill program in Guyana: five rigs, high-grade hits including 5.12 grams per tonne gold over 40.5 meters, and a newly announced PEA outlining a 250,000–300,000 ounce-per-year target plus a plan averaging 350,000 ounces over an 18-year life. The host argues the C$1.7 billion market value is about a third of the $6.2 billion NPV he cites.

about 1 month ago
Lab Report | Sep 1 Daily Market Overview & Deep Dive on Radisson, Omai Gold, Cascadia
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord