Seabridge Gold Inc logo

Seabridge Gold Inc

SA

Seabridge Gold Inc., together with its subsidiaries, engages in the acquisition and exploration of gold properties in North America. The company also explores for copper, silver, molybdenum, and rhenium deposits. Its principal projects are the Kerr-Sulphurets-Mitchell property and Iskut project located in British Columbia, Canada; Courageous Lake property situated in Northwest Territories, Canada; Snowstorm project located in the Nevada; and 3 Aces project located in the Yukon Territory. The company was formerly known as Seabridge Resources Inc. and changed its name to Seabridge Gold Inc. in June 2002. Seabridge Gold Inc. was incorporated in 1979 and is headquartered in Toronto, Canada.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Seabridge Gold Inc

Sector

Precious Metal

Founded

April 20, 2004

Employees

12

Reporting Currency

USD

Contact Phone

14163679292

Headquarters Address

106 Front Street East , Toronto , ON M5A 1E1 , CA

Identifiers

CUSIP

811916105

Commodity Portfolio

AU Gold Primary
CU Copper Byproduct
AG Silver Byproduct

Stock Exchanges

SA NYSE • USD
SA:NYSE
SEA TSX • CAD
SEA:TSE
0VGV LSE • GBP
0VGV:LON

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

The World’s Largest Undeveloped Gold Project Nears a Deal | Rudi Fronk - Seabridge Gold

The World’s Largest Undeveloped Gold Project Nears a Deal | Rudi Fronk - Seabridge Gold

The Deep Dive
4 days ago 13:17

Key Highlights

detailed
  • Chair and CEO Rudi Fronk says Seabridge has never been closer to securing its preferred joint venture partner for KSM, with transaction documentation now underway, and as of this interview he hopes to announce the partner and terms before the end of 2026, while stressing that terms matter more than timing.
  • Fronk argues Seabridge is deeply undervalued: at the metal prices discussed he puts KSM's after-tax net present value above US$30 billion against a market cap of about US$3 billion, meaning the company trades at under 10% of NPV while larger gold companies trade around 1.5 times NPV.
  • A US$100 million unsecured, low-interest credit facility from an undisclosed strategic investor is funding this year's early site construction program, which is centered on launching a bankable feasibility study for KSM.
  • Grid power has reached the project: Seabridge has secured an initial 25 megawatts at the energized Treaty Creek terminal, expandable to 245 megawatts for operations, at about 5 cents per kilowatt-hour versus the 15 to 25 cents Fronk says self-generated power would cost.
  • The court-ordered 90-day consultation window brought by a small indigenous group against KSM's 'substantially started' designation has closed, and Fronk expects the government to reconfirm the designation now that project spend has risen from US$444 million at the 2024 designation to roughly US$700 million, keeping the permits valid for the life of the project.

Gold stocks trade near historic discounts to bullion, and Fronk expects gold to reclaim its roughly $5,500 record before year-end. Fronk argues KSM's after-tax net present value (NPV) tops US$30 billion against a $3 billion market cap, an extreme discount. The US$100 million unsecured credit facility from an undisclosed strategic investor funds KSM's advance into a bankable feasibility study. A joint venture with the preferred partner is being documented now; completing it before year-end is the central milestone. Grid hydropower at about 5 cents per kilowatt-hour and finished road access de-risk KSM ahead of its feasibility launch.

They’re Uncovering an Entire DISTRICT OF GOLD | Michael Bennett - Altamira Gold

They’re Uncovering an Entire DISTRICT OF GOLD | Michael Bennett - Altamira Gold

The Deep Dive
15 days ago 7:20

Key Highlights

brief
  • The host cites Rudy Frong of Seabridge as an admirer of exploration metrics such as ounces added per meter drilled and capital spent per ounce, using them to frame Altamira's Maria Benito growth as efficient.

Altamira Gold added over 600,000 ounces with just 12 drill holes, lifting Maria Bonita (its main deposit) from 720,000 to over 1.3 million ounces. The guest argues today's roughly $4,300 gold price makes low-grade deposits economic; his resource was viable at $1,500 gold in 2019. A new porphyry (a large, low-grade intrusion-hosted gold system) called Maria Bonita West was found at depth, and its first drill hole is now collared. Altamira frames Cajueiro as a multi-porphyry district, targeting over three million ounces, with new targets Novosonios and Tavares North in the pipeline. The Deep Dive discloses Altamira is a paying client of its parent, Canacom Group, so treat this coverage as compensated promotion.

Barrick–Newmont Nevada JV, Permitting Risk, Royalties, and Mine Financing | Analyst Joe Mazumdar

Barrick–Newmont Nevada JV, Permitting Risk, Royalties, and Mine Financing | Analyst Joe Mazumdar

MiningStockEducation.com
28 days ago 51:52

Key Highlights

detailed
  • The guest calls the BC court ruling — that a First Nations group was not fully consulted on KSM's substantially-started permit — a clear negative for Seabridge: there is a 90-day window with an unknown outcome, and with about $1 billion already spent the company will find it hard to land the partner it is looking for.
  • Scale drives the dispute, per the guest: KSM is a 170,000 tonne-per-day, $6.4 billion project with 7.3 billion pounds of copper, 47 million ounces of gold and twin 23-kilometre tunnels — big enough that groups downstream or on the fringe of the footprint feel affected though they were never consulted.
  • The guest argues the sector needs a consultation buffer zone beyond the formal footprint, notes UNDRIP has given First Nations a bigger say, and flags the precedent of one nation lobbying on behalf of a smaller nation the court found was ignored.
  • Beyond Seabridge itself, the guest says the ruling looks bad for BC and Canada because the company did the substantial-start work in good faith, and he compares the accountability question to Mount Polley, where the company ultimately bore the worst reputational and financial damage.

Barrick is selling Fourmile at a steep discount, but access to permitted autoclave (pressure oxidation) capacity via Goldrush justifies it. Seabridge's KSM court setback shows Indigenous consultation now extends beyond a project's footprint, raising permitting risk across British Columbia. Major gold producers returned roughly 30% of first-half 2026 revenue to shareholders, with buybacks outpacing dividends and the top five dominating. Judge management on per-share value: grow assets without growing the share count, and favor teams that raise capital at rising prices. Coffee's upfront capital quadrupled in a decade, reinforcing the case for hunting fatal flaws early — cutoff grades, jurisdictions, and site visits.

Margin of Safety, Mass Psychology, IPOs & Jurisdictional Risks: Junior Mining Insights-Powers & Leni

Margin of Safety, Mass Psychology, IPOs & Jurisdictional Risks: Junior Mining Insights-Powers & Leni

MiningStockEducation.com
about 2 months ago

Key Highlights

detailed
  • Seabridge's KSM is at the center of a major jurisdictional shock: First Nations have publicly pulled their support for the project's development, and Brian argues the market is likely reading this as a business-deal negotiation tactic rather than a genuine walk-away
  • Bill notes the project is massive and located in Northern BC, and that CEO Rudy Frank has been open about being in talks with a major mining company to acquire it as KSM approaches the final investment decision
  • Brian frames the First Nations move as a leverage play tied to the BC government's broader negotiations, noting KSM-related projects sit on the province's short list of top-four projects slated for development
  • Bill questions whether the balance of power has tilted too far, citing that Seabridge's substantially started permit means huge sunk costs and an issued permit can still be undercut by a group changing its mind after the fact

Powers argues margin of safety in early-stage juniors lives in the management team — a project can stall, change hands, and dilute holders before advancing. Both warn Canadian IPO seed and pre-IPO holders often dump at listing — favor fair pricing and avoid groups known for promotional IPO spend. Both argue, citing Neil Atchied, that a well-marketed lesser project beats an undermarketed great one — investors buy a public business, not a rock. Both frame the Seabridge KSM First Nations pullback as a business negotiation rather than a fatal blow — permits do not lock in a project. Leni urges retail to study critical-metals metallurgy — graphite and rare-earth projects live or die on whether end users can actually use the output.

Live Q&A with Rick Rule and Albert Lu

Live Q&A with Rick Rule and Albert Lu

Rule Investment Media
about 2 months ago

Key Highlights

brief
  • Rule says Seabridge's KSM project now faces more challenges after a British Columbia judge ruled the Environmental Assessment Office failed in its 'deep consultation' duty with the small Schukleblok Shah band (around 62 people), which is being backed by the adjacent Gixxan band.
  • He calls the ruling political, arguing the Schukleblok Shah likely compared the benefit package the Tahltan extracted from Skeena and decided they could do better at KSM; First Nations make up roughly 80% of voters in that BC riding.

Reading offering documents and 10-Ks is essential; Rick Rule uses a condo contract story to illustrate capital stack diligence. Rick rates First Mining Gold's Spring Pole a 6, and Agnico Eagle's Radisson stake validates Abitibi infrastructure economics. Lotus Resources' Chialecra uranium deposit isn't buildable at $80/lb given East African political and economic challenges, Rick says. Inversion technique: avoiding Doug Casey's 'gotta hunch, bet a bunch' is the surest way to fail in natural resources. In deleveraging equity plays, Rick waits for net present value of assets to exceed enterprise value before buying.

Rick Rule: Copper Has WAY More Potential Than Gold

Rick Rule: Copper Has WAY More Potential Than Gold

VRIC Media
2 months ago

Key Highlights

detailed
  • Rick discloses he owns Seabridge (transcribed in the audio as 'C-Bridge') and is personally friendly with CEO Rudy Frank.
  • Rick argues Seabridge may be the largest undeveloped gold project in the world and would solve an acquirer's depletion problem for a decade, but warns of extraordinary upfront capital intensity and a feasibility study that likely needs updating for construction cost inflation.
  • Rick says Seabridge is down to a single bidder out of the 12-13 companies that had signed confidentiality agreements, and argues that at roughly $4,400 gold this gives the remaining bidder the leverage rather than Rudy Frank, who would have had the leverage at $5,500 gold.
  • Rick suggests the acquirer can now afford to let the Tudor Gold litigation resolve in court rather than pay up to extinguish it.

Major copper producers need roughly $250 billion just to hold production steady — and they don't have the capital, opening a financing boom for streamers. Wheaton Precious and Franco-Nevada could be the biggest winners — silver byproducts from copper mines earn much higher multiples inside a streamer. Rule is rotating out of Franco, Wheaton, and Agnico into smaller, more speculative juniors to front-run the coming M&A wave. Most majors face a five-year depletion problem — only Agnico and Goldfield, Rule says, have near-term production covered. A red flag in royalty M&A: rapid capital deployment without a structural edge usually signals overpayment, not bargain hunting.

'I Still Like SILVER' - $200 a 'When, Not If' Question: Gianni Kovacevic

'I Still Like SILVER' - $200 a 'When, Not If' Question: Gianni Kovacevic

Commodity Culture
2 months ago

Key Highlights

brief
  • Kovacevic groups Seabridge with Snowline and Aben Gold as the kind of gold developers and small-cap explorers he follows alongside high-quality producers like Agnico Eagle.

Kovacevic treats $200 silver as a 'when, not if' call, anchored to a 40:1 silver-to-gold ratio off an $8,000 gold target. Silver producers trade like silver is $40 even at $60 metal, opening a re-rating window for major silver miners. Agnico Eagle at $200 is his highest-conviction gold pick, with cash flow strong enough to survive a $500 gold pullback. Lithium is the most mispriced sector globally; DLE (Direct Lithium Extraction) will feed 20-30% of a market that triples by 2030. Copper sits in a $5.50-$7 plateau, so he prefers junior drill plays where one discovery hole can drive multi-bagger returns.

5.65 g/t Gold at Surface: GoldInxs Prepares to Drill at Fishpot Project in BC

5.65 g/t Gold at Surface: GoldInxs Prepares to Drill at Fishpot Project in BC

CEO.CA
3 months ago 5:06

Key Highlights

brief
  • Seabridge Gold's KSM is named in the same Golden Triangle discovery list, cited by the guest as precedent for the district rather than as a current producing status.

A maiden 2,000-metre drill program at GoldInxs' Fishpot project is the newly listed explorer's next major test. Airborne geophysics, geological mapping and geochemical sampling have each flagged the same drill targets at Fishpot. Surface rock samples returned up to 5.6 g/t gold, 11.3 g/t silver and copper mineralization ahead of any drilling. The guest calls Fishpot a large epithermal system, citing similar volcanic rocks and geochemistry to Artemis Gold's Blackwater mine, 65 km away. Millar adds Golden Triangle exposure and diversification in a district that has produced Brucejack, SK Creek and KSM.

Kingfisher Metals–Barrick Mining Comes In As Strategic Shareholder  For Exploration Upside At Hwy 37

Kingfisher Metals–Barrick Mining Comes In As Strategic Shareholder For Exploration Upside At Hwy 37

The KE Report
3 months ago

Key Highlights

brief
  • Perry cites Seabridge's KSM project in the Golden Triangle as the largest undeveloped gold deposit on earth, and notes it sits nearby.
  • He says Kingfisher has dated its rocks to the same age as KSM and that the company's chief geologist did her master's work at KSM, using both to argue the ground compares with the district's best-known deposit.

Barrick Mining will hold 9.9% of Kingfisher Metals after a C$20.9 million placement priced at C$1.35 per unit. At least 80% of the proceeds fund exploration and development at Kingfisher's Hwy 37 project in BC's Golden Triangle. The guest says the placement priced at more than double the March BMO financing, four or five months earlier. Pro forma treasury reaches roughly C$47 million, funding a fully paid 15,000-metre drill program with three rigs turning. Barrick gets a joint technical committee and full access to its technical staff, but the deal bars a project-level joint venture.

$6,500 Gold by 2027? | Rudi Fronk - Seabridge Gold

$6,500 Gold by 2027? | Rudi Fronk - Seabridge Gold

The Deep Dive
3 months ago

Key Highlights

detailed
  • Fronk says the KSM joint-venture process is down to a single preferred partner and that he expects naming it, with agreed structure and terms, to be the biggest rerating event in Seabridge's share price.
  • A recent sensitivity at $4,400 gold and about $575 copper puts KSM's after-tax NPV at $33 billion, versus $8 billion and a 16% IRR in the 2022 study at $1,740 gold and $353 copper, with the IRR more than doubling to 34%.
  • On June 8, 2026 a judge upheld the substantially started designation as reasonable but ordered renewed consultation with the small First Nation behind the first petition within a 90-day window, and Fronk expects the government to confirm its 2024 decision.
  • KSM's economics worked even at $1,700 gold, and infrastructure has improved sharply since the 2000 purchase: a highway beside the project, over $700 million of government hydropower spending on the Northwest Transmission Line, 245 megawatts of secured power, and road access to two ports.
  • The recently closed Valor Gold spinout moves Courageous Lake, held since 2002 and described by the host as one of Canada's largest gold deposits outside KSM, into a separate public vehicle to win the share-price recognition management says it was not getting.

Seabridge Gold chair and CEO Rudi Fronk calls gold's pullback temporary war-driven reserve selling, forecasting $5,500 gold by end-2026 and $6,500 in 2027. The guest says KSM worked at $1,700 gold, and new highway, hydropower, and port access transformed the once-remote project's logistics. Naming the preferred major partner is the anticipated rerating trigger: the joint-venture process is down to one company from three finalists. Courts upheld KSM's substantially started designation - keeping permits valid for the project's life - but ordered more consultation with a small First Nation. The Valor Gold spinout separates Courageous Lake, and a $4,400-gold scenario lifts KSM's after-tax NPV (net present value) to $33 billion.

This Could Be Silver’s Next Monster Mine | AbraSilver Diablillos DFS

This Could Be Silver’s Next Monster Mine | AbraSilver Diablillos DFS

The Deep Dive
3 months ago

Key Highlights

brief
  • In the speaker's five-developer peer comparison, Seabridge sits at 0.44 times EV-to-NAV, the same figure he gives as the group's pure average and uses as the reference point against AbraSilver's 0.49 times.

Junior miners cannot choose when good news lands, and this feasibility study hit on a day silver fell more than 5%. Phase one is a 25-year open pit processing 9,000 tonnes of ore a day, averaging 10.3 million silver-equivalent ounces annually. The first five years average 20.3 million silver-equivalent ounces, so the profile is heavily front-loaded rather than level. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) of $19.98 and $722 million of capital look readily financeable. Senior producers trade above one times NAV while developers sit at a discount; the host puts this project near the peer average.

Summit Royalties – Acquisition Of Star Royalties Is Complete, Bringing In A Significant Gold Stream

Summit Royalties – Acquisition Of Star Royalties Is Complete, Bringing In A Significant Gold Stream

The KE Report
3 months ago

Summit Royalties closed its acquisition of Star Royalties, adding a 4% gold stream on the Copperstone project in Arizona to a 48-asset portfolio. A stream is an upfront payment plus an ongoing one (here 25% of spot for 4% of gold), giving Summit growth it did not fund. Mining Americas' new PFS (Pre-Feasibility Study — the detailed economics test before a build decision) supports construction, with first gold targeted by mid-2027. A royalty on Jaguar Mining's Pitangui project should start construction this year and ramp up in 2027, pairing with Copperstone for revenue growth. The guest argues Summit trades near 0.65 of net asset value, and closing that discount through research coverage would lower its cost of capital.

Live Q&A with Rick Rule and Albert Lu

Live Q&A with Rick Rule and Albert Lu

Rule Investment Media
3 months ago

Key Highlights

brief
  • Rick expects a possible Seabridge joint-venture announcement imminently — he has promised CEO Rudy Fronk a bourbon, a case on behalf of the classroom, if it lands before next week's symposium.

Falling share prices against rising values signal a bargain season; Rule urges investors to pre-build tiered shopping lists before forced selling creates bargains. Mining costs are inflating: consumables rise near 10% compounded versus stated CPI, so AISC (All-In Sustaining Cost — full production cost per ounce) climbs industry-wide. Rule favors uranium's remaining upside after the hated-to-not-hated move, sees a multi-year US natural gas upcycle, and still expects five-to-ten-year metals bull markets. Rule backs B2Gold and OceanaGold at low cashflow multiples, seeing resolved construction problems and quiet Mali diplomacy as mispriced strengths supporting further gold-sector M&A. Ivanhoe Mines offers compelling value for DRC-risk takers as Kamoa-Kakula repairs, a new smelter, and two more tier-one deposits reshape 2027 cashflow.

Teuton Resources Stock Paying Dividends in Shares

Teuton Resources Stock Paying Dividends in Shares

The Gold Bull
4 months ago

Key Highlights

brief
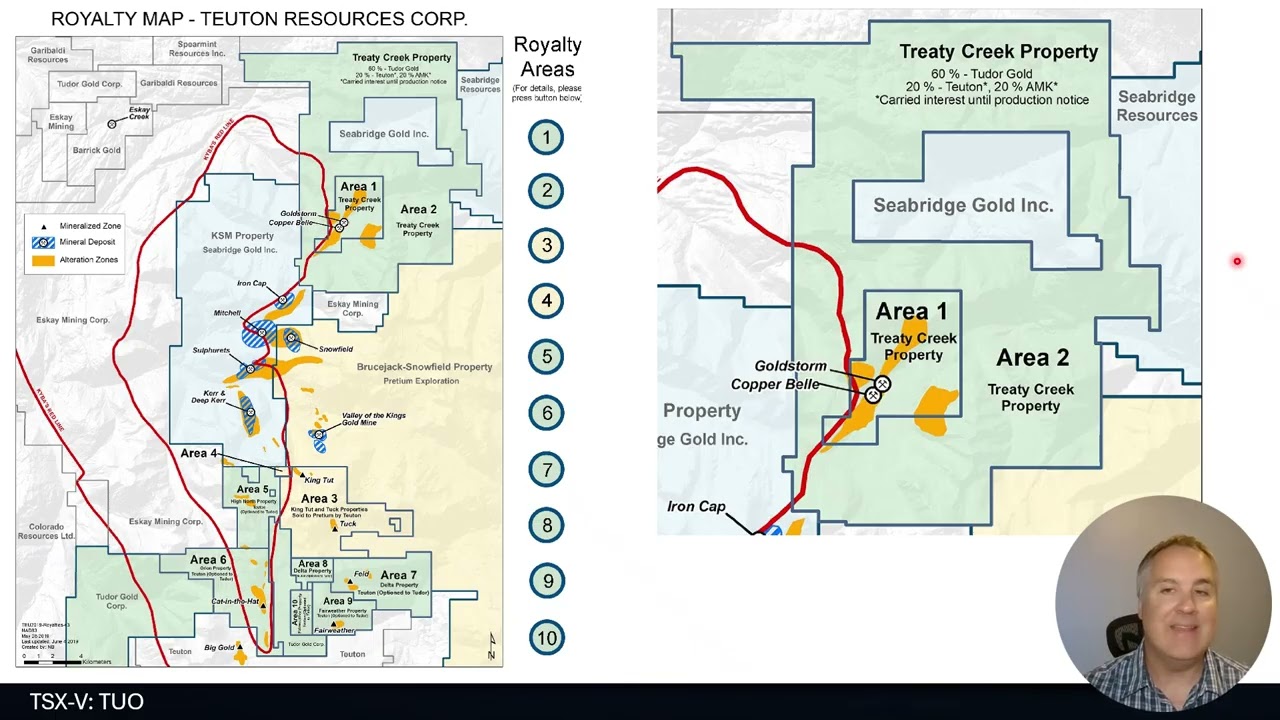
  • The presenter cites Seabridge Gold's nearby KSM project as hosting 180 million ounces of gold, which he calls the biggest undeveloped gold project in the world.

Teuton Resources owns a 20% stake plus a 0.98% NSR (net smelter return — a royalty on production revenue) in Goldstorm, a 29-million-ounce gold deposit. A free carry means partner Tudor Gold funds all Treaty Creek spending until a production decision, so Teuton grows its flagship without dilution. A proposed double spinout gives shareholders free shares in two new companies holding the royalty and property portfolio, with Treaty Creek kept in the parent. The host argues the current price and roughly $130 million market cap do not reflect the value and potential of Teuton's asset portfolio. The Golden Triangle's scale anchors the case: Seabridge Gold's KSM project nearby hosts 180 million ounces, the world's biggest undeveloped gold project.

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton

Rule Investment Media
5 months ago

Key Highlights

detailed
  • Fronk says Seabridge has narrowed potential joint venture partners for KSM to a single preferred candidate and is aligning the final bankable feasibility design with that company first, so the partner does not later reject the study's design choices.
  • KSM is described as the largest undeveloped gold project in the world by reserves and resources and the second-largest undeveloped copper project if gold is set aside; Seabridge has spent over C$1 billion since 2006, received environmental approval in 2014 and started on-site construction, with a 33-year initial mine life of just over 1 million ounces of gold a year and life-of-mine cost of production under $500 per ounce after by-product credits.
  • At $4,400 gold Fronk puts KSM's after-tax NPV above US$35 billion, against roughly US$8 billion at the 2022 pre-feasibility prices of $1,740 gold and $3.53 copper; payback stays near two years even if capital cost rises to $8 billion, and the first five years of operations generate about US$35 billion of combined EBITDA.
  • The Courageous Lake spin-out, to be named Valor Gold, was about 99.9% approved by shareholders as of the May 2026 discussion and still needs court sign-off before shares are expected in accounts around June 3, 2026; Fronk says its NPV has moved from about $0.5 billion in a 2024 study at $1,850 gold to north of $3 billion, which he frames as $5 to $10 per Seabridge share if the market picks it up.
  • The main open risks are permitting and balance sheet: the M2-4-5 amendment needed for the full haulage tunnel is held up pending the Tudor dispute, a neighbouring First Nation of roughly 50 band members has a judicial review pending over KSM's substantially started designation with a fallback application ready on spend that has risen from $440 million to about $700 million, and holding costs run near C$40 million a year against roughly $130 million in treasury.

Seabridge's KSM is now the world's largest undeveloped gold project by reserves and resources, and second-largest for copper. Fronk argues capital efficiency is the real draw: at current metal prices after-tax NPV reaches $35 billion against a $6.4 billion build. Over $1 billion of roads, camps and grid tie-in is already built, so an incoming partner inherits spending rather than starting from zero. The remaining risk is a tunnel dispute with Tudor; both sides want a negotiated fix because neither wants a court trial. Nearly half of $750 million in on-site construction spending already flows to First Nations companies under impact benefit agreements.

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton 📱

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton 📱

Rule Investment Media
5 months ago

Key Highlights

detailed
  • The guest says KSM's after-tax NPV works out to about $35 billion at $4,400 gold, a price he had not yet run against $6 copper, versus a 2022 capital estimate of $6.4 billion, and that the project still pays back in roughly two years even if capital climbs toward $8 billion.
  • He says permits were secured for the life of the project: environmental approvals received in 2014 were due to expire in July 2026, but after spending about C$700 to C$750 million on site-specific construction the company won 'substantially started' designation in July 2024, so a new partner would not have to restart the assessment, and that designation is now under judicial review.
  • He says joint venture talks have narrowed from seven or eight candidates to one preferred partner, and that only about seven companies globally have the technical, financial and social standing he would partner with on a project this size; he wants that partner aligned on the bankable feasibility design before the study starts, and says the company held about $130 million against roughly C$40 million a year of holding costs.
  • He notes the 2022 study restricts mining to 2.3 billion tons of the project's 15 billion tons of economic resources, giving an initial 33-year life at just over one million ounces of gold and close to 200 million pounds of copper a year plus about two million ounces of silver, with life-of-mine cost of production under $500 an ounce after copper, silver and molybdenum by-product credits.
  • He says the Courageous Lake spinout is expected to reach shareholders around June 3, 2026, shortly after the as-of date, with about 99.9 percent of votes cast in favour; he puts that project's NPV at more than $3 billion at current gold prices, roughly Seabridge's own market cap, and frames it as $5 to $10 of value per Seabridge share.

KSM is described as the world's largest undeveloped gold project by reserves and resources, and its second largest for copper. At $4,400 gold, net present value (what future cash flow is worth today) hits $35 billion after tax, with payback under two years. Life-of-mine production cost sits below $500 an ounce once copper, silver and molybdenum are credited against the gold. The main blocker is a haulage tunnel dispute with a neighbouring project; a permit amendment waits on that company's mine plan. Only about seven companies worldwide have the technical, financial and social capacity to partner on a project this size.

Kody Penner, VP, Corporate Development of Nations Royalty |Rule Symposium 2026: Rick Rule interviews

Kody Penner, VP, Corporate Development of Nations Royalty |Rule Symposium 2026: Rick Rule interviews

Rule Investment Media
5 months ago

Key Highlights

detailed
  • The guest calls the royalty on Seabridge's KSM deposit the most valuable holding in Nations Royalty and the biggest part of its net asset value, describing KSM as the world's largest permitted but undeveloped copper-gold project, with about 47 million ounces of gold and 7.5 billion pounds of copper in reserve.
  • He argues Seabridge and Nations Royalty are effectively the same bet, saying a share in Nations Royalty can be thought of as a bit of a call option on Seabridge because the royalty moves with any progress at KSM.
  • He says the royalty company is closely aligned with Seabridge's management and expects any material partnership or development news at KSM during 2026 to lift Nations Royalty sharply.
  • He frames KSM as the holding that gives investors a route to a top-tier asset through a roughly $150 million market cap, cheaper than owning Seabridge directly.

Impact benefit agreements already give indigenous groups royalties on most major Canadian mines, signed over the past 30 to 40 years. Nations Royalty, 72% owned by the Nisga'a Nation, consolidates those royalty streams and trades publicly at roughly $150 million market cap. Its biggest prize is a royalty on Seabridge's KSM deposit, which holds 47 million gold ounces and 7.5 billion pounds of copper in reserve. Cash flow is uneven: Bruce Jack payments keep rising, but Cambria's Premier and Red Mountain mines went into care and maintenance. The founding nation holds 72% and management 1.5%; the guest argues that thin float could sharply move the stock on any new deal.

Live Q&A with Rick Rule, hosted by Steve Barton 📱

Live Q&A with Rick Rule, hosted by Steve Barton 📱

Rule Investment Media
5 months ago

Key Highlights

detailed
  • Rick thinks it is highly likely that the Tudor legal action is holding up Seabridge's joint venture, since no potential acquirer wants to inherit a lawsuit.
  • He says Seabridge is in the mid-to-final stage of negotiations with a preferred JV partner, whom he surmises - without knowing - is Newmont based on its free cash flow and investment in the region.
  • He doubts any JV announcement comes before settlement or adjudication of the Tudor dispute.
  • He rates Seabridge a five on his scale.

Rick Rule argues resource equities remain reasonably priced after two years of gains, but a 2008-style liquidity crisis could force overexposed investors to sell. Consolidation keeps rewarding shareholders: mergers cut duplicated overhead, and larger miners gain index inclusion, passive buying, and a lower cost of capital. Oil's move from $65 to $105 is anticipatory pricing for rationing, so an unresolved conflict points to higher energy prices ahead. Copper holding firm despite oil-driven slowdown and speculator selling defies Rule's expectations, an anomaly he flags without claiming an answer. In the Q&A, Rule calls Cameco's flood a buying opportunity, favors debt-free Uranium Energy, and explains net present value's blind spots on tier-one deposits.

Live Q&A with Rick Rule, hosted by Steve Barton

Live Q&A with Rick Rule, hosted by Steve Barton

Rule Investment Media
5 months ago

Key Highlights

detailed
  • Rule rates Seabridge a five and says today's gold price works in the stock's favor.
  • He thinks it is highly likely the Tudor legal action is holding up a joint venture, since no partner wants to inherit a lawsuit.
  • He says Seabridge is in the mid-to-final stage of negotiations with a preferred joint-venture partner, and he surmises it may be Newmont given its free cash flow and investment in the region.
  • He expects no announcement before the Tudor dispute is settled or adjudicated, and says Rudy will not reveal the partner's name.

Rule argues resource equities are not excessive despite two years of gains, but liquidity-crisis risk means checking your own exposure. Mining consolidation looks set to continue; Rule favors owning likely takeover beneficiaries because mergers cut overhead and lower capital costs. Rule calls Cameco's flood-driven sell-off a buying opportunity, since a three-month outage barely dents reserves measured in decades. Build NPV (net present value — discounted future cash flow) from measured and indicated resources only, then add back optionality for growth and tail. Development-stage mining assets deserve a basket approach across several names, Rule says, never a single speculative position.

Rudi P Fronk, Chairman and CEO of Seabridge Gold | Rule Symposium 2026: Rick Rule interviews

Rudi P Fronk, Chairman and CEO of Seabridge Gold | Rule Symposium 2026: Rick Rule interviews

Rule Investment Media
5 months ago

Key Highlights

detailed
  • Fronk argues the company trades at roughly 10% of NAV: about a $3 billion U.S. market cap versus a stated after-tax NPV above $30 billion for KSM at current metal prices — the central value-versus-valuation gap of the interview.
  • KSM is described as the largest undeveloped gold and copper project in the world by reserves and resources, with measured and indicated resources of just over 100 million ounces of gold and about 20 billion pounds of copper, and total resources of 180 million ounces of gold and about 47 billion pounds of copper across five 43-101 deposits.
  • The 2022 KSM feasibility study assumed about $6.4 billion of initial capital and, at $1,740 gold and $3.53 copper, produced an NPV of roughly $8 billion; Fronk states that at $4,400 gold and $5 copper the NPV jumps to above $30 billion, which he says more than absorbs likely capex escalation.
  • KSM joint venture process: Seabridge hired RBC Capital Markets about three years before the interview, narrowed a field of 7–8 companies to three finalists after achieving 'substantially started' status in July 2024, and is now in agreement finalization with a single preferred partner.
  • Beyond KSM, Fronk highlights a May 22, 2026 shareholder vote to spin out Courageous Lake — 15 million ounces of gold with an NAV above $3 billion at current prices — into a new public company called Valor Gold, plus the Bronson Corridor project (formerly Iskut), where the maiden Snip North resource adds roughly 9.2 million ounces of gold and 1 billion pounds of copper alongside the existing Bronson Slope deposit of about 5.5 million ounces of gold and 1 billion pounds of copper.

Seabridge's $3B market cap trades near 10% of NAV while its KSM project shows an after-tax NPV above $30B at current metal prices. Fronk argues KSM is the largest undeveloped gold-copper project globally — 180M oz gold and 47B lb copper across five deposits. Fronk says a KSM joint venture partner is close: RBC narrowed 7-8 candidates to three, and the preferred partner is now in final talks. Seabridge plans a May 22nd shareholder vote to spin out Courageous Lake into a new public company called Valor Gold. Rule frames KSM's $30B after-tax NPV against $8B upfront capex as a clear pass on the 1:2 capex-to-NPV test.

Articles

Seabridge Gold has never been closer to a KSM joint venture, says CEO Rudi Fronk

Seabridge Gold CEO Rudi Fronk says the company has never been closer to naming its preferred joint venture partner for KSM, with transaction documentation underway and an announcement hoped for before year-end. He cites an after-tax NPV above US$30 billion at KSM against a roughly $3 billion market cap, newly connected grid power, and a feasibility study ready to launch.

4 days ago
The World’s Largest Undeveloped Gold Project Nears a Deal | Rudi Fronk - Seabridge Gold
Read article
Seabridge at 10% of NAV: A KSM Joint Venture, a Courageous Lake Spin-Out, and a New Discovery

Seabridge Chairman Rudi Fronk says KSM, which he calls the largest undeveloped gold-copper project by reserves and resources, shows an after-tax NPV above $30 billion at current metal prices against a roughly $3 billion market cap. A joint venture partner is in final discussions and a Courageous Lake spin-out vote is set for May 22.

5 months ago
Rudi P Fronk, Chairman and CEO of Seabridge Gold | Rule Symposium 2026: Rick Rule interviews
Read article

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord