Skeena Resources Limited
SKESkeena Resources Limited explores and develops mineral properties in Canada. The company explores for gold, silver, copper, and other precious metal deposits. It holds 100% interests in the Snip gold mine comprising one mining lease and four mineral tenures that covers an area of approximately 1,932 hectares; and the Eskay Creek gold mine that consists of eight mineral leases, two surface leases, and various unpatented mining claims, which total 6,151 hectares located in British Columbia, Canada. The company was formerly known as Prolific Resources Ltd. and changed its name to Skeena Resources Limited in June 1990. Skeena Resources Limited was incorporated in 1979 and is headquartered in Vancouver, Canada.
Score
—Data Quality
Market Cap
N/A
Total valuation
Stock Price
N/A
Latest close
Free Cash Flow
N/A
Annual
Financial Position
N/A
Cash position
PEG Ratio
ⓘN/A
P/E ÷ growth
Analysis
Subscribe to see the AI Analysis
Score breakdown, criteria, red flags, bull/base/bear scenarios.
SubscribeFinancials
Asset Pipeline
Subscribe to see the Asset Pipeline
Jurisdiction exposure, project portfolio, cost structure.
SubscribeInformation
Key Information
Legal Entity
Skeena Resources Limited
Sector
Precious Metal
Founded
February 5, 2002
Employees
83
Reporting Currency
USD
Contact Phone
604 684 8725
Website
www.skeenaresources.comHeadquarters Address
1021 West Hastings Street , Vancouver , BC V6E 0C3 , CA
Identifiers
Commodity Portfolio
Organization
Chart
Interactive chart powered by TradingView. Use the chart tools to analyze price trends.
Videos

Skyline Builders Group ($KAZR): Developing a Large-Scale Tungsten Project in Kazakhstan
Key Highlights
brief- John says Skeena is expected to enter construction this year (2026) or in early 2027, placing it on his near-term-producer list.
Skyline Builders Group (KAZR) plans a 50+ year tungsten mine in Kazakhstan targeting 2030 production, with backing from US EXIM and DFC. The project targets 12,000 metric tons of tungsten annually — roughly 15% of current global supply — at cash costs under $100 per MTU. China, Russia, and North Korea control about 87% of global tungsten, creating structural demand for non-Chinese sources used in defense and semiconductors. Management expects US offtake agreements and debt to cover the ~$1.1 billion capex without shareholder dilution, with an MOU already in place. Rotterdam tungsten prices trade at a premium to Chinese prices, signaling Chinese export restrictions rather than a balanced soft market.

Willem Middelkoop: The Next Financial Crisis, 'Perfect Storm' For Commodities & Mining Discoveries
Key Highlights
brief- The guest calls Skeena a 'great example' in his starting-producer basket, a category he expects to see 100-200% re-rates as new mines come online.
Weimar lite is already underway as foreign holders have dropped below 30% of US Treasuries and the Fed has absorbed $330B in a year. Central banks have bought around 1,000 tonnes of gold per year for five straight years -- about a third of global mine output. Gold is being reintroduced into the monetary system without any formal conference, as central banks now hold more gold than Treasuries. Gold producers print record free cash flow at PE ratios of 10-11, roughly a tenth of Magnificent Seven valuations. Discovery investors hold at least 1% stakes in tier-one deposits, scaling back after runs but never selling through production.
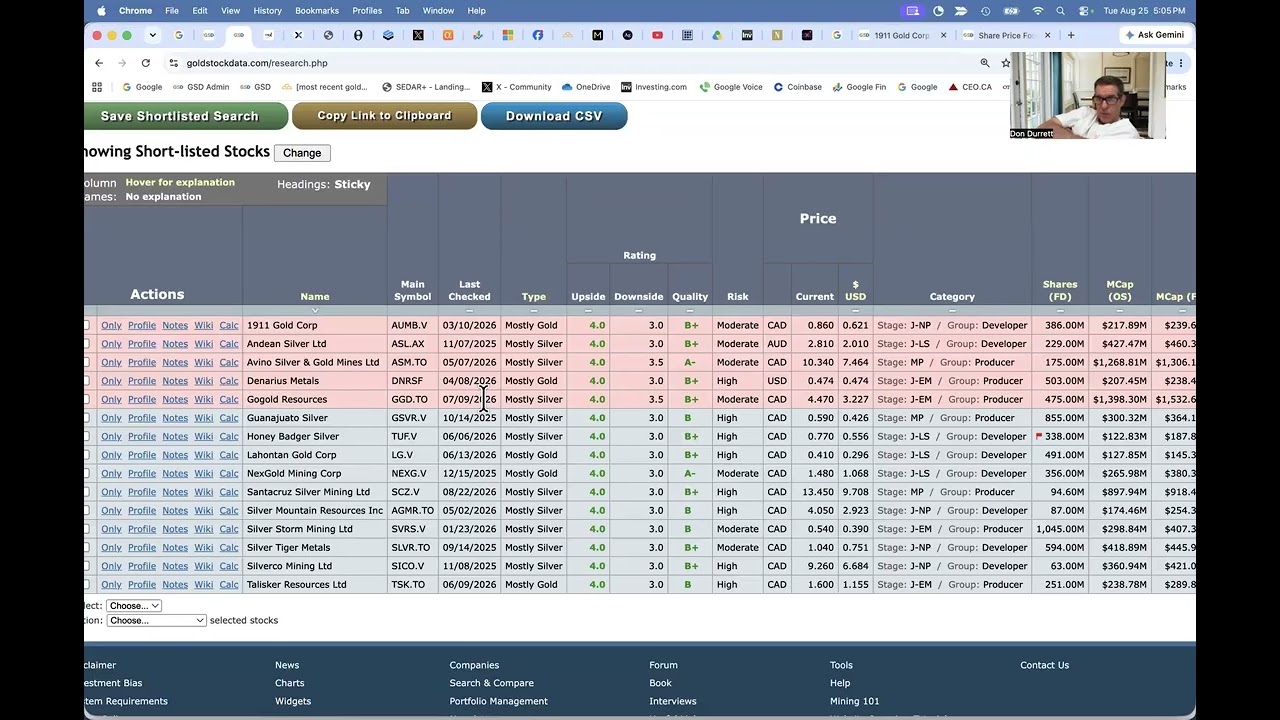
Gold/Silver Miners: Low Hanging Fruit (August 2026)
Key Highlights
brief- He notes Skeena 'will go into construction pretty soon' as one of the next Canadian single-asset developers to come online.
Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

Versamet Royalties–Record Q2 Earnings Metrics, Royalty & Streaming Partner Updates, Growth Into 2027
Key Highlights
detailed- Versamet's 3.52% gold stream on Skeena's SK Creek is described by the guest as uncapped, long-lived Canadian gold and the next major driver of growth.
- SK Creek was reported as more than 60% complete at mid-year, with first concentrate production targeted for spring 2027 and commercial production around mid-2027.
- The asset is expected to contribute about 10,000 GEOs to Versamet over its first five years of operation.
- An upcoming project optimization study is, in the guest's view, likely to yield a longer life-of-mine and an expanded high-grade core versus the original feasibility work.
Versamet posted record Q2 with revenue up 392% and EBITDA up 747% year-over-year, underscoring the cash-flow strength of its royalty model. The 3.52% Eskay Creek gold stream, due mid-2027, should lift attributable production to roughly 35,000 GEOs (gold equivalent ounces) versus 20–23K in 2026. Versamet's operator partners — Equinox, West African, Endeavour Silver — deliver asymmetric upside, since mine-life gains and grade improvements flow straight to its bottom line. Rosh Pinah's RP 2.0 expansion is ~95% complete and is on track to nearly double the mine's throughput to 1.4 million tons annually. Surprise catalysts — Cabral Gold's Cuiú Cuiú pour in September 2026 and Southern Copper's El Palar build starting 2027 — add ounces plus copper exposure.
Silver47 Exploration ($AGA | $AAGAF) on Red Mountain's Critical Mineral Potential & Path to 2027 PEA
Key Highlights
brief- Don says Skeena is currently in construction but doubts it will be in production next year
- Don suggests Skeena's first production could slip to early 2028
A 22-cent EV per ounce on Silver47 Exploration's 246M silver-equivalent ounces screens 2-10x below peers like Blackrock Silver, framing a clear valuation gap. The CEO argues most ounces are inferred, but three high-grade US projects (Red Mountain, Hughes, Mogollon) underpin a 1B-oz aspiration and a 2027 PEA. With $45M Canadian in working capital and four rigs running, Silver47 plans roughly 20,000 meters of 2026 drilling across Alaska, Nevada, and New Mexico. Co-hosts Don Duret and John Fenwick frame a deep correction in US silver developers as a contrarian bottom-fishing setup before a potential second leg up. Near-term producers like 1911 Gold, Denarius, and LaHontan anchor a broader US silver thesis alongside Silver47, all riding a bipartisan critical-mineral policy tailwind.

5.65 g/t Gold at Surface: GoldInxs Prepares to Drill at Fishpot Project in BC
Key Highlights
brief- The guest lists "Skene's SK Creek" among the Golden Triangle's most important Canadian discoveries; "Skene's" appears to be a speech-to-text rendering of Skeena Resources, and the transcript never names Skeena directly.
A maiden 2,000-metre drill program at GoldInxs' Fishpot project is the newly listed explorer's next major test. Airborne geophysics, geological mapping and geochemical sampling have each flagged the same drill targets at Fishpot. Surface rock samples returned up to 5.6 g/t gold, 11.3 g/t silver and copper mineralization ahead of any drilling. The guest calls Fishpot a large epithermal system, citing similar volcanic rocks and geochemistry to Artemis Gold's Blackwater mine, 65 km away. Millar adds Golden Triangle exposure and diversification in a district that has produced Brucejack, SK Creek and KSM.
Kingfisher Metals–Barrick Mining Comes In As Strategic Shareholder For Exploration Upside At Hwy 37
Key Highlights
brief- Perry names Skeena, alongside Teck and Newmont, as holding a larger Golden Triangle tenure than Kingfisher's.
- He notes Skeena is building Eske Creek, a former Barrick asset, as part of his argument that capital is moving into the district.
Barrick Mining will hold 9.9% of Kingfisher Metals after a C$20.9 million placement priced at C$1.35 per unit. At least 80% of the proceeds fund exploration and development at Kingfisher's Hwy 37 project in BC's Golden Triangle. The guest says the placement priced at more than double the March BMO financing, four or five months earlier. Pro forma treasury reaches roughly C$47 million, funding a fully paid 15,000-metre drill program with three rigs turning. Barrick gets a joint technical committee and full access to its technical staff, but the deal bars a project-level joint venture.

50 buy-the-dip stocks (July 17, 2026)
Key Highlights
detailed- Skeena Resources should be in production within about a year, and he thinks it is already close to either starting construction or reporting advances.
- It is a large, high-grade open pit in British Columbia with a good pipeline of projects behind it.
- He has long expected the company to be acquired, though nothing has happened yet.
He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.

Pitch Rick Ep #1 - Versamet Royalties
Key Highlights
detailed- Versamet paid $360 million ($340 million cash, $20 million shares) for an uncapped gold stream on Skeena's Eskay Creek project, which the CEO calls the cornerstone elephant of the portfolio, with production expected mid-2027.
- He concedes the pricing was tight: NPV roughly equal to the price paid, with analysts citing a low single-digit IRR, and the bet resting on Skeena's promised mine-plan upgrades.
- Skeena's chairman has said an updated mine plan will show higher grades in the first 10 years and extend mine life from 12 to 15 years, which the CEO says would greatly lift the stream's NPV; the study is due later this year.
- Construction is about halfway complete, and the CEO expects the stream to deliver over 10,000 ounces out of the gate.
- Skeena used part of a roughly $750 million high-yield note raise to buy the royalty down from over 10% to the 3.52% Versamet acquired from Orion and Blackstone, so no further buybacks are possible.
The CEO argues the value of Versamet's producing royalties alone exceeds its roughly $1.2 billion market cap, before counting development assets. Royalties (cuts of production, not mines) give Versamet 90% operating margins with eight staff; it trades near 10 times cash flow, well below larger peers. Gold-equivalent production has doubled annually from 5,000 ounces in 2024 and should reach a 35,000-ounce run rate once the Eskay Creek stream starts in 2027. The $360 million Eskay Creek stream was priced tightly, but Skeena's planned mine-plan upgrade could materially lift the stream's net present value. With about $370 million of debt repayable from under three years of cash flow, officers and directors own over 10% of shares.

The Biggest Mining Boom Has Barely Started | Craig Parry - Inventa Capital
Key Highlights
brief- Craig Parry says his group did a billion-dollar financing at Skeena a few months before the July 2026 interview, part of roughly $1.5 billion raised across the portfolio in six months.
- He cites Skeena among the team's successes — 'uranium, gold with Skeena, silver with Vizsla Silver.'
Craig Parry argues the junior mining bull market is just starting, comparing today's setup to 2006-2007 before that cycle went parabolic. Roughly $1.5 billion was raised across Parry's companies in six months, showing access to capital has reopened for junior miners. Parry sees copper reaching $30 per pound within five to ten years as demand growth outruns a near-total lack of new supply. Vizsla Copper enters its most important stretch: four rigs testing a porphyry system (a large-scale copper deposit), high-grade Woodjam zones, and Alaska's Palmer project. Data centers, electrification and AI add copper demand while major-mine expansions need about $20 billion, so supply cannot respond quickly.
Craig Parry: Updates on Vizsla Silver, Copper and Royalty
Key Highlights
brief- Parry cites Skeena as one of the metals where he has already succeeded, crediting Walt Cole for driving the company forward.
- He uses Skeena as the proof point for his claim that his teams find projects and move them into production quickly, calling the outcome there 'incredible'.
Vizsla sold its royalty spin-out 18 months after IPO, returning roughly eight times the IPO price to shareholders. Nine to ten rigs are turning across eight or nine copper targets in Alaska and British Columbia, with assay results due within weeks. Parry sees copper reaching $20–30 a pound within five years, betting constrained supply cannot match grid, data centre and EV demand. Ground work at Vizsla Silver in Mexico stays suspended after ten colleagues were killed, with permits still expected late this year. Cash of $26 million funds this year's drilling but falls below $5 million by year-end, making a raise in 2027 likely.

This Company Is Sitting on $24 Billion in Gold | Hugh Argo - Revival Gold
Key Highlights
brief- Agro names Skeena's recent project, alongside Detour and Osisko's Malartic, as an example of an unloved major-divested asset that turned into a significant producer, framing Mercur as a comparable case.
Hugh Agro argues gold developers like Revival Gold trade near $25 an ounce in the ground versus $500 for producers and over $4,000 for bullion. Revival Gold’s Mercur project in Utah, a former Barrick mine, targets 100,000 ounces a year on $208 million capex, helped by $100 million infrastructure savings. The CEO calls Mercur a Carlin-type system — the big gold settings that host major resources — and sees multi-million-ounce discovery potential. An Idaho exploration project adds 4.6 million ounces, with mineralization traced along 5.5 kilometers and about 5 kilometers still to test to the south. Watch for a pre-feasibility study by Q1 2027, completed permitting by end-2027, and a construction decision in early 2028.

David Lotan Shows You How to Make Junior Mining Millions: Aurion & Fox River Buyouts Explained
Key Highlights
brief- Lotan says Skeena went up about six times during the Aurion-Rupert conflict period, an example of stocks that performed far better than either embattled company.
Guest David Lotan built most of his Aurion and Fox River stakes buying public shares, arguing open-market bargains beat private deal access. Aurion Resources sold to Agnico Eagle Mines for C$481 million ($2.60 per share cash); Fox River Resources followed at C$94 million ($1.10 per share). Lotan ties the decade-long wait to consolidation among major gold producers; rising mid-tier buying power finally revived takeovers of juniors. The multiyear Aurion-Rupert standoff shows embarrassed, hostile bidders can drag out timelines and destroy value on both sides of a takeover fight. Management teams that refuse warrants (rights to buy future shares cheaply) and protect capital structures earn the investor trust that pays off at exit.

Craig Parry, Co-founder & Advisor of Inventa Capital | Rule Symposium 2026: Rick Rule interviews
Key Highlights
brief- Parry says he became Skeena's chairman in 2017 and helped the company acquire and advance the Eskay Creek mine toward production, calling it a tier-one gold project.
- He says Eskay Creek is going to produce about 450,000 oz per year.
Vizsla Silver holds about 400 million ounces of silver at grades near 500 grams per tonne, with the thick Coppola vein as standout. Cartel violence that killed ten workers, not geology, is now the central risk at Vizsla Silver — one of the world's highest-grade undeveloped silver deposits. Guest Craig Parry points to Mexican presidential backing and many newly issued permits, including open pit, as signs the project is turning the corner. Vizsla Copper is drilling beside a 44-metre intercept of 8.2% copper in Alaska as Parry pursues a mid-tier copper producer. Parry's track record spans Rio Tinto project generation, NexGen Energy's Arrow discovery, chairing Skeena, and selling Vizsla Royalty for $330 million.
This New Gold Stock Comes With a Mill, a Camp, and High Grades | Blue Jay Gold
Key Highlights
brief- Cited only as the outlier that skews the peer comparison: the host says the roughly $151 per ounce Yukon average he uses against Blue Jay's approximately $19 EV per ounce is pulled up by Skeena.
Blue Jay Gold's Yukon Stellar project pairs high grades with a 270-tonne-per-day mill — infrastructure a new junior rarely has. The spin-out history explains the listing: Riverside Resources distributed Blue Jay shares to its shareholders, then management acquired the project. Management is directing 70% of 2026 spending to growing a resource base of roughly 849,000 indicated and inferred gold-equivalent ounces. A $14.7 million April raise fully funds a maiden 16,000-metre drill program set to test three zones plus two historical discoveries. At about $19 enterprise value per ounce versus a Yukon average near $151, the discount looks wide but one large peer skews the benchmark.

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton
Key Highlights
brief- Skeena is said to now own the old Snip underground mine, which the company hopes to use as mill feed for another project described as advancing.
Seabridge's KSM is now the world's largest undeveloped gold project by reserves and resources, and second-largest for copper. Fronk argues capital efficiency is the real draw: at current metal prices after-tax NPV reaches $35 billion against a $6.4 billion build. Over $1 billion of roads, camps and grid tie-in is already built, so an incoming partner inherits spending rather than starting from zero. The remaining risk is a tunnel dispute with Tudor; both sides want a negotiated fix because neither wants a court trial. Nearly half of $750 million in on-site construction spending already flows to First Nations companies under impact benefit agreements.

Live Q&A with Rick Rule, Rudi Fronk, and Steve Barton 📱
Key Highlights
brief- The guest notes that the old Snip mine, which he has known since the 1970s era of flying supplies in and gold out, is now part of Skeena Resources.
- He says Skeena hopes to use the Snip material as mill feed for its other project, which he describes as advancing.
KSM is described as the world's largest undeveloped gold project by reserves and resources, and its second largest for copper. At $4,400 gold, net present value (what future cash flow is worth today) hits $35 billion after tax, with payback under two years. Life-of-mine production cost sits below $500 an ounce once copper, silver and molybdenum are credited against the gold. The main blocker is a haulage tunnel dispute with a neighbouring project; a permit amendment waits on that company's mine plan. Only about seven companies worldwide have the technical, financial and social capacity to partner on a project this size.

Why Copper Could Be Heading to a Price No One Is Ready For | Craig Parry - Vizla
Copper prices may surge dramatically higher due to years of underinvestment, permitting delays, and aging mines creating a severe long-term supply deficit. A significant disconnect currently exists between copper prices and copper equities, presenting a potential buying opportunity for investors in quality projects. Inventa Capital's copper portfolio, including the Palmer, Woodjam, and Poplar projects, offers exposure to high-grade copper assets in favorable jurisdictions.
#100 Digging for Dollars #28 The Game Has Changed Dan Earle and Access to Capital In the Mining Sect
Key Highlights
brief- The guest cites Skeena's recent bond as the clearest evidence of how cheap junior capital has become, saying it trades between 7 and 7.5 percent, roughly 150 basis points, on a straight bond with no conversion feature.
- He contrasts that with the roughly 20 percent all-in cost of capital on Lundin Gold's Frida del Norte financing and calls the change a sea change in cost of capital.
Access to capital, once a junior miner's edge, is no longer an advantage now that participation in resource equities has broadened. Cost of capital has collapsed: Lundin Gold financed Frida del Norte near 20%, while juniors now issue bonds below 9%. Big raises remove junior mining's top risk — getting through the valley of death — which makes dilution a secondary worry. Dan Earle argues investors anchored to prior cycles misread today's deals; newcomers without fixed priors often perform better. Three rapid pitches: a Nevada producer with a $750M NAV second asset, a $6M Peru silver explorer, and a fresh copper find.
Joaquin Marias, CEO of Argenta Silver | Rule Symposium 2026: Rick Rule interviews
Key Highlights
brief- Rick Rule compares Argenta to Skeena, saying that as with Skeena the concentrate penalties are irrelevant given the grade.
Historical metallurgy points to 90-96% silver recoveries, and refiners told the CEO his high-grade concentrate would face no arsenic penalties. Smelters blend concentrates to hit furnace grades, so exceptionally high-grade silver concentrate can be diluted and stay fully economical. The project holds about 50 million ounces of silver, 45.3 million of them indicated at 482 grams per ton, with only 8% of ground explored. Infrastructure serving Salta's lithium industry — rail, gas pipeline, power line — reaches within 3 kilometers of camp, keeping future capex low. Geologist CEO Joaquin Marias followed the Salta project for 16 years before taking Argenta from creation in October 2024 to drilling by May 2025.
Articles
No articles available
Published articles for this company will appear here
Want the full picture on more companies?
Be one of the first.
A room for resource investors taking shape now — independent, spam-free, no hype.