
Vista Gold Corp logo

Vista Gold Corp

VGZ

Vista Gold Corp., together with its subsidiaries, engages in the evaluation, acquisition, exploration, and advancement of gold exploration and development projects primarily in Australia. The company's flagship asset is the Mt Todd gold project located in Northern Territory. Vista Gold Corp. was founded in 1983 and is headquartered in Littleton, Colorado.

Score

—
Updated
—
—

Data Quality

N/A

Market Cap

N/A

Total valuation

Stock Price

N/A

Latest close

Free Cash Flow

N/A

Annual

Financial Position

N/A

Cash position

PEG Ratio

ⓘ

N/A

P/E ÷ growth

Analysis

Subscribe to see the AI Analysis

Score breakdown, criteria, red flags, bull/base/bear scenarios.

Subscribe

Financials

Subscribe to see Financials

Cash flow, balance sheet, valuation metrics, share structure.

Subscribe

Asset Pipeline

Subscribe to see the Asset Pipeline

Jurisdiction exposure, project portfolio, cost structure.

Subscribe

Information

Key Information

Legal Entity

Vista Gold Corp

Sector

Precious Metal

Founded

November 29, 1984

Employees

13

Reporting Currency

USD

Contact Phone

720 981 1185

Headquarters Address

7961 Shaffer Parkway , Littleton , CO 80127 , US

Identifiers

CUSIP

927926303

Commodity Portfolio

AU Gold Primary

Stock Exchanges

VGZ AMEX • USD
VGZ:NYSEAMERICAN
VGZ TSX • CAD
VGZ:TSE

Organization

Subscribe to see Organization

Management team and industry partnerships.

Subscribe

Chart

Loading chart...

Interactive chart powered by TradingView. Use the chart tools to analyze price trends.

Videos

This Gold Mine Is Worth $2.4 Billion With Just 2 Ounces Per Truckload - Liberty Gold

This Gold Mine Is Worth $2.4 Billion With Just 2 Ounces Per Truckload - Liberty Gold

The Deep Dive
6 days ago 12:59

Key Highlights

brief
  • Vista Gold is the only developer trading at a lower multiple than Liberty Gold on each company's own study numbers, with its Mount Todd project in Australia.
  • The host points out Mount Todd's failure bankrupted the company that originally closed Black Pine, yet at a like-for-like gold price Vista's project now trades at well under half of Liberty's NPV multiple.

Very low-grade ore can still pay: Black Pine skips the mill entirely, heap-leaching 0.29 g/t rock straight onto a pad to keep costs low. The $2.4 billion headline NPV is mostly a higher gold price — at constant prices, the study's value sits within about 6% of 2024's. All-in sustaining cost (AISC — the full cost to produce an ounce) of $1,566 sits high among peers, so a falling gold price bites harder. Permitting and funding remain the gates: the permitted plan is smaller than the study's, and $411 million is still to raise, perhaps via royalty. A 70% recovery assumption from uncrushed rock still awaits large column test confirmation, though Pegasus Gold leached the same rock for seven years.

John Feneck: Why These Critical Metals Will Explode Higher, 'Uncharted Territory' For Gold

John Feneck: Why These Critical Metals Will Explode Higher, 'Uncharted Territory' For Gold

Palisades Gold Radio
11 days ago 36:33

Key Highlights

brief
  • Cited as a Beaver Creek takeout at a low premium, and used as an example of the deals he dislikes: 20% to 30% does not compensate investors for the risk the developer carried.

The guest keeps gold's bull case intact through a painful consolidation, with $3,900–$4,000 support and $3,600 the next test if it breaks. He argues the Federal Reserve has no more bullets for aggressive hikes, calling current bond yields the highest since 2002. His portfolio uses GDX and GDXJ (gold miner sector ETFs) as a hub, then adds juniors and developers seen as eventual takeover targets. Critical minerals now make up roughly a quarter of his book, anchored by tungsten names as China supplies 81% of world output. He favours Nevada and Colombian explorers over riskier jurisdictions like the Congo, where nationalization concerns warrant a bigger discount.

Nick Hodge – Beaver Creek Recap, Key Newsflow In Portfolio Stocks, & Outlook On Gold, Silver, Copper

Nick Hodge – Beaver Creek Recap, Key Newsflow In Portfolio Stocks, & Outlook On Gold, Silver, Copper

The KE Report
13 days ago 23:59

Key Highlights

brief
  • Cited by Hodge as one of the small M&A deals done so far, in an M&A environment he describes as light with nothing major yet.

Junior resource companies are spinning out unloved assets into new vehicles, a track record Nick Hodge credits with unlocking shareholder value where portfolios stagnate. This year's Beaver Creek precious metals summit was the busiest yet, with institutional money out in force and companies focused on execution over bull-market debates. The guest argues copper is the strongest major metal, supported by data-center buildout, mine supply disruptions, and the absence of US import tariffs. Gold must hold $4,000, in Hodge's view, as a rising dollar and multi-decade bond yields oppose it, setting up a buying opportunity. Silver looks weaker than gold and could retest $55; Hodge is hunting a mid-tier silver producer but wants a better entry before buying.

Dave Erfle - Gold & Gold Stocks: Beaver Creek Recap, Metals Technicals, Recent M&A

Dave Erfle - Gold & Gold Stocks: Beaver Creek Recap, Metals Technicals, Recent M&A

The KE Report
14 days ago 19:04

Key Highlights

detailed
  • Erfle calls the Artemis takeover of Vista Gold a take-under: about $37 per ounce for 10.5 million in-ground ounces, with roughly $50 million of cash still on the balance sheet.
  • He says the discount reflects Mount Todd's hard-rock difficulty and Vista's failure to attract a strategic partner despite its Australian footprint.
  • He credits Vista's chief executive of some 20 years with strong de-risking and wonders whether a pending exit shaped the timing.
  • Vista still gets taken out near all-time highs, he notes; the name sat on his watch list and in his portfolio during the last cycle.

Beaver Creek was record-busy and juniors arrived cashed up, increasingly choosing to build projects themselves rather than sell, reshaping takeover dynamics. Seniors have repaired balance sheets, paid down debt and paid dividends, so replacing depleted ounces through M&A becomes the logical next step. Artemis's takeover of Vista Gold values Mount Todd's 10.5 million in-ground ounces near $37 each, a take-under reflecting the deposit's hard-rock difficulty. Gold's pullback may extend toward $3,950-$4,000 support if inflation runs hot and hike odds build, with GDX 85 and GDXJ 110 gaps in play. Erfle screens explorers for district-scale land packages, serially successful management, and projects over 5 million ounces that could attract a major.

50 buy-the-dip stocks (July 17, 2026)

50 buy-the-dip stocks (July 17, 2026)

Don Durrett
3 months ago

Key Highlights

detailed
  • The speaker says he has been convinced Vista Gold will build its Australian project, where the operation is located despite the company being Canadian and listed in New York.
  • He describes a large permitted project of about 8M oz of gold and expects construction to start next year.
  • He says the risk/reward is significant as long as the mine actually gets built.

He reviews 50 gold and silver mining stocks he owns, sizing the upside against $7,000 gold and $200 silver. Most of the list screens as an eight-bagger or better, and he favors undervalued producers growing output. Development names need patience: permits plus roughly two-year builds push many payoffs to 2028 and beyond. He cautions that gold and silver mining stocks are speculative, so keep allocations small and only risk what you can lose.

Rick Rule: Gold will Soar Over The Next 10 Years

Rick Rule: Gold will Soar Over The Next 10 Years

VRIC Media
4 months ago

Rick Rule argues that rising U.S. deficits and unattractive long-duration bonds create a strong macroeconomic backdrop for gold over the next decade. A wave of mergers and acquisitions is approaching for gold miners, with Rule highlighting Equinox, Calibre, and Orla as potential acquirers or targets. Rule sees uranium demand rising due to global energy security concerns, favoring developers like NexGen and UEC, alongside Uranium Royalty's acquisition strategy.

BUY THE DIP: Gold & Silver Are Nearing Floors Before Next Huge Climbs

BUY THE DIP: Gold & Silver Are Nearing Floors Before Next Huge Climbs

VRIC Media
5 months ago

Gold and silver are experiencing short-term pullbacks that represent buying opportunities before the next major price surge higher. Massive government debt, inflation, and money supply growth are creating a doom loop that will eventually trigger a financial reset. Specific mining equities like Vizsla Silver, Coeur Mining, and Endeavour Silver offer asymmetric upside for investors.

Don Durrett and John Feneck Interview Scorpio Gold ($SGN | $SRCRF) CEO on 50,000 m Drill Program

Don Durrett and John Feneck Interview Scorpio Gold ($SGN | $SRCRF) CEO on 50,000 m Drill Program

Investor TV
6 months ago

Key Highlights

brief
  • Don Durrett names Vista Gold among companies pivoting to production after realizing how much value they were leaving on the table.

Scorpio Gold is fully funded for a 50,000 m Nevada drill program, targeting growth from 740,000 oz toward 2 million oz this year. The CEO frames an eventual sale to a mid-tier as the goal, but says the company is not locked into any path. Grade is the differentiator: holding roughly 1.26 g/t against a 0.6 g/t Nevada open-pit average supports premium margins and strategic value. Durrett argues gold's pullback is a warning that the S&P is overextended, so he would buy junior dips rather than chase. The hosts frame junior mining returns as asymmetric: size positions small, buy capitulation, and only risk what you can afford to lose.

Newsletter Favorites Sorted by Quality (April 2026)

Newsletter Favorites Sorted by Quality (April 2026)

Don Durrett
6 months ago

Key Highlights

brief
  • Don Durrett says Vista could move up if it gets into construction.

Durrett ranks the 89 gold and silver stocks he owns on upside, downside risk, and company quality — a system investors can copy. His 'three-five' score marks a likely five-bagger — a stock he expects could multiply roughly five times from current levels. Only four holdings earn an A, reserved for low costs, clean balance sheets, and consistent execution — Australian mid-tier producers dominate the top. Country risk caps otherwise strong names: West African, Mexican, and Colombian exposure keeps ratings below top marks. He flags likely takeover targets among focused developers and producers still generating free cash flow.

“We’re on the Threshold of the Mother of All Resource Bull Markets” says Pro Speculator John Kaiser

“We’re on the Threshold of the Mother of All Resource Bull Markets” says Pro Speculator John Kaiser

MiningStockEducation.com
6 months ago

Key Highlights

detailed
  • The guest's DCF work shows Vista Gold should be worth $5 to $10 per share based on $3,000 gold — let alone $5,000 gold — implying large upside from around $2.
  • He notes the stock rose substantially from an original 60 cents, raised $45 million at $2.50 in a roughly $3-sized company, and was sitting at $2 as of the interview.
  • He says the institutional audience still treats buying Vista Gold and building a billion-dollar mine as 'stupid stuff,' viewing gold as a sunset industry — the inflection he is waiting for is institutions recognizing gold's fundamental price reset.
  • He references a 'PP2' copper-gold context separately, but Vista itself is his flagship example of juniors not even pricing $3,000 gold into their models.

Veteran speculator John Kaiser says the junior resource bull market is at a third-inning pause, with a three-to-five year advance still ahead. Gold's parabolic run to $5,600 needs six to nine months of repair, yet juniors still do not price even $3,000 gold into their models. Kaiser rotates profits from moved juniors into bottom-fish names under $100 million, favoring feasibility-stage and discovery stories. China's cheap critical metals strategy suppresses Western projects, but export blockades on tungsten and rare earths keep supply security pressure alive. He faults LIFE financings for enabling warrant-clipping flippers and prefers competent, underexposed management teams that build audiences organically.

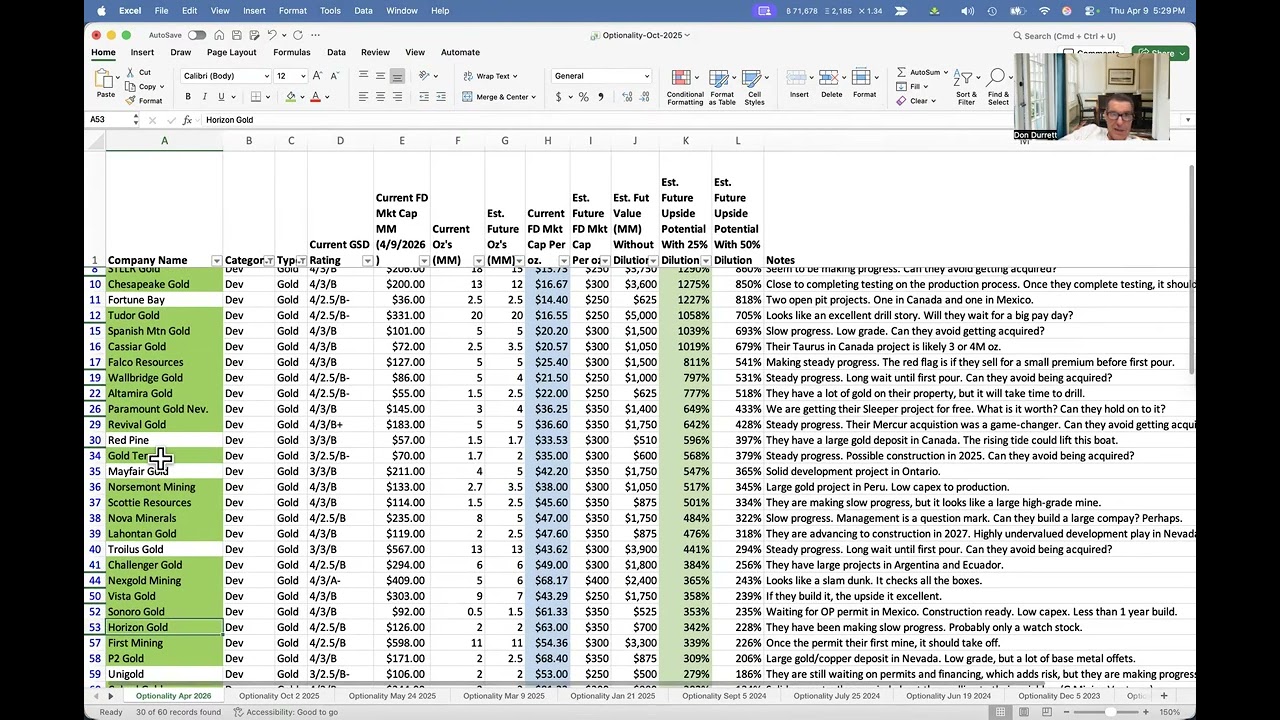
Optionality Update - April 2026

Optionality Update - April 2026

Don Durrett
6 months ago

Key Highlights

brief
  • Durrett says Vista Gold has decided to build the mine, which made him a buyer.
  • He models 9 million ounces with 7 million to be mined at about $44 per ounce, thinks his $250 (per ounce) assumption may be conservative, and hopes the company builds rather than sells.

G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Frederick Earnest of Vista Gold talks to John Kaiser | Metals Investor Forum | January 2026

Frederick Earnest of Vista Gold talks to John Kaiser | Metals Investor Forum | January 2026

Metals Investor Forum
9 months ago

Vista Gold CEO discusses advancing the Mt Todd Gold Project in Australia's Northern Territory with an updated feasibility study. The interview covers the development pathway and long-term value creation strategy for this significant Australian gold asset. Presentation took place at the Metals Investor Forum in Vancouver, highlighting management quality for potential investors.

Frederick Earnest of Vista Gold Corp. presents at Metals Investor Forum in Vancouver | January 2026

Frederick Earnest of Vista Gold Corp. presents at Metals Investor Forum in Vancouver | January 2026

Metals Investor Forum
9 months ago

Frederick Earnest, CEO of Vista Gold Corp., presents corporate updates and strategy at the Metals Investor Forum in Vancouver. Vista Gold is dual-listed on NYSE American and TSX, offering investors exposure to gold development with strong management. Forum provides vetted access to junior mining companies pre-screened by newsletter writers for quality management and properties.

Articles

Want the full picture on more companies?

Be one of the first.

A room for resource investors taking shape now — independent, spam-free, no hype.

Join the founding community on Discord