Don Durrett
LEGENDGold & Silver Mining Stock Analyst | Author | Founder of GoldStockData.com
"Valuing miners by where prices are going, not where they are."
Biography
Don Durrett became a gold bug in 1989 after reading a book that convinced him America's debt-fueled economic growth was unsustainable. His first stock purchase in 1991? A gold mutual fund. He hasn't looked back since.
Today, Durrett runs GoldStockData.com—a comprehensive database covering over 800 gold and silver mining stocks. His methodology combines rigorous data analysis with forward-looking valuation models, helping investors identify which companies offer the best risk-reward profiles at current prices.
What sets Durrett apart is his willingness to share his framework publicly. Through his Seeking Alpha articles, X posts (with over 70,000 followers), and frequent podcast appearances, he's become one of the most accessible voices in gold stock analysis.
Most analysts value mining companies based on current gold prices. Durrett doesn't. He projects valuations using $4,000 gold and $100-150 silver—prices he believes are coming based on structural economic factors. This forward-looking approach reveals which companies are truly undervalued versus which are fairly priced today. His analysis earned endorsement from billionaire Eric Sprott.
Videos (77)
Upside Gold ($UG | $UGODF): 3.31 Moz Historical Gold Resource and 5,180 Metres Drilled in BC
- Top takeaway Don Durrett frames Upside Gold as a bottom-bouncing value play: with gold around $4,100 and the stock near 46 cents US as of the interview, he says roughly $8 per ounce in ground against Banyan-style re-rating makes $150 per ounce 'absolutely in play', and he expects to buy the stock and make it his 17th exploration holding.
- He argues gold is trending toward $10,000 and that Canadian exploration projects, which traded north of $100 per ounce in ground in the last bull market, are headed far above current valuations.
- He contends undeveloped 3-million-plus-ounce deposits in Australia, the US, or Canada will be in heavy demand as M&A kicks in, because deposits of that size are becoming very rare and hard to find.
- He sees no red flags in the tight share structure (about 70% of shares in friendly hands) and the cash position, naming only possible resistance to open pits in British Columbia as a concern.
Upside Gold's Kena project in southern British Columbia holds a historical 3.31 million ounce gold resource, with an updated 43-101 estimate expected in Q1 2027. The 2026 drill program reached 5,180 metres, beating its 4,000 metre plan and finishing ahead of schedule, with assay results still pending. Management is targeting 4 to 5 million ounces by adding recent drilling, the Kena copper gold zone, and previously excluded copper and silver values. The host sees the company valued near $850 an ounce in the ground against a $34 million market cap, framing shares as cheap optionality. Flow-through dollars (tax-incentive financing for Canadian exploration) make up $3.7 million of the June raise, already covering the 2027 drill program.

Beaver Creek 2026 - Best Stocks
- Top takeaway His entry plan is to buy now with gold near $4,100 and weaker in October, then buy again below $4,000 and again below $3,700, describing three more buying opportunities.
- He is targeting 8 winners out of 10 on this list, having told readers he expects about 7 out of 10 from his overall portfolio and no one to get 9 out of 10.
- He expects the basket to average about a 15-bagger, which he calculates would make the whole group a 10-bagger, and says higher multiples are possible once a stock reaches three to five times.
- His grading framework has no A-rated names; he says the best stocks are the 4-3-5s, and that near-term producers offer the best risk-reward, with late-stage names carrying more risk.
- He says he owned the whole list going into Beaver Creek, added only to Osisko and Heliostar, and rotates positions into the stories he prefers.
Gold at $4,100 anchors his buy-the-dip plan: add again below $4,000, and again below $3,700. His Beaver Creek list holds 37 stocks, all rated as tenbaggers (ten-times-plus targets), with seven winners out of ten as the goal. He grades risk-reward by letter and number; near-term producers screen best, while late-stage projects carry more risk. Discovery Silver and Osisko Gold Group lead his Canadian gold picks, and Silver X's 250 million ounce resource lifted the grade. Low insider ownership makes Andean Silver, Talisker and Avino the likeliest takeover targets on his list.
Aya Gold & Silver ($AYA): From Updated PEA to Development at Boumadine
- Top takeaway Don argues Aya is dramatically undervalued, saying Boumadine alone should be worth the current $4B market cap and that Zgounder is worth another $4B if silver prices rise, implying the stock trades at roughly half of intrinsic value.
- He is deeply bearish on the macro set-up, arguing that with $40T of US debt and inflation above 2% for five years the Fed has no good choices, and that Warsh's September rate hike was a no-win move into a weakening economy.
- He claims Wall Street is 'out to lunch' on the mining sector, noting that all gold and silver equities combined represent only about 0.1% of the investable global universe while GDX and GDXJ returned roughly 155% and 175% respectively the prior year.
- He frames Aya as offering roughly 10x likely upside with 20x potential, modeling margins of $3,000-$5,000/oz if gold reaches $5,000-$8,000 by 2030 and noting production could scale toward 500,000 oz/year at under $3,000 AISC.
- He points to 1911 Gold as proof that the market waits until a mine is actually built before assigning value, which is why he expects Aya to re-rate once Boumadine breaks ground in early 2028.
Aya's Boumadine PEA shows a $3.5B base-case NPV and 93% IRR on $463M of capex, with no equity dilution needed. An AISC of $1,100/oz in years one to five keeps Boumadine robust even if silver stays in the low $60s. Full permits plus $200M cash and up to $300M in off-take prepayments leave the project fully funded through construction. The guest calls Boumadine the best gold-silver project globally; the analyst host sees 10x potential as Wall Street ignores the build.

Eastport Critical Metals ($EVI.V | $EVIIF): Targeting a Large-Scale Copper Opportunity in Botswana
- Top takeaway Don identifies BMC Minerals and Honey Badger as his preferred large polymetallic opportunities, citing their large, high-grade silver-equivalent resources.
- Don views Stillwater favorably for its mix of metals and argues that battery-related nickel demand could improve its optionality.
- Don concludes that Eastport is worth monitoring because of its tightly held 52-million-share fully diluted structure and the possibility of multiple large discoveries.
- Don considers copper grades around 0.5% potentially excellent and says Eastport's geology appears favorable for copper mining.
- Don argues that faster permitting in parts of Africa is an advantage relative to the long timelines required to build copper mines in the US and Canada.
Eastport's flagship Matsitama spans 1,854 square kilometres, with a 30-kilometre copper soil anomaly guiding geophysics and initial drilling. Semarule's first assay returned 330 metres of continuous rare-earth mineralization, while a central anomaly hole remains pending. Management prioritizes copper while advancing early-stage nickel, uranium, and rare-earth targets, using portfolio flexibility to allocate limited exploration capital. Botswana offers year-round access, established infrastructure, relatively straightforward permitting, and mining laws rooted in English law, according to Major. Major says Eastport holds $2.5 million cash and plans about 5,000 metres across projects, including 2,000 metres at Matsitama.

"America Won't Survive" As Debt Crisis Accelerates | Don Durrett
- Top takeaway Don Durrett argues the US is past a debt 'point of no return' and predicts a 'Humpty Dumpty crash' in which regional bank failures, a Fed-led currency reset, and political fragmentation end the United States as currently constituted
- He frames regional banks as the 'Achilles heel' of the US economy, saying the Fed will let some fail rather than print its way out of further inflation
- He describes a Fed 'doom loop' in which every policy choice makes the situation worse: rate hikes weaken the economy, rate cuts reignite inflation
- He expects the US to issue a new digital currency that converts dollar holdings at roughly 70 cents on the dollar — a 30% overnight haircut — and to orphan eurodollar obligations
- His defensive investment stance treats gold as the 'ultimate asset'; he recommends a starting position of 1,000 ounces of physical silver, plus Bitcoin and Ethereum, international assets, and food and water commodities, and warns that the stock market will deliver zero gains over the next decade
Don Durrett argues the U.S. is past the debt point of no return, locking the Fed into a 'doom loop' where every move backfires. He sees regional banks — heavy in commercial real estate and small-business loans — as the most likely crack when the next recession hits. Durrett recommends physical gold and silver as the primary defense, warning that paper vehicles like GLD and SLV carry counterparty risk. He expects a bond-market failure to force a new currency, deep federal cuts, and a state-by-state fragmentation of the union. The guest's database of 880 gold and silver miners and a 300-page book target investors who already own mining stocks.
Rua Gold ($RUA | $NZAUF): Unlocking Reefton’s Historic Goldfield
- Top takeaway Don says he likes RUA more after every update, citing the management team's execution (oversubscribed, warrant-free raises) and the project's multi-mine hub-and-spoke growth story.
- Don argues RUA's 25,000 oz/yr starter at Alt Creek could double fairly quickly into a 50,000 oz/yr producer, with cash flow funding ongoing drilling and growth.
- Don highlights the depth potential of the nine historic mines (mined to ~500m, with mineralized systems extending another ~1,000m) as the major exploration upside.
- Don argues the October 2026 fast-track application starts a six-month permitting clock pre-November 2026 election, effectively de-risking the project from the election outcome.
- Don expects RUA to pursue an acquisition ('Glen Morgan' mentioned by name) to grow into a larger company, citing Rob's capital-markets track record.
Reefton's Old Creek targets first antimony-gold concentrate by mid-2028 from a 25,000 oz/year starter mine with $130M CapEx. Nine undrilled historic mines at Reefton support a hub-and-spoke expansion that could roughly double throughput. Antimony co-product (25% antimony, 80 g/t gold) drew metal trader Mercuria into a $5M strategic investment. New Zealand's fast-track permitting compresses mine approvals to about six months; application is due October. Three oversubscribed, warrant-free raises let Rua Gold fund the permitting path with minimal dilution overhang.

Emperor Metals ($AUOZ | $EMAUF): Growing Duquesne West & Moving Lac Pelletier Toward Production
- Top takeaway Values Emperor Metals at roughly $3B in 2030 if Duquesne West reaches ~3M oz as a 100,000 oz/yr Canadian open pit at $7,000 gold, versus an ~$80M market cap he cites mid-September 2026 (10-20 bagger potential).
- Treats insider ownership of ~40% as a key quality filter and personally owns 92 development stories, including Emperor Metals.
- Sees the CEO's Detour Lake background as the single biggest credibility signal, calling the setup 'a shooting fish in a barrel' given the path from a major producing mine to a junior explorer.
- Endorses the develop-then-acquire-producer strategy, citing Discovery Silver and Integra Resources as successful examples of juniors that pivoted to producer status.
- Projects all-in sustaining costs under $2,000/oz at 100,000 oz/yr production at Duquesne West, supporting his $3B valuation thesis.
Emperor Metals CEO John Florek outlines a path to 3-5 million ounces at the Quebec Duquesne West project, with a PEA (preliminary economic assessment) targeted in 2027. Already-permitted Lac Pelletier could produce about 40,000 ounces per year and roughly $200 million in annual revenue at $5,000 gold, acting as a cash-flow bridge. Six nearby underused mills let Emperor skip building its own plant, a savings Florek pegs at $500 million to $1 billion in capex (capital expenditure). Insiders and high-net-worth holders appear to control more than 30% of a 32% public float, signaling tight supply and management alignment. Hosts frame juniors broadly as deep-value buys, expecting a decisive S&P-gold break around S&P 7,000 to reignite the gold leg higher.

Stillwater Critical Minerals ($PGE | $PGEZF): Updated Polymetallic Resource Sets the Stage for a PEA
- Top takeaway Don frames Stillwater Critical Minerals as a classic buy-and-forget-it optionality play, arguing investors should accumulate cheaply and wait for a major-acquisition exit.
- Don argues the project could reach roughly $1.5–2 billion in valuation if in-ground precious-metal values rise to $200–$300/oz gold-equivalent, even without further drilling.
- Don explicitly opposes spending on a PFS or full permitting, saying a PEA plus continued drilling is enough to attract Glencore-, Rio Tinto-, or Freeport-class buyers without diluting shareholders.
- Don flags the two risks for holders as a low-premium takeover by Glencore and equity dilution from over-spending, both of which management appears positioned to resist.
Stillwater Critical Minerals released its third, largest MRE: 4.82 billion pounds of nickel-copper-cobalt and 7.43 million ounces of PGMs (platinum-group metals) and gold. Stillwater's Montana project applies South Africa's Platte Reef bulk-mining model, targeting AISC (all-in sustaining cost) near $600 per 4E ounce. CEO Rowley plans a PEA in about a year but skips a full PFS, aiming to upgrade resources and attract a major's bid. Hosts frame Stillwater as a 'buy-and-forget' optionality play: buy ounces cheap, let the PEA re-rate them, then wait for Glencore or another major to bid. The U.S. has only one small nickel mine and no nickel processing capacity; Rowley is engaging D.C. on funding but says grants take time.
Lion One Metals ($LIO | $LOMLF): Tuvatu Gold Mine Production, High-Grade Drilling & Mill Expansion
- Top takeaway The guest argues Lion One is a high-risk/reward producer, not an explorer — at 12.5 cents US the risk/reward looks compelling if management can creatively clear the $25M December debt wall via private equity, hedge funds, or a JV partner, with gold at about $4,400 making strategic interest more likely.
- The guest expects an S&P correction to drag gold down before year-end, then a rip higher — he forecasts gold above $5,000 by the end of 2026.
- On the macro, the guest thinks the Fed has zero probability of raising rates this year despite a likely hot CPI print, prioritizing growth and bond-market stability; he watches only the S&P 200-day moving average (~7,200) and wants the gold-to-S&P ratio at 0.70 versus 0.57 today.
- The guest flags the 715 g/t intercept as a unicorn hole — top three of the year on Mining Hub — and notes the hole also ran 6,500 g/t over 0.445 m with the remaining intercept still grading 12.48 g/t, which he says could lift mill head grade from 5-5.5 g/t toward 6 g/t.
- The guest is also bullish on the copper angle — copper at an all-time high adds prospectivity to the caldera drilling Lion One is restarting.
Refinancing of Lion One's $25.8M NABARI tranche gives the company a 4-month runway to year-end to secure alternative funding. A 4.2m intercept at 715 g/t gold near existing workings ranks among the highest-grade holes tracked globally in 2026. Mill throughput expansion to 650 to 700 t/day by mid-2028 could push AISC (All-In Sustaining Cost) below $2,000/oz. Management sees roughly 35,000 oz/year as achievable by late 2028 at 5-plus g/t head grade and 700 t/day throughput. Fed rate expectations turning dovish alongside geopolitical de-escalation sets up a constructive year-end backdrop for gold.
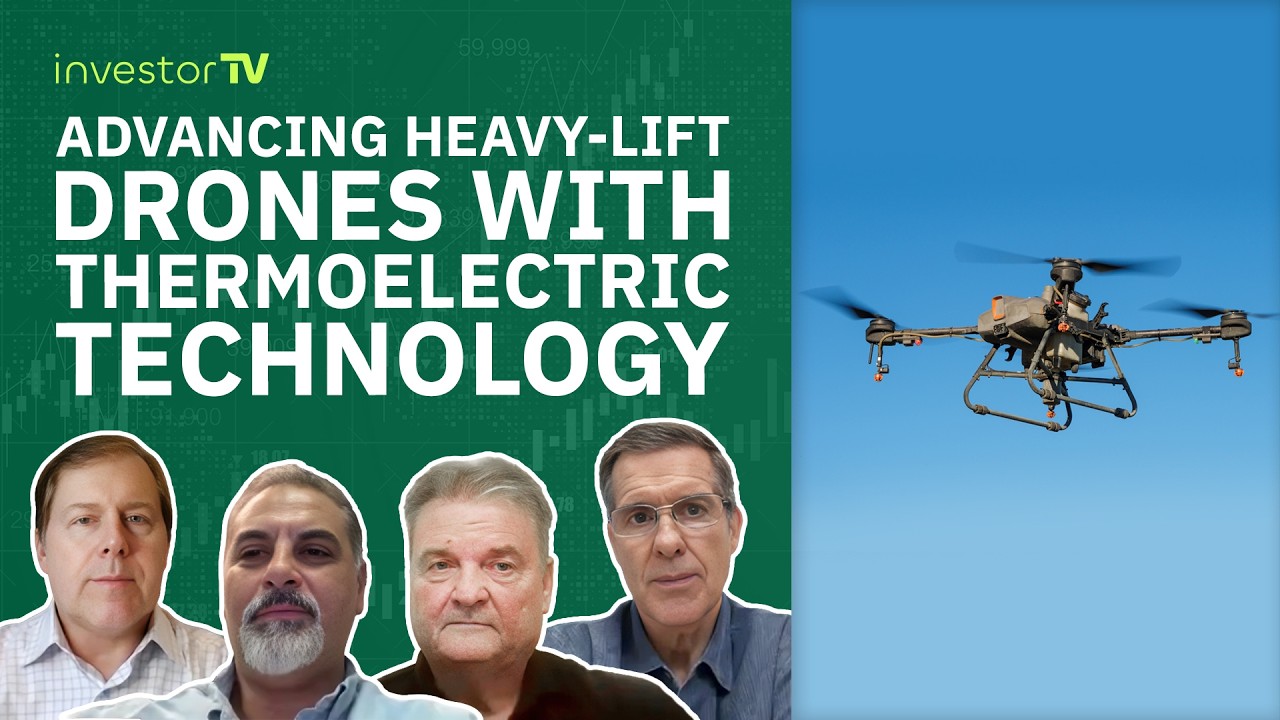
First Tellurium ($FTEL | $FSTTF) & PyroDelta Energy on Heavy-Lift Drones and Thermoelectrics
- Top takeaway Don asks how large the tellurium deposit is and how long it will last, signaling investor focus on resource depth.
- Don argues drone manufacturing has a low regulatory barrier since it only requires a permit, with no environmental testing.
PyroDelta's 150-pound drone carries 300 pounds for two hours at 40 mph — a 2:1 payload ratio that beats most heavy-lift competitors. The team designed its own 40-horsepower engine after manufacturer specs fell short, then built a thermoelectric heat-recovery system around it. First Tellurium's Deer Horn property in British Columbia hosts tellurium, silver, gold, bismuth, copper, and molybdenum — inferred tellurium of roughly 100 tons. An end-of-September Florida demonstration targets firefighting, search-and-rescue, and northern-Canada logistics as the first drone revenue path. Tellurium's role in thermoelectrics opens adjacent opportunities in solar overnight generation and data-center heat recovery, offering non-mine revenue.

White Gold ($WGO | $WHGOF) Advances Its 3-Million-Ounce Gold Resource in Yukon
- Top takeaway Don Durrett argues miners are starting to outperform gold (since July of this year, the gold/S&P ratio sits around 0.55 and he wants to see it climb toward 0.7-2.0) and that money will rotate from broad equities into miners over the next two years.
- He expects a near-term correction in September/October 2025 driven by midterm-year seasonality, but sees any dip as a buying opportunity, with gold heading to $4,200 before $5,000 and most Fed tightening already priced in.
- Durrett calls Agnico his largest holding and 'the best gold miner in the world,' frames the Yukon as becoming one large mining district, and labels White Gold a potential 10-bagger development play with a $3B+ price target.
White Gold's maiden PEA on 2 of its 3 million ounces delivers C$1.9B NPV at $3,600 gold, scaling to C$3B at $4,500. Sub-$1,500 AISC and 225,000 oz/year in the first 5 years make Golden Saddle Yukon's highest-grade development story. The company's largest-ever exploration program is drilling now, targeting district-scale growth across 750,000 acres. Agnico Eagle's 19% stake plus its position in neighboring Talamore/Coffee hints at district-scale consolidation in Yukon. Macro view: a seasonal September/October correction is likely before gold pushes to $5,000, with miners now outperforming the metal.

Don Durrett: Gold Miners 'The Most Asymmetric Upside' & The Point of No Return for Gold
- Top takeaway Don argues the US crossed his 'point of no return' on the debt bubble in August 2026, with Bessent's interventions marking stage 5 of a 7-stage framework; he says they are now in stage 6 (confidence waning) and expects 'doom loop' recognition in 2027.
- He holds a $15,000 gold target with a $3,750 floor, sees silver outperforming gold by 2x with a $1,000 ceiling, and frames the next leg (Nov/Dec 2026 toward ~$6,500) as the 'fun wave' before a larger leg-three mania.
- He expects gold miners to deliver massive leverage — ETFs/SILJ/GDX potentially doubling each leg for a 300%+ base case over two years, with Newmont and Agnico as 3-baggers making 10-baggers in smaller names easier to find.
- He flags gold/silver miner valuations as still 'uber cheap' at ~9–10x free-cash-flow (some under 5x) versus an expected re-rating to 'high teens', and calls the setup the 'most asymmetric' he has seen.
- His portfolio discipline is buy-the-dip and sell smart toward the top — he has stopped accumulating above HUI ~830, only adds on dips, and runs ~170 names expecting 7 of 10 to work while 'purging dogs' each December.
Don Durrett argues gold's $3,750 floor and $15,000 ceiling reflect a seven-stage debt bubble now entering stage five (interventions). He expects a near-term pullback to $4,100-$4,200 before gold's next leg higher toward $6,500 in November. Silver should outpace gold 2x via a 2-4% silver-to-gold ratio, targeting $200-$500 as the bull matures. Junior miners deliver compounding leverage — producers could 3-bag and developers 10-bag as free cash flow multiples expand. Treasury interventions starting July 2026, signaling bond market fragility, are the catalyst that wakes Wall Street to gold.

Gold’s Next Leg Could Be Huge
- Top takeaway Don Durrett's base case is three more leg-ups in gold, with the current leg pushing from $4,000 to roughly $6,500 and a third leg correcting back to about $5,500 before a final run toward $8,000.
- He argues corrections are getting shorter and shallower — the last took about seven months, and he expects the next to last under two months, possibly only one-month dips with no deep pullbacks.
- He also floats a fourth-leg scenario toward $10,000, framing that as a possible upside bonus rather than his base case.
The guest argues gold could advance from $4,000 in three legs: first ~$6,500, then ~$8,000, with $10,000 as a possible fourth leg. Corrections between legs are expected to be brief — roughly one to two months versus the prior seven-month pullback. Price targets only — no company, drill, or project-fundamental updates for investors to act on here.
First Phosphate ($PHOS | $FRSPF) CEO on Advancing Its Quebec Phosphate Project
- Top takeaway Durrett presses the CEO on LFP fire safety versus NMC batteries, on whether solid-state still has a charging edge, and on the projected ~$250M/year cash flow around 2028, while highlighting that the CEO takes 100% of pay in RSUs/shares as shareholder alignment.
- In his closing he argues US equity-market fragility makes critical-mineral equities like First Phosphate a defensive picks-and-shovels bet, warning that China could cut LFP battery exports entirely — a scenario he calls a 'complete cut-off' — and frames tariffs and gold's rise as symptoms of the US debt problem.
First Phosphate could supply up to 350 GWh of LFP battery feedstock from a single Quebec igneous phosphate deposit, management says. Updated indicated resources grew 378% in this week's mineral resource estimate, supporting a project NPV of $2.1B and IRR of 37%. The guest argues phosphate, not lithium, is the overlooked choke point for North American LFP cathode supply. The project is one of just three North American igneous phosphate deposits; Agnico Eagle recently acquired a second via Martison. Management ties near-total Chinese LFP dominance to broader US bond and currency fragility, framing critical minerals as a hedging play.
The Doom Loop Has Already Begun
- Top takeaway The guest argues a financial crisis is inevitable within the next three years, framing a 'doom loop' that has already begun and stating there is no way to avoid it.
- The guest claims the Fed and Treasury have been manipulating markets since 2008 by tying money-supply expansion to stock-market gains, using money printing to generate wealth rather than real growth.
- The guest contrasts this with 19th-century U.S. growth, arguing economies can expand without printing money and that doing so 'is just asking for trouble.'
- The guest criticizes 'Besent's' announcement that the Treasury will buy both the long and short end of the bond market, calling it explicit manipulation of the bond market and 'a really bad thing.'
Don Durrett argues the U.S. is already inside a financial doom loop driven by post-2008 money printing. He blames Fed and Treasury bond-market intervention for lifting stocks while making the system more fragile. He forecasts a financial crisis within roughly three years, pointing to money-supply growth that mirrors equity prices. He contrasts today's policy with 19th-century growth, which he says happened without money printing to drive GD@.
What’s Next for Gold & Silver? Market Analysis With Don Durrett and John Feneck
- Top takeaway The guest calls the current gold move 'technical' — driven by Bessent's operation twist, a softer dollar, and a flatter yield curve — not the fear trade he really wants to see.
- He frames the sector as being in the 'third inning' of a three-leg bull market and says he's bullish on Q4 2026 and very bullish on 2027.
- He lists global stresses — Japan FX intervention, France's 10-year at 4%, the KOSPI struggling at highs, and the Iran war — but says gold isn't yet getting a fear bid.
- His preferred risk-reward setup is undervalued producers with growth ahead (Goldgroup, Excellon, Denarius).
- He targets HUI 3,000 and argues that at 800+ there's still no positive sentiment in miners, which is why he thinks the upside remains large.
Don and John call the Aug 19 gold-silver rally seasonal, not yet a structural breakout; HUI is above 800. Bessent's surprise long-end Treasury bid weakened the dollar and sent GDX up 8% and silver up 10%. Miners are starting to outperform the metal — a leading signal that institutional rotation into the sector could be starting. Undervalued producers with growth ahead — Goldgroup, Excellon, Denarius, LaHontan, 1911 Gold — screen as the best risk-reward in this tape. Both analysts are bullish into Q4 2026 and 2027, but the real test is whether capital rotates from equities into miners.
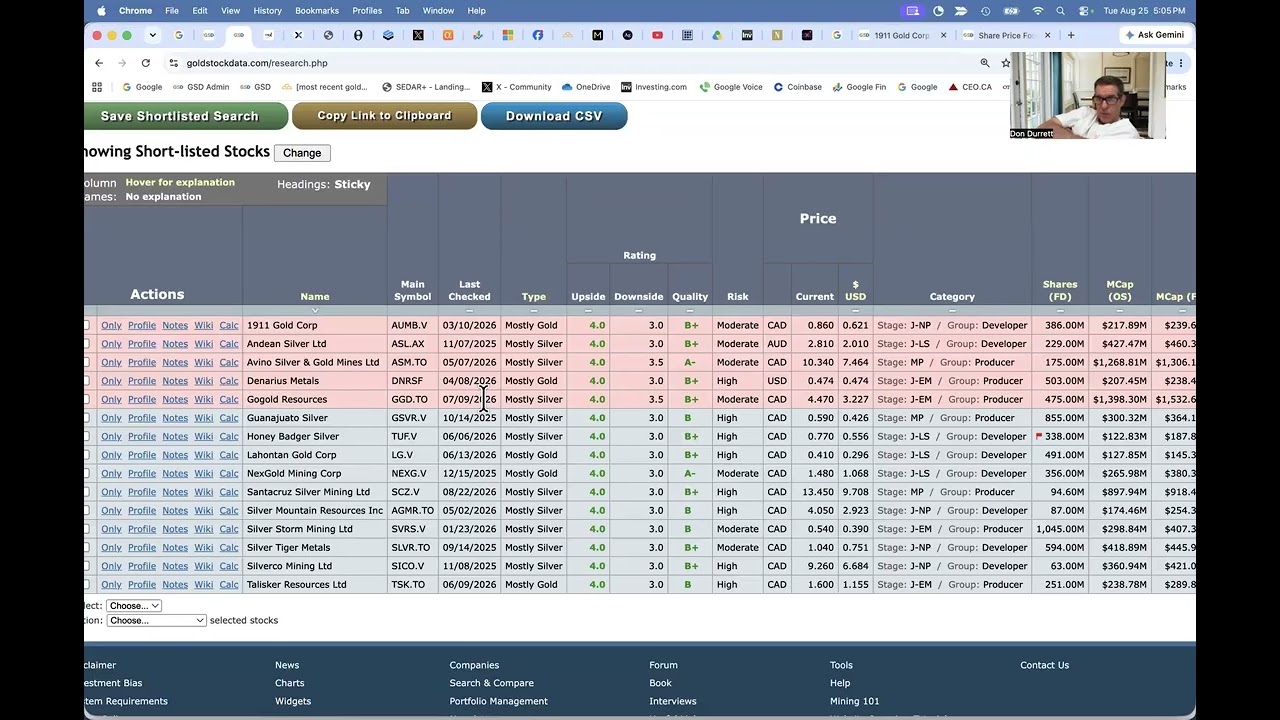
Gold/Silver Miners: Low Hanging Fruit (August 2026)
- Top takeaway Frames the video around his 'low-hanging fruit' screen — 15 names scoring '4' quality at B+ or better, with an average ~15–20x upside, picked because they have leverage to higher gold/silver prices with attractive risk/reward.
- His core analytical framework is to find undervalued producers or near-term producers with planned organic growth and limited dilution, then wait for execution.
- He systematically screens for 'red flags' — insider strength, location risk, dilution, permitting, and capex certainty — and names them openly for each company.
- He actively flags takeover candidates (Andean, Avino, Talisker) where insider ownership is weak, and proposes merger-of-equals pairings (e.g., Talisker with 1911 or Honey Badger) as a defensive move.
- He models these names at long-term $200 silver and $6,000–$7,000 gold to size upside.
Don Durrett's 15 low-hanging-fruit names share a single thesis — execution on planned growth at $200 silver and $7,000 gold unlocks 5-20x upside across the list. Junior miners with low insider ownership become prime hostile takeover targets once their assets are de-risked, so a defensive merger often precedes the rerate. The market is still leaving the second-mine pipeline at NexGold and GoGold free, because the first project's standalone value already exceeds today's market cap. Canada's scarcity of new single-asset gold producers gives each one a permanent jurisdiction premium that U.S. peers cannot replicate. AISC (All-In Sustaining Cost — what it really costs to produce an ounce) is the single variable that decides whether each near-term producer on this list rerates or fades.

Don Durrett: $8,000 Gold & $200 Silver Are Coming
- Top takeaway Expects the gold bull to run in three legs from around $4,000: the current leg to about $6,500, then shallow corrections and a run toward $8,000 within roughly three years — possibly $9,000-$10,000 if a fourth leg develops.
- Argues the 'doom loop' has already started: $40 trillion of US debt with over $1 trillion in annual interest against about $5 trillion of receipts, rising inflation, and a bond market foreigners no longer fund at long durations.
- Claims the Fed's real mandate under Kevin Warsh is economic growth at any cost, so Treasury bond-buying plus Fed buying since January mean ever more money printing — the engine of his gold thesis.
- Plans to sell his entire miner portfolio between $7,000 and $8,000 gold, with silver at $200-$300 this cycle (calling $150-$175 conservative), warning the eventual top will be brutal as in 1980 and 2011-2015.
- Runs a 171-stock portfolio almost entirely in producers and developers that respond to metal prices (about 2% explorers), culls problem companies via a 'probation' system, and wants developers to begin construction by 2029 at the latest.
Treasury bond-buying and $1-trillion annual interest costs confirm the debt 'doom loop' is underway, Durrett argues, making bond-market fragility gold's driver. He maps three gold legs to roughly $6,500 next year and $8,000 within three years, planning to sell his miners between $7,000 and $8,000. Silver could reach $200-$300 this cycle; silver miners' margins (profit per ounce) could swell from $10 to over $200. He favors producers and developers over explorers: free cash flow (cash left after mining costs) makes their shares react to metal prices. His risk playbook: cull problem stocks, keep position sizes small, expect most picks to disappoint, and avoid developers with late construction dates.

Aya Gold & Silver ($AYA) on Strong Q2 Revenue Growth, 400,000-Tonne Silver Ore Stockpile
- Top takeaway Don Durrett central call is that Aya is materially undervalued: at his assumed $200 silver and ~$50 AISC, 42 million oz/yr at Boumazin implies about $6.3 billion of annual free cashflow, which at a 15x multiple would put Aya near $90 billion versus its ~$4 billion market cap at the time of the interview.
- He pushes for a structured share buyback tied to a percentage of free cashflow (25–50%) and recommends that mining companies hold 25% of treasury cash in physical silver as a hedge against potential USD devaluation.
- Don frames silver as heading north of $150 by Boumazin 2029 commissioning (silver hit $121 earlier in 2026) and lists Aya among his top-10 silver names as of August 2026.
- He identifies the main risk as the time to full re-rating — Boumazin commissioning targeted mid-2029, roughly three years out — but expects meaningful re-rating to begin by end of 2027 as the free-cashflow story becomes visible.
Aya's Zgounder mine is running as a cash machine: Q2 revenue up 151% YoY, operating cash flow up 522%, with payback on $140M capex inside five months. Boumadiene is targeting 37M ounces of silver a year at an AISC (all-in sustaining cost) under $15, lifting Aya to roughly 43M ounces by mid-2029. Q3 and Q4 historically deliver about 60% of annual silver production at the Moroccan operations because winter weather slows Q1 and Q2. A 400,000-ton ore stockpile gives the mill roughly two quarters of feed if mining halts, materially de-risking any short-term pit disruption. At a roughly $4B market cap, even conservative silver prices imply material upside as Boumadiene approaches commissioning.
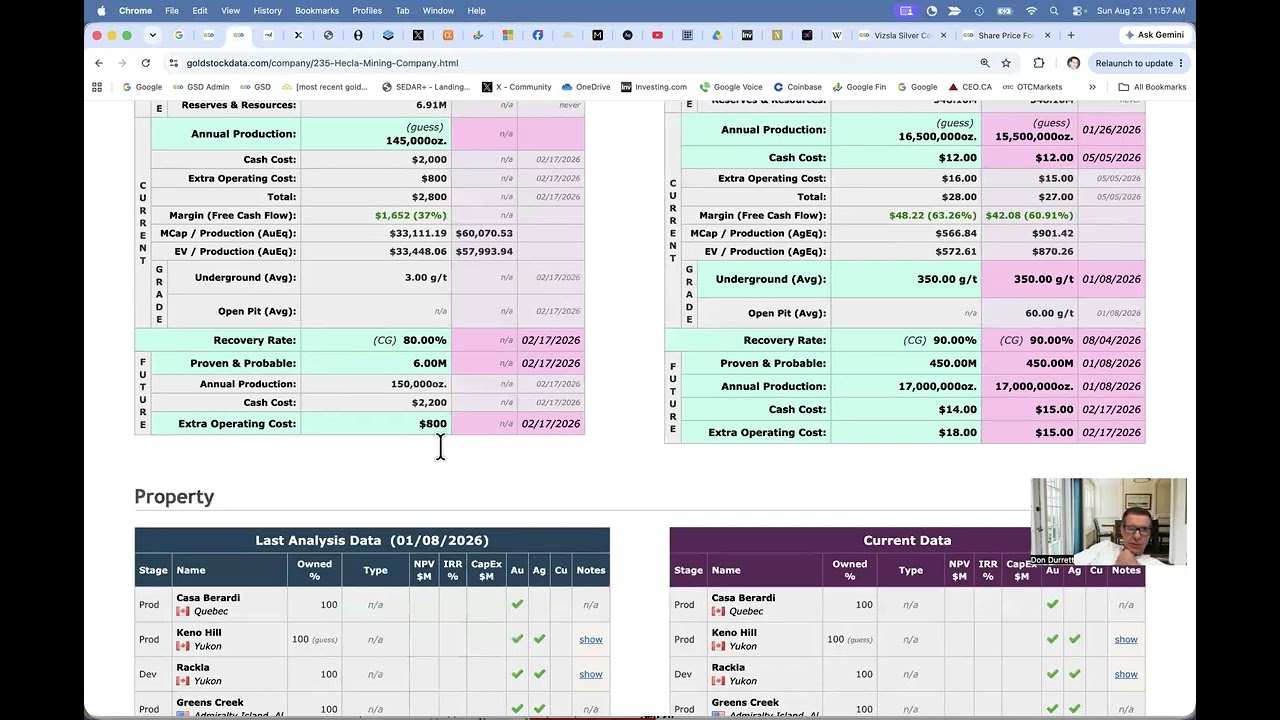
Share Price Forecast Tool (August 2026)
- Top takeaway Don demonstrates his GoldStockData share price forecast tool, which values miners on future fully diluted market cap and cash-flow growth — never on resources — across 12-, 24-, and 36-month horizons.
- His near-term call on Hecla is muted: it needs an all-time-high silver price near $110 just to double in 12 months, though he sees a four- to five-bagger in three years at $200 silver.
- His strongest conviction is in Vizsla as a really cheap, fully funded developer with, in his words, 'absolutely massive' leverage to the silver price.
- He stresses adjusting the multiple and share count for expected dilution or buybacks, and expects producers like Hecla to shrink their share counts through buybacks.
A share price forecast tool turns production, share count, cost, and silver price assumptions into 12-month and three-year return scenarios for miners. Durrett models Hecla at roughly a double in 12 months near $110 silver, and a four- to five-bagger at $200 silver in three years. Developer Vizsla Silver prints the biggest scenarios: a 30-bagger at $200 silver and 40-bagger at $250 silver, with $480 million cash limiting dilution. AISC (all-in sustaining cost — what it fully costs to produce an ounce) and the price-to-cash-flow multiple are the main levers besides metal price. He adjusts developer share counts for expected dilution and capex (upfront capital spending), and expects producer buybacks to shrink share counts.
Key Quotes
"Is the stock market telling the truth at an all-time high, or is it gold that's telling the truth? Well, it's pretty obvious that gold is the one telling the truth."
"You're projecting what that price will be. And so you're saying when the market collapses or when the bond market implodes, then you're going to see what type of functional prices are you using now."
"Gold equities are being mispriced unbelievably in today's market given the prospective rise in the metal's price."
Key Works
Available on Amazon
Specializations
Disclaimer: Don Durrett has NOT endorsed this platform and is not affiliated with Pixys in any way.