Don Durrett
LEGENDGold & Silver Mining Stock Analyst | Author | Founder of GoldStockData.com
"Valuing miners by where prices are going, not where they are."
Biography
Don Durrett became a gold bug in 1989 after reading a book that convinced him America's debt-fueled economic growth was unsustainable. His first stock purchase in 1991? A gold mutual fund. He hasn't looked back since.
Today, Durrett runs GoldStockData.com—a comprehensive database covering over 800 gold and silver mining stocks. His methodology combines rigorous data analysis with forward-looking valuation models, helping investors identify which companies offer the best risk-reward profiles at current prices.
What sets Durrett apart is his willingness to share his framework publicly. Through his Seeking Alpha articles, X posts (with over 70,000 followers), and frequent podcast appearances, he's become one of the most accessible voices in gold stock analysis.
Most analysts value mining companies based on current gold prices. Durrett doesn't. He projects valuations using $4,000 gold and $100-150 silver—prices he believes are coming based on structural economic factors. This forward-looking approach reveals which companies are truly undervalued versus which are fairly priced today. His analysis earned endorsement from billionaire Eric Sprott.
Videos (77)

$7,000 Gold Incoming? How Mining Stocks Could Deliver 20 Baggers | Don Durrett
Gold and silver are entering a massive secular bull market, with price targets potentially reaching $7,000 per ounce for gold. Mining stocks offer extraordinary leverage to rising metal prices, presenting credible opportunities for 10 to 20-bagger returns. Investors should use market corrections as buying opportunities and focus on identifying high-quality mining shares with robust fundamentals.
Don Durrett & John Feneck Interview Mayfair Gold ($MFG | $MINE) on Building a Mine in Ontario
- Top takeaway He calls Mayfair a five-to-ten-bagger development opportunity that checks all his boxes: a 4-million-ounce-plus project with a 1.47 g/t starter pit and ~90% recovery, a top-tier Timmins location, a solid path to production and about 40% insider ownership, though he expects inflation to hold AISC nearer $1,500 and free cash flow nearer $200 million a year.
- His metals framework is war-dependent: gold is stuck in a 4,500-5,000 range and silver in 70-90 until the war resolves, with a quick end sending both higher and a prolonged conflict sending them lower.
- He favors undervalued and near-term silver producers: Avino, Americas Gold & Silver and Santacruz as undervalued five-bagger-plus candidates, plus near-term names like Silver Mountain and Silver Storm, with Andean Silver restarting in Q1 2028.
- On Americas Gold & Silver he points to the Galena mine's ~200 million ounces at ~400 g/t with three shafts (only one in use), valuing the company on roughly 7 million ounces of annual production versus management's 10-million-ounce target.
- He came away struck by how difficult Canadian federal greenfield permitting is, five to seven years for the environmental assessment alone, so he argues companies close to production, like Mayfair at about four years out, carry real value and optionality.
Mayfair Gold is permitting a 4,800 tonne-per-day starter pit at Fenn-Gib provincially, cutting years off the federal route to first production. Projects under 5,000 tonnes per day permit provincially in Ontario, avoiding a federal review where no new (greenfield) mine has won approval since 2019. Management guides to a sub-$1,200 AISC (All-In Sustaining Cost — the full cost to produce an ounce) and first gold in 2030. Staying small preserves optionality: regional high-grade and underground tonnes can sweeten mill feed (raise average grade) without expanding throughput or new federal permits. Don Durrett favors undervalued, leveraged silver producers while John Fenwick argues war headlines, not fundamentals, gate gold's next move.

'Never Been More Bullish' - 'Unbelievably CHEAP' Gold & Silver Stocks Set to Rip
John Feneck and Don Durrett see massive undervaluation in gold and silver stocks, describing them as unbelievably cheap and set to rip higher. The experts open up their portfolios to reveal top stock picks in the precious metals sector they believe are currently on sale. Discussion covers the macro backdrop for precious metals, geopolitical risks like the Iran war, and specific gold and silver stocks to watch.
Don Durrett & John Feneck Interview Rua Gold ($RUA | $NZAUF) CEO on Exploration Strategy
- Top takeaway Reveals he bought Rua Gold after the October 2025 interview, rates it highly on GoldStockData, and says that after this update he likes the stock even more and is weighing adding to his position before the PEA due around May 2026.
- Argues the US economy is fragile after 25 years of Fed-driven manipulation: consumer confidence just hit a record low near 55, GDP is running around 1.5% (he believes recession has already begun), and the Iran conflict, gated private-credit funds, AI layoffs and boomer retirements are pushing markets toward a 'panic button' selloff he thinks is close.
- Contends investors do not have to worry about Rua's PEA: with gold around $4,500/oz in April 2026 (he does not see it below $4,000) and CapEx he puts at $100-120 million, NPV should comfortably exceed twice CapEx, so IRR and free cashflow should be fine.
- Calls New Zealand politics the story's only red flag, a small country where a left-leaning government could curb mining, but is comfortable because Rua is already in the fast-track process and the South Island is, per the CEO, about 99% pro-mining.
- Sees big growth potential: the first mine looks set to exceed 1 million ounces with five or six high-grade past-producing mines to drill deeper, backed by a team that has built eight mines, sold $11 billion worth of companies and raised over $2 billion, plus a strong balance sheet and tight share structure.
Rua Gold is fast-tracking a small, high-grade gold-antimony starter mine in New Zealand's Reefton district, targeting a fully permitted mine by April 2027. New Zealand's six-month permitting and a PEA (Preliminary Economic Assessment, an early study of mine economics) due within a month anchor the path to production. Grades above 1% antimony, roughly 20 times what the CEO cites at Perpetua's Utah project, would make Reefton New Zealand's biggest critical mineral deposit. About $63 million raised since October leaves a strong treasury and sticky institutional shareholders, including metals traders seeking future antimony offtake. Analysts see contained political risk: the pro-mining South Island and fast-track approval shield the project even if government changes, with $4,000-plus gold underpinning economics.

Don Durrett & John Feneck Interview Earthwise Minerals ($WISE | $EWISF) on the Iron Range Project
- Top takeaway Durrett frames Earthwise as a fast-payoff speculation: you are definitely rolling the dice, but a few good holes could get paid off quickly, and he calls it the ultimate spec bet.
- He argues the 87 historical holes and road access separate this from a greenfield project — the team knows where to drill, and one good hit should get market attention quickly because of the project's history.
- He points to the recent tape — about C$0.02 two months before the interview, a run to C$0.08, then back to about C$0.04 — as evidence of both the volatility and the potential.
- He cautions the sector is capital-intensive and requires constant financing to drill, but notes the catalyst is close, with drilling set to start about a month after the interview.
Earthwise Minerals plans about 1,200 metres of May drilling across three or four holes at the Iron Range Talon zone. CEO Mark Luchinski anchors the story on a 56.5-metre intercept grading 1.9 g/t (grams per tonne) gold from about 200 metres depth. Roughly $8 million of historical work across 87 holes, plus road, highway, and railway access, underpins the exploration plan. The four-year earn-in with Eagle Plains requires $4 million in exploration, $250,000 cash, and $1.5 million in shares. The hosts frame the sub-$2 million market cap junior as a dice-rolling speculation that could pay off quickly.

Americas Gold and Silver ($USA | $USAS): Silver and Antimony Opportunity in Idaho
- Top takeaway He sets an exit price for Americas Gold and Silver north of $50 a share, calling it a top-20 position as of December 31 that he added to after the last CEO interview, and says it is going dramatically higher over the next 2-3 years.
- He describes a 'final battle' between the S&P 500 and gold — gold tells the truth and wins while the S&P goes lower — and predicts April 2026 will be messy, with the S&P possibly sliding toward or below 6,000.
- He expects a slow-motion recession, with the Iran war as a possible trigger, persistent inflation and pressured consumer spending.
- He argues gold's fundamentals are the strongest ever because Treasuries' risk-free status is being questioned, making gold the only alternative; after buying the last dip at $4,100 gold he is waiting to buy the next dip mid-to-late April, noting silver's crash from $120 to $60 (around $72 at the April 6 recording) still has a long way to retrace.
- He says only about 15 silver producers have market caps over $100 million and only about five have real growth; he favors undervalued growers and expects 3-5 baggers on producers and 10 baggers on the growth stories.
CEO Paul Andre Huet says the turnaround is on track: silver output stepped up 50% and targets a 3.6 million ounce run rate by year end. Huet reports Galena's measured and indicated resource — the higher-confidence categories — rose 19%, with grades up 21%, past 200 million silver ounces. Huet describes a US Antimony joint venture that turns previously penalized antimony into revenue, with an Idaho plant backed by price protection. Don Durrett frames gold and the S&P 500 as a 'final battle' gold will win, urging investors to stay invested and buy dips. With about $130 million US in cash and no planned equity raise, management says drilling at Galena, Crescent, and Cosala will be funded from operations.

I interview the President of Contango Silver & Gold, Shawn Khunkhun.
- Top takeaway On camera he runs a valuation model and lands on roughly $370 to $475 per share for Contango in about five years, against a share price near $23 at the time of this April 10, 2026 interview.
- He says Contango trades at about a five-times multiple, which he calls ridiculously cheap, and argues an eight-times multiple is defensible, with ten times if the growth lands, noting most peers trade at about half of what they should.
- He names the main risk as insider ownership of only 10%, which he thinks leaves the company open to a strategic buyer circling its 65 million-plus ounces of silver.
- His gold-only scenario, which assigns no value to the silver, still implies roughly $100 to $185 per share, so he treats the silver ounces as effectively free.
- He says he bought the stock when the merger was announced because he prefers aggressive management, and rates the management team, jurisdiction and balance sheet as solid, with a five-year hold that could be a five-times move in three years if gold reaches $7,000.
Contango Silver & Gold targets growth from 60,000 ounces of gold a year to 200,000 ounces plus 5 million ounces of silver. The president credits the direct shipping ore model, trucking to Kinross' Fort Knox mill, for reaching production in two and a half years. A new mineral resource estimate for Kitsault Valley lands in June, backed by a 40,000-meter drill program targeting high-grade primary silver. The host values the company at an eight-times multiple versus today's five times, calling the discount to peers unusually wide. The channel discloses that Contango compensated the host for this interview, so viewers should weigh the praise accordingly.
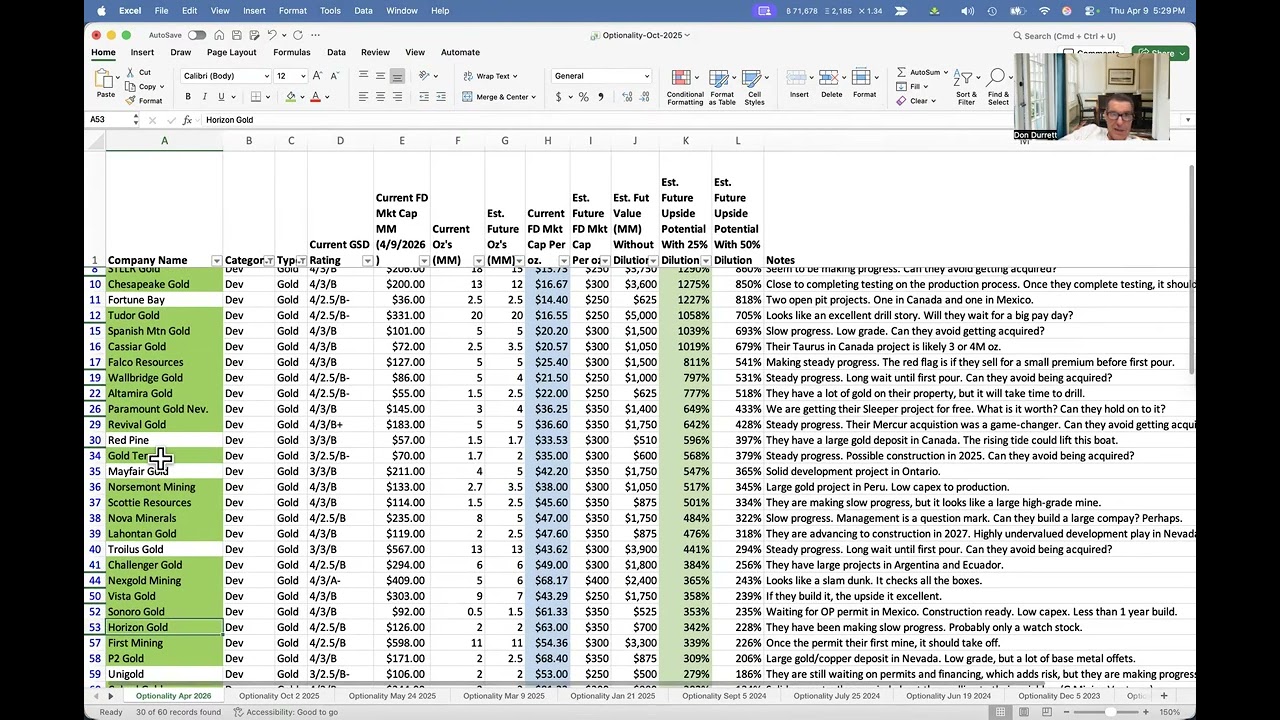
Optionality Update - April 2026
- Top takeaway Durrett's core thesis as of April 2026 is that G Mining Ventures' $2 billion takeover of G2 Goldfields at roughly $400-500 per ounce in the ground reprices the entire junior development cohort.
- He argues that if more deals close at $300-450 per ounce, optionality stocks across his 60-name list are four-baggers or better, with a rising tide lifting all of them.
- He presents a spreadsheet framework scoring each name on upside, risk/reward, quality, ounces, and upside at $5-per-ounce (silver) or roughly $300-per-ounce (gold) takeover assumptions, adjusted for 25% dilution.
- He discloses that he personally owns many of the names, including most silver developers and several gold explorers he entered early.
- He favors names with permitting or growth catalysts, notably Chesapeake's expected permit, Paramount's Sleeper project, and Freegold's 29-million-ounce resource.
G Mining Ventures' $2 billion acquisition of G2 Goldfields implies roughly $500 per ounce, resetting valuation benchmarks for Canadian gold developers. A 72% premium for an exploration-stage project lifts per-ounce benchmarks, creating optionality across junior gold and silver names. Durrett screens about 60 juniors by future ounces against market cap, applying $250-$450 gold and $5 silver in-ground price assumptions. Names like Freegold, Triumph, Falco and Cabral show multi-bagger optionality if further deals clear at $300-$450 an ounce. He expects development-stage stocks to re-rate together if upcoming acquisitions keep pricing gold in the ground near $400 per ounce.

Newsletter Favorites Upside (using New GSD Defaults)
- Top takeaway The host raised his GSD default price assumptions on the day of the video to $7,000 gold and $200 silver, from $6,000 and $150, because he sees at least an 80% probability of $7,000 gold within 24-36 months.
- He argues only two things can prevent that move — a strengthening US economy that avoids recession, or some kind of monetary reset reducing the need for gold — and he assigns both a low probability.
- On silver, he targets roughly $175-200 if gold reaches $7,000, expecting the gold-silver ratio to squeeze toward 2.5-3%, and believes any overshoot above $200 (as Michael Oliver expects) would be temporary and correct back, with $200 holding.
- Walking through his 90-stock newsletter favorites list out of about 165 holdings, he says the upside numbers at the new defaults are the best he has seen and warns the opportunity won't last long.
- He stresses timing matters: stocks needing three-to-four-year builds (like Chesapeake, Silver Tiger, Tudor) are longer-term bets, while producers like Guanajuato Silver offer immediate leverage if silver hits $200.
Raising default price assumptions to $7,000 gold and $200 silver reflects conviction that current metal prices undershoot the macro setup. Screening 90 favorite miners at those prices prints 20-plus-bagger upside for many, but most need three-to-four-year mine builds first. Near-term producers like Guanajuato Silver need no new growth, so they offer immediate leverage if silver reaches $200. A gold-silver ratio squeeze toward 2.5-3% underpins the $175-200 silver target alongside $7,000 gold within 24-36 months. Timeline to getting paid is the key filter: the longer a mine build, the longer investors must wait for the printed upside.

Shaun Heinrichs of 1911 Gold Corp. talks to Don Durrett | Metals Investor Forum | February 2026
1911 Gold Corp controls the past-producing True North mine and a district-scale land package in Manitoba's historic Rice Lake Gold District. The company's strategy focuses on restarting gold production while simultaneously expanding resources through aggressive exploration across the land package. Extensive existing infrastructure provides a significant advantage for the potential restart of operations in this historic gold camp.

Terry Harbort of Talisker Resources Ltd. talks to Don Durrett | Metals Investor Forum|February 2026
Talisker Resources is advancing the Bralorne Gold Complex in British Columbia, with the Mustang Mine currently in production and ramp-up phase. The company achieved first gold sales in August 2025 and is now planning development of its second mine, Olympus, to expand operations. As a vetted presenter at the Metals Investor Forum, Talisker showcases strong management and promising properties to potential investors.

Glenn Jessome of Silver Tiger Metals Inc. talks to Don Durrett | Metals Investor Forum | Feb 2026
Silver Tiger Metals CEO Glenn Jessome presents the El Tigre Project in Sonora, Mexico, highlighting its district-scale exploration potential and historic high-grade production. The company is focused on expanding gold and silver resources while advancing the project toward development across a century-old mining district. The Metals Investor Forum provides investors direct access to vetted junior mining management teams with strong financials and promising properties.

Brad Rourke of Scottie Resources Corp. talks to Don Durrett | Metals Investor Forum | February 2026
Scottie Resources CEO Brad Rourke presents the company's district-scale Golden Triangle gold exploration strategy at the Metals Investor Forum. The Scottie Gold Mine Project features high-grade gold mineralization with extensive historic infrastructure and ongoing expansion drilling. Forum provides investors direct access to vetted junior mining management teams pre-screened by experienced newsletter writers.

Arturo Préstamo Elizondo of Santacruz Silver Mining Ltd. talks to Don Durrett | MIF | February 2026
Santacruz Silver CEO discusses company operations across four producing mines in Bolivia and Mexico, focusing on disciplined growth and operational optimization. Interview highlights Santacruz's strategy for increasing silver and base metals production while improving operational efficiencies across its Latin American portfolio. Metals Investor Forum provides investors direct access to vetted junior mining management teams with excellent financials and promising properties.

Kimberly Ann of Lahontan Gold Corp. talks to Don Durrett | Metals Investor Forum | February 2026
Lahontan Gold Corp is advancing the Santa Fe Mine Project in Nevada's Walker Lane Trend, targeting a large-scale, open-pit, heap-leach gold and silver operation. CEO Kimberly Ann highlights the project's significant oxide resource, excellent infrastructure, and location in a premier, mining-friendly jurisdiction as key competitive advantages. The company's strategy focuses on aggressive resource expansion and advancing technical studies to demonstrate the economic viability of the project to investors.

"How To Get An Edge Buying Gold/Silver Miners" Don Durrett at the Toronto Metals Investor Forum
Don Durrett of Gold Stock Data presents strategies for gaining an edge when investing in gold and silver mining companies. The Metals Investor Forum provides investors direct access to vetted junior mining management teams with excellent financials and properties. Assessing management quality is essential for junior mining success, requiring direct interaction to ask critical questions.

Newsletter Favorites Overview (Feb 2026)
- Top takeaway Don argues there is only a little time left to buy these stocks while they are still cheap, and he expects one more significant dip that investors should prepare a buy list for.
- He says he uses $6,500 gold and $175 silver in his share-price tool - above his stated $6,000/$150 baseline, which he calls conservative - and those assumptions drive his upside multiples.
- He states he owns around 160 stocks and his Newsletter Favorites list is the 86 he would keep if forced to choose, ranked on best risk-reward.
- He predicts a mania phase is coming in which multiples go nuts, and he wants to own Australian and Canadian mid-tier producers, quality developers, and the acquisitive 'sharks' that can grow regardless.
- He reads Australian names like Ramelius reaching $8 billion as the first sign the bull market is warming up and Aussie stocks are starting to get pricey.
Durrett argues there is limited time left to buy gold and silver producers while they are still cheap, expecting one more significant dip. His Newsletter Favorites list leans on quality Canadian and Australian mid-tier producers, which he expects to re-rate as the bull market warms up. Companies whose second and third projects get no market value offer free upside — you pay for the first asset and get the rest for nothing. Cheap forward free-cash-flow multiples persist in West Africa and among silver producers, where weak sentiment discounts heavy leverage to metal prices. Australian producers like Ramelius reaching major-sized valuations is, in his view, the first sign the junior gold bull market is broadening.
Key Quotes
"Is the stock market telling the truth at an all-time high, or is it gold that's telling the truth? Well, it's pretty obvious that gold is the one telling the truth."
"You're projecting what that price will be. And so you're saying when the market collapses or when the bond market implodes, then you're going to see what type of functional prices are you using now."
"Gold equities are being mispriced unbelievably in today's market given the prospective rise in the metal's price."
Key Works
Available on Amazon
Specializations
Disclaimer: Don Durrett has NOT endorsed this platform and is not affiliated with Pixys in any way.