Craig Hemke
Founder and Editor | TF Metals Report | Precious Metals Market Analyst
"Macroeconomic analysis of precious metals markets and advocacy for physical gold and silver accumulation"
Biography
Craig Hemke is the founder and editor of TF Metals Report, a leading precious metals analysis platform that provides daily market commentary and technical analysis for gold and silver investors. With over a decade of experience analyzing precious metals markets, Hemke has established himself as a prominent voice in the commodity space, particularly known for his macroeconomic approach to understanding precious metals price movements.
Hemke's analytical framework combines technical analysis with deep macroeconomic insights, focusing on how Federal Reserve policy, geopolitical events, and monetary policy shifts impact gold and silver prices. He is particularly recognized for his ability to connect broader economic trends—such as yield curve control, inflation dynamics, and currency debasement—to precious metals investment opportunities. His work frequently examines the disconnect between paper and physical precious metals markets, providing investors with insights into market manipulation and true supply-demand fundamentals.
As a regular guest on major financial podcasts and platforms including Peak Prosperity, Palisades Gold Radio, and The KE Report, Hemke has built a reputation for making bold but well-reasoned predictions about precious metals markets. His 2026 forecast calling for aggressive monetary and fiscal stimulus under the Trump administration exemplifies his forward-looking approach to precious metals investing. Hemke advocates for physical precious metals accumulation as a hedge against monetary debasement, often advising investors to "keep stacking" physical gold and silver regardless of short-term price volatility.
Videos (69)

Gold and Silver at a Breaking Point: Is the Next Major Rally About to Begin? | Bob Thompson
- Top takeaway Hemke argues the market has likely reached peak hawkishness, with gold still holding above $4,000 and silver above $48 despite higher rates and a stronger dollar, suggesting a short-term floor.
- He frames gold as defensive capital preservation rather than an offensive bet, citing Eric Sprott's stated 2000 rationale that gold was bought to survive the financial crisis.
- Hemke argues miners are still at '7 o'clock' on the cycle because generalists do not yet feel performance pain from underweighting gold equities.
- He notes that Mag7 behavior — overvalued-stock M&A and capex blowouts — mirrors the mining cycle at 10 o'clock, suggesting the broader equity market is entering euphoria.
Gold and silver are finding support after a hawkish July; Bob Thompson argues extreme pessimism sets up a V-shaped recovery for miners. The guest frames miner buying as defensive wealth preservation, citing SILJ's 200% gain from the Feb 2024 'puking point' near $8. Capital rotation is what unlocks the next leg: precious metals is 1% of the S&P, so miners stay invisible until tech stocks fall. The pair maps mining-cycle signals onto tech: SpaceX and Open AI IPOs plus stock-funded M&A echo late-stage excesses that historically fail. Templeton's quote — bull markets are born on pessimism and die on euphoria — frames precious metals at '7 o'clock' with room to run.

Craig Hemke - Previewing Fed Meeting, PCE Data, Newmont Earnings
- Top takeaway He is 'bullish as ever' on gold miners long term and expects better-than-expected earnings with wide margins at around $4,400 gold and $70 silver, but warns traders will sell the strength — a stock could open up 3% on great results and finish up only 1%.
- He argues the shares trade mainly on metal-price sentiment: with gold and silver back where they were in early-to-mid November 2025, the GDX and SILJ are too, and only a metals turnaround (gold toward $5,000, silver toward $90) will lift them — after which multiples expand.
- On the Fed he sides with the roughly 84% expecting no hike at next week's meeting, thinks Warsh will eventually find reasons to cut, and flags the Jackson Hole speech as the event that sets up September.
- He expects next week's PCE to come in softer like the latest CPI and PPI (citing Nick Timiraos), but doubts it will matter because the restarted war and rising energy prices will get the improvement written off.
- He is cynical about Newmont — citing its 'bloated management' while acknowledging its bellwether status — and says the sector is back to a stock-picker's environment where researched picks should beat blanket ETF buying in the rebound.
Markets shrug off Iran war escalation; the guest argues traders have grown desensitized, with crude oil's overnight spike toward $85 quickly fading. The Fed's quiet period (a pre-meeting communications blackout) empties the calendar; markets price roughly 16% odds of a 25 basis point hike next week. PCE inflation should keep cooling like CPI and PPI did, but the guest expects war-driven energy costs to cloud the print. Newmont opens gold-miner earnings Thursday with output guided lower and AISC (all-in sustaining cost — the full cost to produce an ounce) rising. Miner shares have round-tripped to last November alongside gold and silver; the guest favors research-driven stock picking over ETFs for the rebound.

Why Gold and Silver Are Entering a Historic Supercycle as the Fed Loses Control | Nomi Prins
- Top takeaway Hemke argues gold's sharp fall over the four months to mid-July 2026 on rate-hike expectations rests on Fed 'jawboning': its real mandate is keeping markets afloat — and, as he puts it, greasing a $2-trillion-a-year deficit — not fighting inflation.
- He frames today's speculation as rhyming with the 1920s and suggests Warsh's inflation-first posture is about establishing gravitas, not a real break from Powell.
The guest argues central banks set the cost of money but cannot control real-asset inflation, leaving gold and silver as long-term stores of value. Paper silver trading in one ETF can reach 50 million ounces a day against roughly 800 million ounces of annual mine supply, per the guest. Silver is in its sixth consecutive year of structural deficit between mine extraction and real demand, according to the guest. A cited study since 1992 shows gold, gold miners, and especially junior miners beat cash and Treasuries on purchasing power. Central banks led by China have cut Treasury holdings and keep adding gold, leaving reserve percentages below historical highs, the guest says.
Criag Hemke - Busy Week Ahead: Inflation Data, Fed Testimony
- Top takeaway Hemke's central argument as of July 13, 2026: with the US deficit at $1.367 trillion for the fiscal year through June — including a $120 billion June deficit, considerably worse than last June's surplus — the government will ultimately have no choice but to cap yields to service the exponentially growing debt, so the current rate-hike talk cannot last.
- He would rather the Fed 'get it over with' — hike in July, possibly again in September, and stay hawkish at Jackson Hole — so the market can move on to what he sees as the inevitable return to cutting.
- He attributes gold's weakness to positive real interest rates: with the Fed hiking, bonds pay a return even after inflation while gold pays nothing, which he says is the rationale behind gold getting dumped even as regular equities shrug off the same rate fears.
- His call for the back half of 2026 is that metals have roughly 2-3% downside versus 15-20% upside, which he expects to extrapolate into better miner performance, while conceding he could very well be wrong.
- On positioning, he stays nearly 100% invested in his financial assets at all times — a buy-and-hold approach since he re-entered the miners in late 2015 — raised a little cash on Friday to buy Aya Gold & Silver, and would be a buyer of Agnico Eagle near $140 if he had cash to deploy.
Hemke argues record deficit spending and soaring interest costs mean the Fed cannot hike for long and will eventually cap yields. Real interest rates (returns after inflation) correlate most closely with gold, so this week's inflation data and Fed testimony could set the trend. Gold and silver sit above year-ago levels, yet miner shares have lagged badly, and Hemke sees fat margins the market ignores. Copper holds near all-time highs on long-term supply shortfalls, and rising copper tends to lift silver, which stays above breakout levels. Rather than time bottoms, Hemke stays fully invested in miners, saying the most uncomfortable moments are the best buying opportunities.

Craig Hemke – Constructive Outlook On The Precious Metals As Inflation Expectations Equilibrate
- Top takeaway Argues gold's lows are in as of early July 2026 — each dip below $4,000 was quickly bought back above that level — and that peak hawkishness will soon be priced out, setting up a second-half rally, though he expects a basing process rather than a V-shaped recovery.
- Expects a repeat of last summer's pattern, when four to five months of sideways consolidation let moving averages converge before short-duration averages crossed above longer-duration ones to launch the next bull-market leg.
- Points to the PCE energy component rising 21% from March through May as crude went from $65 to $110 as the driver of the rate-hike narrative; with crude back near $68, he expects month-over-month inflation prints to undershoot and hike expectations to unwind, with June CPI and PPI due around mid-July 2026.
- Calls the roughly 40% collapse in gold stocks a market inefficiency — even royalty companies fell as hard as energy-intensive producers — and expects Q2 producer earnings later in July and August 2026 to beat the expectations behind the May-June selling, with margins healthier than feared at $70 crude.
- Discloses a directional trade: he bought 10 GDX $80 calls expiring the third Friday of August 2026 and is holding them, expecting generalists to rotate back into the sector ahead of earnings reports.
Craig Hemke argues peak Fed hawkishness is priced in, and easing rate-hike expectations are letting gold and silver bottom and build a base. Gold snapped back above $4,000 on every dip, signaling the lows are in; he expects a sideways base, not a V-shaped recovery. A death cross (50-day moving average crossing below the 200-day) keeps rallies getting sold until sideways trade lets the averages converge. The guest argues energy-cost fear oversold producers 40-60%; energy is only 10-15% of input costs and crude has round-tripped, restoring margins. He bought GDX (the gold miners ETF) August calls, betting generalists rotate back ahead of Q2 earnings that beat depressed expectations.
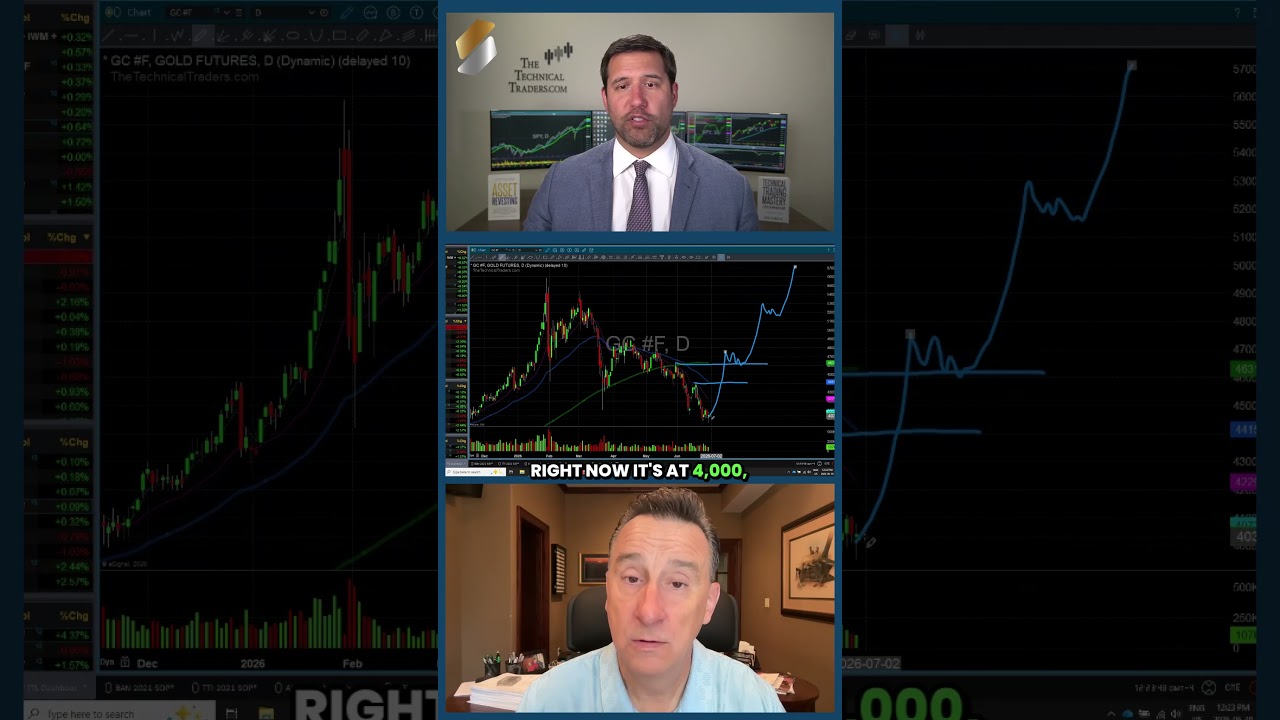
🚨 Gold's Next Move: Impulse Breakout - Chris Vermeulen #shorts
- Top takeaway Appears as the interviewer in this Sprott Money conversation, with the technical discussion delivered entirely by guest Chris Vermeulen.
Chris Vermeulen argues gold flips bullish once a powerful impulse (a strong directional surge) breaks two resistance ceilings and prints a higher high. After breaking out near $4,600, the first pause and pullback usually offers an entry point before gold's next big run. Breakouts tend to repeat through bull flags (brief consolidations that continue a trend), so investors should expect pauses, not straight lines. Gold sits near $4,000 and needs about $4,600 to break out; the speaker expects the next move significantly higher.

🚨 Silver to $40 Before the Next Rally? Chris Vermeulen Explains #shorts
Vermeulen reads silver's bounce with Fibonacci levels (chart ratios used to project price targets) and sees a drop toward $40. He argues a market event could trigger margin calls (forced selling by traders who borrowed to buy), pushing silver sharply lower. The speaker expects any $40 touch to last minutes or hours before silver rebounds into the $60 range. He frames that brief dip as a window to accumulate physical silver at a much lower price.
Gold to $8,500 After a Brutal Pullback? Chris Vermeulen’s Warning for Metals
- Top takeaway The host frames June as a hawkish surprise — he says he watched 'Warsh' expecting a more dovish outcome than the market had priced — and that it quickly trimmed about 10% off gold and nearly 20% off silver in a week, leaving both metals trying to find a base.
- He says they liquidated their S&P 500 and QQQ positions and stepped aside after taking profits near the peak, because the market is giving choppy signals and he does not yet know whether it will roll over or hand back a new buy signal.
- He reads the QQQ chart as pointing to about 20% upside, to roughly $879 if it resolves higher, and asks whether a global equity washout is the kind of event that could force margin calls and drive metals lower.
- He describes money rotating from one day to the next between mega caps, small caps, technology, dividend stocks and utilities, and reads that choppy rotation as unhealthy internal volatility and a market that may be stalling out.
- He argues that with debt and the money supply still increasing, the stock market should keep chugging higher over time, and that expanding money will help the metals at some point too.
The guest sees gold's short-term trend pointing to a sharp slide toward $3,600, a level he expects to be brief. Above that, he maps a potential impulse breakout near $4,600 and a first pullback as the better place to add physical metal. Silver, platinum and palladium share similar charts, with a fast, violent drop toward $40 framed as a short-lived buying window. Watch for an impulse move through two resistance levels: the first pause afterward is the entry before the next leg. Equities look unresolved, so he liquidated his S&P 500 and QQQ positions and is waiting for a new buy signal before re-entering.

Craig Hemke – The Precious Metals Market Has Hit “Peak Hawk”
- Top takeaway Argues 'peak hawk' is in: the Fed-driven correction likely ended with gold's break just below $4,000 long-term support, though he expects the metals to chop sideways rather than snap straight back up.
- Sees 2026 ending roughly flat, with a rally back to about $4,500 gold leaving only a 2-3% annual gain after gold rose 24% in 2024 and roughly 46% in 2025, and silver about 140% last year.
- Maintains the debt-math thesis: with roughly $2 trillion now added to US debt every year, money printing and dollar debasement should carry gold from $4,000 toward $8,000 and eventually $16,000.
- Expects crude's slide back to about $70 to pull PCE and CPI below expectations, leading the Fed to abandon hike plans, with a return to negative real rates as the trade that pushes gold back up.
- Sees an attractive moment to add mining shares for the second half of 2026 and 2027, with miners getting gold out of the ground at roughly $1,500-1,910 per ounce and still booking large profits.
Craig Hemke argues peak hawkishness has passed: falling crude oil should pull inflation readings lower and force the Fed's rate-hike expectations back down. He calls the break below the 200-day moving average (a long-term trend line) a piling-on effect, not the end of the bull market. Hemke expects gold to end 2026 roughly flat, arguing a sideways correction through time can lift price back above falling moving averages. Real interest rates — returns after inflation — drove gold's fall, he argues, and the return to negative real rates will push it back up. Miners still produce gold far below spot prices, so Hemke sees the share sell-off as a chance to add before the second half.

🚨 Eric Sprott: Why Silver Stocks Could Outperform #shorts
Eric Sprott expects silver mining stocks to outperform the precious metals sector and would buy them first as capital flows in. Silver ETFs (funds holding baskets of silver miners) give broad sector exposure, which Sprott prefers over picking a single company. Long-term conviction is central to his strategy: he keeps significant positions for years and is rarely a seller. Index inclusion creates selling liquidity for large holders whose own sales would otherwise pressure the market, Sprott notes.
🚨 Eric Sprott on Silver Supply, Demand & Market Manipulation #shorts
Silver has run a supply deficit for six consecutive years, which Sprott argues underpins the metal's strength despite the recent correction. Sprott says people from major United States banking institutions have gone to jail for manipulating the price of silver. He argues banks are effectively the only shorts in COMEX (the main silver futures exchange), so the correction inflicted heavy losses. Rapid exchange margin increases, Sprott contends, amplified the correction and blew out traders already caught on the wrong side.

Eric Sprott's CRITICAL Mid-Year 2026 Warning | Sprott Money
- Top takeaway Host Craig Hemke compares gold's pullback from about $5,500 to $4,000 with March 2008, when gold fell roughly 34% (about $1,035 to $685) in the months before the stock market crash, and asks whether history is rhyming.
- He presents a chart pricing silver against M2 money supply — growing at its fastest year-over-year pace since June 2022 — showing the January peak matched 2011, and argues silver may therefore be close to a low.
- He flags that total gold and silver open interest sits at multi-decade lows, that EFP volumes have collapsed from 25,000-30,000 a day in January 2020 to a couple hundred, and that about $1 billion of gold a day has been leaving Comex for delivery this month.
- He raises whistleblower Andrew Maguire's repeated references to Jane Street and worries a large ETF player — reportedly $39 billion in profit last year and roughly 25% of all ETF trades — could knock down Comex silver to profit across hundreds of related securities.
Sprott blames silver's January break — roughly $60 in 30 hours — on banks covering dangerous short positions ahead of massive SLV option expiries. Six straight years of silver deficits and Eastern buying near half of world supply anchor the case that prices recover from this washout. He sees AI budgets breaking at major companies and huge IPO issuance draining liquidity, leaving the stock market's last pillar looking fragile. For new money he prefers silver equities and ETFs, expecting them to run fastest, and names Highcroft's 2.6-billion-ounce resource as his top holding. Highcroft's PEA (preliminary economic assessment) pegged net asset value at $10 billion against a $2.5 billion market price, implying 300% upside.
Craig Hemke – Unusual Intra-day Swings In Gold/Silver Since Last Week - Post-War & Post-Fed Meeting
Craig Hemke argues that recent gold and silver price weakness, including potential tests of key double-bottom support levels, would not invalidate the broader precious metals bull market trend. Kevin Warsh's hawkish first Fed meeting shifted market expectations toward rate hikes, but Hemke expects any tightening to quickly reverse due to unsustainable sovereign debt levels. Low COT (Commitment of Traders) open interest is causing unusual intra-day price swings, and Hemke sees a potential summer capitulation move before the next upward leg begins.

🚨 Brien Lundin's Warning on Currency Purchasing Power #shorts
Brien Lundin argues that four decades of expanding debt and easy monetary policy are driving a sustained decline in currency purchasing power. Lundin suggests gold could eventually be reconnected to the monetary system to restore confidence as fiat currencies lose value. Silver and mining stocks are positioned to benefit directly from the long-term macroeconomic trend of weakening fiat currencies.
🚨 Why Brien Lundin Thinks This Gold Bull Market Is Different #shorts
Brien Lundin argues central bank gold buying is the primary force driving the current precious metals bull market higher. Gold's rally has featured unusually few meaningful corrections, signaling sustained structural demand rather than typical speculative momentum. Lundin sees silver and mining stocks as laggards with significant catch-up potential relative to the physical metal's strong advance.

The Biggest Gold Bull Market We'll Ever See? - Brien Lundin | Sprott Money
Brien Lundin argues that negative real interest rates (when inflation outpaces nominal rates) create the ideal macroeconomic backdrop for a sustained gold bull market. Lundin views silver's current price weakness relative to gold as a temporary dislocation, presenting a buying opportunity for investors building precious metals positions. Central bank gold accumulation and structural risks to fiat currencies underpin long-term precious metals demand, while mining equities remain undervalued relative to bullion.

ALERT: Debt Collapse In High Gear | Craig Hemke
- Top takeaway Hemke argues the Fed's only real mandate in 2026 is keeping dollars flowing, and that with a $293 billion deficit in May and interest costs annualizing near $1.3 trillion — the second largest budget line, above defense and Medicare — the US cannot afford higher interest rates as of June 16, 2026.
- He expects the incoming Fed to reach for yield curve control or new quantitative easing, with the Fed and Treasury working hand in glove as buyers of last resort, capping 10-year Treasury yields now near 4.4%.
- On his purchasing-power math, an ounce of gold took about $1,100 in 2015-16, $2,100 five years ago and roughly $4,400 as of June 15, 2026, and he projects about $8,500 in five more years, saying the next doubling will come faster than every five years.
- He rejects the expectation that the new Fed chair will be hawkish, predicting a surprisingly dovish first FOMC press conference on June 17 and room for precious metals to recover in the back half of 2026 if the conflict calms.
- He notes that in the week before June 16, 2026 the bullish percentage index on mining shares hit zero and gold sat below its 200-day moving average, treating that sentiment extreme as a reason to buy, and advises holding assets that grow faster than inflation rather than sitting in cash.
Hemke argues a $293 billion May deficit and $1.3 trillion of annual interest costs leave Washington no affordable path but cheaper money. Gold's dollar price has doubled every five years for a decade; he expects the next doubling in under five. With the Federal Reserve's rate-setting meeting under new chair Kevin Warsh ahead, he expects a surprisingly dovish tone. He expects Washington to try yield curve control, making the Fed and Treasury buyers of last resort for 10-year notes. Sentiment hit extremes — a mining-share bullish index at zero — and he says those moments are when he buys.

Will Gold Double? Fed's Real Mandate Explained | Craig Hemke
- Top takeaway The guest argues that despite the Fed's charter dual mandate, its real mandate in 2026 is to keep dollars flowing to keep the system running, which devalues the dollar and pushes gold higher.
- He notes gold has doubled roughly every five years over the last decade, and as of the June 2026 interview he does not think it will take another five years to double again.
- He warns that holding cash in a savings account earning a couple of basis points means the dollar's value is being devalued and crushed over time.
- He argues the key to successful investing and surviving through retirement is holding assets such as stocks or real estate that grow money faster than inflation.
The speaker argues the Fed's real 2026 mandate is keeping dollars flowing to sustain the system, not its stated dual mandate. Dollar purchasing-power erosion, in this view, is the core driver pushing gold prices higher over time. Gold has doubled roughly every five years for the past decade, and the speaker expects the next doubling to come sooner. Cash parked in savings earning basis points loses value to inflation; investments that outrun inflation are presented as the key to financial survival.
Craig Hemke - Is the Bull Market Back? Technicals vs. Fundamentals in Gold
- Top takeaway The guest argues the runaway US debt is the decisive driver: a $293 billion May deficit (about $10 billion a day), roughly $1.7-1.8 trillion annualized, and interest expense running near $1.3 trillion a year, which forces fiat devaluation and keeps the gold uptrend intact regardless of technicals or headlines.
- He is optimistic short term: gold and silver double-bottomed (gold near 4100, silver near 61), silver is back above its 200-day moving average, and he sees room for silver to run to 80-85 within its 65-95 range, with a break above 95 accelerating things.
- He expects the incoming Fed chair Warsh to be dovish rather than a Volcker-style hawk, citing post-WWII yield curve control and negative real rates as precedent, and thinks a 'wait and see' first meeting could be read as dovish and reverse the rate-hike fears of the past 100 days.
- On the dollar, he says its 96-100 range over 13-14 months matters mainly intraday, and a break below 98 toward 96 as the summer progresses would be very bullish for metals, as in January when the index fell 3 points in 12 days.
- He accepts a sideways year for gold would be fine — gold still around 4400 per ounce as of the episode and he expects it to double to about 8800 within five years as fiat purchasing power erodes.
Gold and silver double-bottomed near $4,100 and $61, reclaimed their 200-day moving averages, and are showing follow-through that supports a short-term bullish view. Craig Hemke argues technicals matter near-term, but the runaway growth of US debt (a $293 billion May deficit) is the enduring driver pushing gold higher. The US Dollar Index has traded sideways between 98 and 100 for over a year; a break below 98 toward 96 would act as a strong tailwind for metals. Fed chair nominee Warsh is unlikely to echo Volcker; the post-WWII playbook of yield curve control and negative real rates fits the debt-reduction need better. Even a sideways year for gold fits history: long-run gains average 9-10% annually in major currencies, and fiat devaluation math points to higher prices within five years.

Craig Hemke–Technical/Fundamental Outlook For Gold, Silver, & PM Equities After The Market Bloodbath
Hemke argues that algorithmic trading, not fundamental weakness, drove the sharp sell-off in precious metals equities despite producers reporting record Q1 earnings. Central bank gold buying remains the key structural support for prices, with China absorbing record amounts and offsetting sales from nations like Turkey. The great rotation out of US bonds and into gold creates competing forces: it underpins gold demand while simultaneously pushing interest rates higher, which pressures the metal.
Key Quotes
"A lot of the discontinuities that we're seeing in the silver market right now are due to the fact that the big exchanges like Comex may not have enough silver to satisfy the demands of futures contract holders."
— Investing News Network interview on silver market dynamics
"The way the global gold market operates; the banks have to deliver physical metal at whatever price is derived through derivative trading."
— GoldSeek Radio discussion on gold market mechanics
"The 200 day BBs on silver and miners are blown out so wide it is going to be at least 12-18 months before durable new highs can be expected."
— KE Report interview on technical outlook for precious metals
"Just be ready and keep stacking"
— Peak Prosperity interview on precious metals strategy
"The end of the Great Keynesian Experiment is upon us"
— Palisades Gold Radio forecast discussion
Key Works
Subscription-based precious metals analysis platform covering COMEX dynamics, macro trends, and mining equity commentary
Regular articles on silver price analysis, COMEX inventory dynamics, and precious metals market commentary
In-depth analysis of COMEX silver inventory tightness and the impact of algorithmic trading on junior mining shares
Daily precious metals market commentary and technical analysis platform
Comprehensive outlook on Fed policy and precious metals markets under Trump administration
Specializations
Disclaimer: Craig Hemke has NOT endorsed this platform and is not affiliated with Pixys in any way.